
The Great Austrian Economists
4. Jean-Baptiste Say: Neglected Champion of Laissez-Faire
NEGLECTED CHAMPION OF LAISSEZ-FAIRE LARRY J. SECHREST
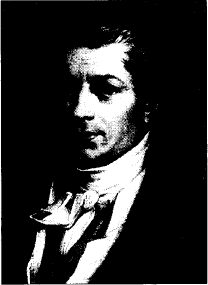
Jean-Baptiste Say 1767–1832
BEYOND SOME RUDIMENTARY facts, very little is available in English about the life of J.B. Say.1 He was born in Lyons, France, to middle-class Huguenot parents, and spent most of his early years in Geneva and London. As a young man, he returned to France in the employ of a life insurance company, and soon became an influential member of a group of strongly pro-free-market intellectuals.2 Indeed, Say was the first editor of La Décade Philosophique, a journal published by the group. After the Napoleonic Wars, he held a Chair of Political Economy at the Conservatoire des Arts et Métiers, and again, later, at the Collège de France. In addition to his famous Treatise, his works included Cours Complet d’Économie Politique Pratique and Letters to Mr. Malthus. By means of his writing, his influence spread to Italy, Spain, Germany, Russia, Latin America, Great Britain, and the United States, in which latter country his admirers included Thomas Jefferson and James Madison. His devotion to laissez-faire principles appears to have been maintained throughout his life. Say died in Paris.
J.B. Say deserves to be remembered, especially by Austrian economists, as a pivotal figure in the history of economic thought. Yet, one finds him discussed very briefly, if at all. In fact, even Austrians have devoted little attention to Say’s contributions.3
Mainstream history-of-thought texts usually mention Say only briefly, and then only in connection with his law of markets, thereby implicitly trivializing much of his work. One of the exceptions is A History of Economic Thought by Eric Roll.4 Roll treats Say with notable respect, but, unfortunately, partly because he misinterprets Say as an ancestor of modern general-equilibrium, positivistic, neoclassical economists.
In all fairness, one could argue that this lack of both attention and appreciation might be traced, at least in part, to Say himself. After all, Say did explicitly represent his work as being mainly an elaboration and popularization of Adam Smith’s Wealth of Nations for the benefit of continental European readers. Taking Say at his word, many economists seem never to have bothered to investigate more closely. Upon close reading of Say’s principal work, A Treatise on Political Economy,5 one will find that, although Say frequently praises Smith, he also departs from Smithian doctrine on a number of important points. In fact, Say even sharply criticizes Adam Smith on more than one occasion. Rather than thinking of Say as a slight variation on Smith, it is much more accurate to recognize that these two men represent two meandering, but generally divergent, paths embedded within classical economics.
Smith leads one to David Ricardo, John Stuart Mill, Alfred Marshall, Irving Fisher, John Maynard Keynes, and Milton Friedman. Say leads from A.R.J. Turgot and Richard Cantillon to Nassau Senior, Frank A. Fetter, Carl Menger, Ludwig von Mises, and Murray Rothbard. The reader should keep in mind, however, that these two paths, or progressions, have often been circuitous and nonlinear. That is to say, J.B. Say was in a number of ways truly a precursor of the Austrian School, but one must not leap to the conclusion that he was a fullfledged Austrian who was simply ahead of his time. One should not read Say and expect, at all points, to find Mises.
METHODOLOGY
Say’s approach to economics is, in philosophical terms, that of a realist and an essentialist.6 He combines a healthy skepticism regarding the usefulness of statistical investigations with an emphasis on observing the facts of reality. A statistical description “does not indicate the origin and consequences of the facts it has collected.”7 For Say, only a causal analysis based on the essential natures of the entities involved can achieve that end, and such an analysis is the core task of political economy. He sees economics as a genuine science capable of establishing “absolute truths,”8 but insists that it “has only become a science since it has been confined to the results of inductive investigation.”9 In fact, Say declares that political economy “forms a part of experimental science” and is, thus, rather similar to chemistry and natural philosophy.10
Taxonomically, he divides all facts into (a) those that refer to objects and (b) those that refer to events or interactions. The former is the domain of descriptive science (e.g., botany); while the latter is the domain of experimental science (e.g., chemistry or physics).
Above all, Say seeks to be practical; for “[n]othing can be more idle than the opposition of theory to practice!”11 To that end, he attempts always to employ language that is precise and yet as simple as possible, so that any literate, reasonably intelligent person can comprehend his meaning.12 For Say, as for most modern Austrians, economics is not a shadowy realm to be penetrated only by the expert, but a subject of enormous practical importance accessible to all. It is thus no surprise to find that Say, in keeping with such a goal of lucidity and intelligibility, criticizes Adam Smith’s Wealth of Nations for being “destitute of method,” obscure, vague, and disjointed as well as for containing too many long and distracting digressions on topics such as war, education, history, and politics.13
MONEY AND BANKING
Say’s discussion of money opens with what is now a standard argument about the “double coincidence of wants” problem and how a medium of exchange solves it. His explanation of how one highly demanded commodity spontaneously evolves into an accepted exchange medium is reminiscent of Carl Menger’s more famous treatment of the same issue,14 although it predates Menger by almost seventy years. Historically, money appears due to self-interest, not government decree, and its form should be left to the interaction of consumers’ preferences. “[C]ustom, therefore, and not the mandate of authority, designates the specific product that shall pass exclusively as money.”15
He then reviews the list of properties a medium of exchange should (ideally) possess: durability, portability, divisibility, high purchasing power per unit, and uniformity. From this presentation, Say draws the familiar conclusion that the precious metals (gold and silver) are excellent choices as monetary substances. In other words, if individuals are left free to choose, it is highly likely that they will choose a commodity money (specie). While it is true that Say is a strong proponent of gold and silver as money, it is provocative to notice that he does allow for the possibility that they could be replaced by something else if “new and rich veins of ore should be discovered.”16 In short, Say is not unalterably wedded to the proposition that “money” means gold or silver. However, if money consists of precious metal coinage, then he does agree that monetary units, such as the dollar, should be renamed in terms of the mass of gold or silver contained in the coin. For example, if a coin denominated as one French franc is supposed to contain 5 grams of silver, then it should be named “5 grams of silver,” not “one franc.”17
According to Say, the only justifiable intervention by the State into monetary matters is the minting of coins. In fact, Say thought this should be monopolized by the State “because there would probably be more difficulty in detecting the frauds of private issuers.”18 In particular, in any system in which gold and silver coexisted as monetary metals, governments should studiously avoid setting an official exchange rate between the two, contrary to what was done in historical episodes of bimetallism.19 Say clearly understood why the practice under bimetallism always led to disaster. That is, the officially overpriced money drove the officially underpriced money out of circulation, a principle known as Gresham’s Law.20 Say emphatically states that money is ruled by supply and demand, just like all commodities. Money’s purchasing power “rises and falls in proportion to the relative demand and supply.”21 Therefore, exchange rates between gold coinage and silver coinage should be allowed to change with market conditions. Say seems to favor a “parallel” metallic system, much like that suggested by Murray Rothbard.22
With regard to banking, Say distinguishes between “banks of deposit” and “banks of circulation,” but treats them both as legitimate institutions.23 The former function as warehouses for money. They hold one-hundred-percent reserves at all times, and provide convenience as well as security in that they effect transactions on behalf of their depositors by transferring funds from one customer’s account to another’s, for which services they charge a fee.24 The latter function as true financial intermediaries. They hold fractional reserves, issue banknotes, and generate an interest income by discounting promissory notes and bills of exchange. The banknotes issued by such institutions must be backed by specie or short-term securities, but if so, then “[t]he holders of the notes of a bank issuing convertible money run little or no risk, so long as the bank is well administered, and independent of the government.”25 In fact, Say even argues that these fractional-reserve-holding banks of circulation bestow a benefit upon society because they provide “the advantage of economizing capital, by reducing the amount of the sum kept in reserve.”26 And if it happens that such fractional-reserve banknotes also supplant part of the specie that had been in circulation, then “the functions of the specie, that has been withdrawn, are just as well performed by the paper substituted in its stead.”27
There are two additional insights on monetary topics that one must not overlook. First, Say emphasizes that as the division of labor extends ever farther, horizontally and vertically, through the society, that is, as individuals specialize ever more, the number and the importance of exchanges will increase. And this requires an identifiable medium of exchange. Briefly put, money is an integral part of the rise of modern civilization.28 Second, Say agrees with Mises and Rothbard, who insist that any nominal supply of money is “optimal,” as long as prices are free to adjust, because any increase or decrease in nominal terms will simply change the purchasing power per unit in inverse proportion. Thus the real money supply will remain the same.29
SAY’S LAW OF MARKETS
Without question, the one thing for which Say is best known is “Say’s Law,” also referred to as his theory of markets (la théorie des débouchés) or law of markets (loi des débouchés). This principle was, and still is, one of the key building blocks of the classical school of economics.30 It remains, in some guise or other, essential to any defense of free markets. Moreover, all collectivists attempt to refute it in the course of their assault on liberty and the free society. And yet, some writers have questioned the profundity of Say’s Law. Alexander Gray refers to “this theory, which perhaps does not come to much.”31 Even Murray Rothbard calls it a “relatively minor facet of his [Say’s] thought.”32
Most textbooks truncate Say’s Law into the transparently false proposition “supply creates its own demand.” At minimum, this should be given as “aggregate supply creates its own aggregate demand,” because the claim is not that the production of commodity X necessarily results in an equivalent demand for X, but that the production of X leads to demand for commodities A, B, C, and so forth. The production, or supply, of commodities (and complementary services) in general leads to the consumption of, or demand for, commodities (and complementary services) in general.33 It is certainly possible for there to exist either a shortage or a surplus of any particular commodity, but general overproduction or general underproduction can be no more than momentary phenomena. “It is because the production of some commodities has declined, that all other commodities are superabundant,” and such maladjusted production results from “some violent means . . . a political or natural convulsion.”34 Left to its own devices, the market will correct such imbalances.
Say identifies two means by which the corrective process operates. Principally, he argues that, though individuals do save part of the income derived from production, as long as those savings are reinvested in “productive employment,” in the aggregate there need be no decreases in production, income, or consumption.35 This process of reinvestment is fueled by differences in the profits earned by entrepreneurs. Those goods that are relatively more scarce, and thus rising in price, attract additional investment, while those that are relatively less scarce, and thus falling in price, discourage investment. And even if one hoards money or buries it, “the ultimate object is always to employ it in a purchase of some kind,”36 so there still cannot be deficient demand as long as real economic values are being produced. In order for consumers to exist, there must first be producers.
Throughout his discussion of production and consumption, Say consistently maintains that money is merely a neutral conduit through which aggregate supply is translated into aggregate demand, or “money is but the agent of the transfer of values.”37 There seems to be no recognition of the transmission mechanism by which changes in the supply of money alter the relative prices of goods and, thereby, redirect the entire interrelated structure of production. From a modern Austrian perspective, Say’s failure to grasp the non-neutrality of money must be deemed a deficiency of some note.
On the other hand, Say eloquently expresses a clear understanding that it is wholly beneficial for a society to experience generally falling prices whenever such declining prices are the result of productivity gains. Not only does this circumstance indicate, contrary to popular belief, “that a country is rich and plentiful,”38 but also that “products formerly within reach of the rich alone have been made accessible to almost every class of society.”39 Moreover, Say correctly perceives that (a) the prices of goods reflect their utility to the buyer, (b) the prices of the factors of production are derived or “imputed” from the prices of the goods produced, and therefore (c) costs of production represent an interface between the utility of the good and the productivity of the factors of production.40
ENTREPRENEURS, CAPITAL, AND INTEREST
Rothbard has suggested that the world of economics should bestow blessings upon Say for reintroducing the entrepreneur into economic thought,41 and so it should. With pen and ink, Adam Smith made the entrepreneur invisible. J.B. Say brings him back to life and to the center of the stage.42 What do these entrepreneurs do? They use their “industry” (a term Say prefers to “labor”) to organize and direct the factors of production so as to achieve the “satisfaction of human wants.”43
But they are not merely managers. They are forecasters, project appraisers, and risk-takers as well.44 Out of their own financial capital, or that borrowed from someone else, they advance funds to the owners of labor, natural resources (“land”), and machinery (“tools”). These payments, or “rents,” are recouped only if the entrepreneurs succeed in selling the product to consumers. Entrepreneurial success is not only sought after by the individual, but also essential to the society as a whole. “[A] country well stocked with intelligent merchants, manufacturers, and agriculturists has more powerful means of attaining prosperity, than one devoted chiefly to the pursuit of the arts and sciences.”45
Say’s use of the word “capital” can be confusing, because it is used to mean, as the context requires, either (a) capital goods that are integral to the production of further, final goods, or (b) the financial capital that constitutes the enterprise’s funding.46 The former are the result of some earlier production process and, when combined with the industry of the entrepreneur, generate profit (or loss). The latter is the result of saving some portion of the income from past productive activity and generates interest.
The analysis of interest rates is very perceptive and, in most respects, remarkably Austrian. First, Say realizes that the interest rate is not the price of money, but the price of credit, or “capital lent.”47 Therefore, it is false that “the abundance or scarcity of money regulates the rate of interest.”48 Of course, Say is thinking of the real rate of interest, not the nominal, or market, rate. He also clearly sees that interest rates will include some risk premium as a sort of insurance to protect against loss due to default.49 Such a risk premium will become very large when, for example, laws are imposed so that creditors have no legal recourse against a debtor who defaults.50 Furthermore, Say identifies the fact that there are “political risk” differentials between nations that lead to an international array of nominal interest rates.51 Overall, in terms of public policy, Say adopts the same stance with regard to credit markets that he exhibits elsewhere: namely, the state should not meddle. The “rate of interest ought no more to be restricted, or determined by law, than . . . the price of wine, linen, or any other commodity.”52
It has been argued that the one glaring flaw in Say’s understanding of interest rates is his failure to anchor them on the bedrock of “time preferences,”53 that is, to explain interest rates as founded on the rate at which individuals prefer to trade present goods for future goods.54 While Say does indeed fail explicitly to connect interest rates with time preferences, he seems to possess at least an embryonic notion of time preference itself. He observes, for instance, that there often exists an “inducement to every one to consume the whole of his income . . . [during] times of political turbulence and confusion.”55 And when discussing the impact of increased frugality (a falling rate of time preference?) on the accumulation of capital, he even concludes that “the low rate of interest proves the existence of more abundant capital.”56
VALUE AND UTILITY
For Say, the foundation of value is utility or the capacity of a good or service to satisfy some human desire. Those desires—and the preferences, expectations, and customs that lie behind them—must be taken as givens, as data, by the analyst. The task is to reason from those data. Say is most emphatic in denying the claims of Adam Smith, David Ricardo, and others that the basis for value is labor, or “productive agency.”57 Economists who subscribe to a labor theory of value have the matter precisely backwards. “[I]t is the ability to create the utility . . . that gives value to productive agency.”58
The two categories of value are “exchange-value” and “use-value.”59 Exchange-value lies within the domain of economics, because it is a measure of what one must give up in order to acquire a good in the market. In economic terms, “[t]he only fair criterion of the value of an object is, the quantity of other commodities at large, that can be readily obtained for it in exchange.”60 Those things which possess exchange-value would today be called “economic goods,” but Say calls them “social wealth.” In contrast, some things, such as air, water, and sunlight, possess only use-value, because they are present in such abundance that they cannot command a price. These are now known as “free goods,” but Say labels them “natural wealth.”61
Unfortunately, by adhering to the above taxonomy of values, Say plunges into a most regrettable error. He concludes that since the measure of a good’s economic value is literally and precisely its market price,62 then all market transactions must involve the exchange of equal values. This, of course, must imply that neither buyer nor seller gains. Or, in other words, all market transactions are a “zero-sum game.” “When Spanish wine is bought at Paris, equal value is really given for equal value: the silver paid, and the wine received, are worth one the other.”63 Austrians are adamant in maintaining that exchanges, as long as they are voluntary, must be mutually beneficial in terms of the expected utilities of each the buyer and the seller. If that is not the case, then why would buyer and seller agree to trade?
TAXES AND THE STATE
Nowhere is Say’s radicalism more evident than in his critique of government intervention into the economy.64 Most succinctly stated, he declares that self-interest and the search for profits will push entrepreneurs toward satisfying consumer demand. “[T]he nature of the products is always regulated by the wants of society,” therefore “legislative interference is superfluous altogether.”65
Say’s comments on one particular series of legislative acts is very instructive. The first of the British Navigation Acts was passed in 1581; these Acts were strengthened in 1651 and 1660; and the last was not repealed until 1849. Their purpose was to reserve Britain’s international trade exclusively for the shipowners of the British merchant marine. Say argues that such monopolization of the “carrying trade” diminishes national wealth because it often reduces the profits of those merchants shipping their goods to market.
He recognizes that defenders of such statutes may grant this, but still insist that the restrictions are justified on the grounds of national security. Say retorts that this is so only if
it is an advantage to one nation to domineer over others. . . . The love of domination never attains more than a factitious elevation, that is sure to make enemies of all its neighbors. It is this that engenders national debt, internal abuse, tyranny and revolution; while the sense of mutual interest begets international kindness, extends the sphere of useful intercourse, and leads to a prosperity, permanent, because it is natural.66
The foregoing reveals how well Say comprehends the proposition that free trade and peace go hand in hand.
As for taxation, Say divides it into two types. Direct taxes are those levied on income or wealth. Indirect taxes are those such as sales taxes, excise taxes, and tariffs. Regardless of its specific form or method of collection, “all taxation may be said to injure reproduction, inasmuch as it prevents the accumulation of productive capital.”67 Therefore, contrary to what some economists have claimed, “[i]t is a glaring absurdity to pretend, that taxation . . . enriches the nation by consuming part of its wealth.”68
Today, one will find many writers who insist that high rates of taxation, and the concomitant high levels of government spending, somehow cause a society to be more prosperous. Naturally, Say knows this to be false, despite the fact that, from a statistical standpoint, prosperity and taxation may be positively correlated. He explains that such assertions commit the error of reversing cause and effect. That is, “[a] man is not rich, because he pays largely; but he is able to pay largely, because he is rich.”69 Prosperous nations, if they remain prosperous, do so despite heavy tax burdens, not because of them. Anyone who reads Say’s Treatise should not overlook the fact that the discussion of taxes and government appears in the section headed “consumption.” That is no accident, for Say does not hesitate to identify government spending as “unproductive consumption.” And “[e]xcessive taxation is a kind of suicide.”70
It is true that Say either overlooked or misunderstood certain points of theory dear to the hearts of Austrian economists. He does not believe that market exchanges represent utility gains for both buyer and seller; he does not see the relationship between interest rates and time preference; he offers no theory of business cycles. On the other hand, he is cognizant of the limitations of statistical investigations; he is very much in favor of commodity money and free banking; he knows that entrepreneurs and the accumulation of capital are essential to economic advancement; he correctly identifies both government regulation and taxation as threats to prosperity, indeed, even as threats to civil society itself.
Jean-Baptiste Say has much to offer any reader, whether Austrian or not, whether an economist or not. He saw many important truths with clarity, and wrote of them with passion and lucidity. Say once called economics “this beautiful, and above all, useful science.”71 He left economics both more beautiful and more useful than he had found it.
SELECTED READINGS
Gray, Alexander. [1931] 1961. The Development of Economic Doctrine: An Introductory Survey. London: Longmans, Green.
Kelley, David. 1986. The Evidence of the Senses: A Realist Theory of Perception. Baton Rouge: Louisiana State University Press.
Menger, Carl. [1871] 1976. Principles of Economics. Translated by James Dingwall and Bert F. Hoselitz. New York: New York University Press.
Mises, Ludwig von. [1957] 1969. Theory and History: An Interpretation of Social and Economic Evolution. New Rochelle, N.Y.: Arlington House.
—. [1960] 1976. Epistemological Problems of Economics. Translated by George Reisman. New York: New York University Press.
—. [1949] 1966. Human Action: A Treatise on Economics. Chicago: Henry Regnery.
Palmer, R.R. 1997. J.B. Say: An Economist in Troubled Times. Princeton, N.J.: Princeton University Press.
Reisman, George. 1996. Capitalism: A Treatise on Economics. Ottawa, Ill.: Jameson Books.
Roll, Eric. [1956] 1961. A History of Economic Thought. Englewood Cliffs, N.J.: Prentice-Hall.
Rothbard, Murray N. [1962] 1993. Man, Economy, and State. Auburn, Ala.: Ludwig von Mises Institute.
—. [1962] 1991. The Case for a 100 Percent Gold Dollar. Auburn, Ala.: Ludwig von Mises Institute.
—. 1983. The Mystery of Banking. New York: Richardson and Snyder.
—. [1970] 1977. Power and Market: Government and the Economy. Kansas City: Sheed Andrews and McMeel.
—. 1995. Classical Economics. Vol. 2. An Austrian Perspective on the History of Economic Thought. Cheltenham, U.K.: Edward Elgar.
Say, Jean-Baptiste. [1880] 1971. A Treatise on Political Economy: or the Production, Distribution and Consumption of Wealth. Translated by C.R. Prinsep and Clement C. Biddle. New York: Augustus M. Kelley.
Sowell, Thomas. 1972. Say’s Law: An Historical Analysis. Princeton, N.J.: Princeton University Press.
—. 1974. Classical Economics Reconsidered. Princeton, N.J.: Princeton University Press.
_____________
72One recent book may rectify that deficiency. See R.R. Palmer, J.B. Say: An Economist in Troubled Times (Princeton, N.J.: Princeton University Press, 1997).
73This group was inspired by the work of Abbé Etienne Bonnot de Condillac, and it included such men as Destutt de Tracy and Pierre Jean Georges Cabanis as well as Say.
74Of course, Murray N. Rothbard does discuss Say in detail and with great respect in Classical Economics, vol. 2, An Austrian Perspective on the History of Economic Thought (Cheltenham, U.K.: Edward Elgar, 1995), pp. 3–45.
75Eric Roll, A History of Economic Thought (Englewood Cliffs, N.J.: Prentice-Hall, [1956] 1961).
76This was first published in French in 1803 as Traité d Économie Politique. There were five editions of this enormously popular book published during Say’s life, the last being in 1826. See Jean-Baptiste Say, A Treatise on Political Economy: or the Production, Distribution, and Consumption of Wealth, C.R. Prinsep and Clement C. Biddle, trans. (New York: Augustus M. Kelley, [1880] 1971), p. 111. It has been translated into a number of other languages.
77It is not clear, however, whether Say adopts the Aristotelian position that “essences” are metaphysically real, that is, that particular objects “partake of” the essence of the class of objects, or the position of contextual realism that “essence” is a necessary epistemological device, but possesses no metaphysical reality. See David Kelley, The Evidence of the Senses: A Realist Theory of Perception (Baton Rouge: Louisiana State University Press, 1986).
78Say, Treatise, p. xix.
79Ibid., p. xlix.
80Ibid., p. xxxvi, emphasis added.
81Ibid., p. xviii.
82Ibid., p. xxi.
83Ibid., p. xlvi.
84Ibid., p. xliv.
85Carl Menger, Principles of Economics, James Dingwall and Bert F. Hoselitz, trans. (New York: New York University Press, [1871] 1976), pp. 257–62.
86Say, Treatise, p. 220.
87Ibid., p. 222.
88Ibid., p. 256.
89Ibid., p. 229.
90Ibid., p. 254.
91This is an application of the textbook treatment of price controls, but to money. Simultaneously, a price ceiling is imposed on one form of money and a price floor on the other. This, of course, creates a shortage of the former (that is, it disappears into savings) and a surplus of the latter (it is used for daily transactions).
92Say, Treatise, p. 226.
93Murray N. Rothbard, The Case for a 100 Percent Gold Dollar (Auburn, Ala.: Ludwig von Mises Institute, [1962] 1991), p. 28.
94This is certainly not the case with all Austrians. Murray Rothbard was especially hostile to fractional-reserve banking, and frequently condemned it as “inherently fraudulent.” See ibid., pp. 42–51; also Murray N. Rothbard, The Mystery of Banking (New York: Richardson and Snyder, 1983), pp. 97–98; and idem, Man, Economy, and State (Los Angeles: Nash Publishing, [1962] 1970), p. 700.
95Say, Treatise, pp. 268–69.
96Ibid., p. 278.
97Ibid., p. 272.
98Ibid., p. 274.
99This poses a problem for Karl Marx and those other socialists who have wished to abolish money but somehow retain the productive benefits of a division of labor.
100Say, Treatise, p.151.
101See Thomas Sowell, Say’s Law: An Historical Analysis (Princeton, N.J.: Princeton University Press, 1972); idem, Classical Economics Reconsidered (Princeton, N.J.: Princeton University Press, 1974); also, George Reisman, Capitalism: A Treatise on Economics (Ottawa, Ill.: Jameson Books, 1996).
102Alexander Gray, The Development of Economic Doctrine: An Introductory Survey (London: Longmans, Green, [1931] 1961), p. 268.
103Rothbard, Classical Economics, p. 27.
104Say, Treatise, pp. 132–40.
105Ibid., p. 135.
106Ibid., p. 110.
107Ibid., p. 133.
108Ibid.
109Ibid., p. 303.
110Ibid., p. 288.
111Ibid., p. 287–88.
112Rothbard, Classical Economics, p. 25.
113For the benefit of those who might be reading Say’s Treatise for the first time, it should be pointed out that the commonly found text is a reprint of the American edition of 1880, and in that edition the French word “entrepreneur” is translated as “adventurer.” See Say, Treatise, p. 78n.
114Ibid., p. 83.
115Ibid., p. 82–85.
116Ibid., p. 82.
117Ibid., p. 343.
118Ibid.
119Ibid., p. 353.
120Ibid., p. 344.
121Ibid., p. 345–46.
122Ibid., p. 347.
123Ibid., p. 352.
124Rothbard, Classical Economics, p. 23.
125One might also think of this as the rate at which an individual prefers to consume now as opposed to saving for the future.
126Say, Treatise, p. 348.
127Ibid., p. 116.
128Ibid., pp. xxxi, xl, 287.
129Ibid., p. 287.
130For a discussion of value that bears some strong similarities to Say’s, see Menger, Principles, pp. 114–21, 295–302.
131Say, Treatise, p. 285.
132Ibid., p. 286.
133Ibid., p. 285.
134Ibid., p. 67.
135Murray N. Rothbard, in his Power and Market: Government and the Economy (Kansas City: Sheed Andrews and McMeel, [1970] 1977), provides a superb analysis of this issue from a modern Austrian perspective. One cannot but believe that Say would have applauded this work quite heartily.
136Say, Treatise, p. 144.
137Ibid., p. 104.
138Ibid., p. 455.
139Ibid., p. 447.
140Ibid., p. 448.
141Ibid., p. 450.
142Ibid., p. lii.
- 1Two recent examples are the review article by Israel M. Kirzner, “Entrepreneurial Discovery and the Competitive Market Process: An Austrian Approach,” Journal of Economic Literature 35, no. 1 (March 1997): 60–85; and Sherwin Rosen, “Austrian and Neoclassical Economics: Any Gains From Trade?” Journal of Economic Perspectives 11, no 4. (Fall 1997): 139–52. Both of these journals are publications of the American Economic Association, indicating the degree to which Austrian ideas are at least recognized, if not embraced, by the profession’s mainstream.
- 2See Leland B. Yeager, “Austrian Economics, Neoclassicism, and the Market Test,” Journal of Economic Perspectives 11, no. 4 (Fall 1997): 153–65, for an insightful discussion on the challenges that an alternative to mainstream ideas faces in the academic marketplace.
- 3See Karen I. Vaughn, Austrian Economics in America: The Migration of a Tradition (New York: Cambridge University Press, 1994), for a good discussion of the development of the modern Austrian School. Also see Murray N. Rothbard, “The Present State of Austrian Economics,” Money, Method, and the Austrian School, vol. 1, The Logic of Action (Cheltenham, U.K.: Edward Elgar, 1997).
- 4The first edition of Menger’s Principles of Economics was published in German in 1871. While it was generally recognized as a landmark contribution in economics, an English translation was not published until 1950.
- 5Murray N. Rothbard, in Ludwig von Mises: Scholar, Creator, Hero (Auburn, Ala.: Ludwig von Mises Institute, 1988), p. 13, notes that Mises’s early work on monetary theory, while controversial, was published in the Economic Journal, one of the leading mainstream economic journals of the time.
- 6Paul A. Samuelson, Economics, 9th ed. (New York: McGraw-Hill, 1973), p. 883.
- 7Diego de Covarrubias y Leyva, Omnia Opera (Venice, 1604),vol. 2, chap.4, p.131.
- 8Luis Saravia de la Calle, Instrucción de mercaderes (1544); republished in Colección de Joyas Bibliográficas (Madrid, 1949), p. 53. Saravia’s book addresses the business entrepreneur (in Spanish mercaderes) following a continental Catholic tradition that can be traced back to San Bernardino de Siena (1380–1444). See Rothbard, Economic Thought Before Adam Smith, pp. 81–85.
- 9Juan de Lugo (1583–1660), Disputationes de iustitia et iure (Lyon, 1642), vol. 2, d. 26, s. 4, n. 40, p. 312.
- 10Juan de Salas, Commentarii in secundam secundae D. Thomae de contractibus (Lyon, 1617), vol. 4, no. 6, p. 9.
- 11Jerónimo Castillo de Bovadilla, Práctica para corregidores (Salamanca, 1585), vol. 2, chap. 4, no. 49. See also the important comments on the scholastics and their dynamic concept of competition written by Oreste Popescu, Estudios en la historia del pensamiento económico latinoamericano (Buenos Aires: Plaza and Janés, 1987), pp. 141–59.
- 12Luis de Molina, De iustitia et iure (Cuenca, 1597), vol. 2, disp. 348, no. 4, and La teoría del justo predo, Francisco Gómez Camacho, ed. (Madrid: Editora Nacional, 1981), p. 169. Raymond de Roover, ignoring the work of Castillo de Bovadilla, acknowledges how “Molina even introduces the concept of competition by stating that concurrence or rivalry among buyers will enhance prices.” See his article “Scholastic Economics: Survival and Lasting Influence from the Sixteenth Century to Adam Smith,” Quarterly Journal of Economics 69, no. 2 (May1955): 169.
- 13Included in Covarrubias, Omnia Opera, vol. 1, pp. 669–710.
- 14Carl Menger, Principles of Economics (New York: New York University Press, 1981), p. 317.
- 15Martín Azpilcueta Navarro, Comentario resolutorio de cambios (Madrid: Consejo Superior de Investigaciones Científicas, 1965), pp. 74–75.
- 16See Jesús Huerta de Soto, “New Light on the Prehistory of the Theory of Banking and the School of Salamanca,” Review of Austrian Economics 9, no. 2 (1996): 59–81.
- 17Luis de Molina, Tratado sobre los cambios, Introduction by Francisco Gómez Camacho (Madrid: Instituto de Estudios Fiscales, 1990), p. 146. Also James Pennington’s memo dated February 13, 1826, “On the Private Banking Establishments of the Metropolis,” included as an Appendix in Thomas Tooke, A Letter to Lord Grenville; On the Effects Ascribed to the Resumption of Cash Payments on the Value of the Currency (London: John Murray, 1826).
- 18However, according to Father Bernard W. Dempsey, if the members of this second group of the School of Salamanca had had a detailed theoretical knowledge of the functioning and implications of the economic process to which fractional-reserve banking gives rise, it would have been described as a perverse, vast and illegitimate process of institutional usury, even by Molina, Lessius, and Lugo themselves. See Father Bernard W. Dempsey, Interest and Usury (Washington, D.C.: American Council of Public Affairs, 1943), p. 210.
- 19Quoted in ibid., p. 214, n. 31.
- 20Mariana, Discurso de las enfermedades de la Compañía, pp. 151–55, 216.
- 21See Leland B. Yeager, “Book Review,” Review of Austrian Economics 9, no. 1 (1996): 183, where he says:
- 22Jaime Balmes, “Verdadera idea del valor o reflexiones sobre el origen, naturaleza y variedad de los precios,” en Obras Completas (Madrid: B.A.C., 1949), vol. 5, pp. 615–24. Balmes also described the personality of Juan de Mariana with the following graphic words:
- 23Ibid., p. 51.
- 24Cantillon laid the groundwork for Turgot and the theory of profit. See Renee Prendergast, “Cantillon and the Emergence of the Theory of Profit,” History of Political Economy 23 (Fall 1991): 429.
- 25Cantillon, Essai, p. 49. His use of the word “naturally” shows that the changes he refers to cause a predictable change in price.
- 26Ibid., p. 53.
- 27Ibid., p. 31. When he refers to well-organized societies, Cantillon seems to be referring to an advanced market economy in which monetary exchange and banking services have been long and thoroughly established.
- 28Ibid., p. 97.
- 29Hülsmann, “Cantillon as a Proto-Austrian,” p. 3, defends Cantillon by noting he clearly did not think that market prices were determined by cost, in terms of land and labor, and that intrinsic value is merely being used as a measure of the quantity of land and labor. Cantillon thus avoided the errors of later economists who claimed that land and labor were measures of value. His views are similar to Austrian economists who hold that only exchange ratios and market prices permit economic calculation.
- 30Cantillon, Essai,p. 107.
- 31Hayek, “Richard Cantillon,” p. 263.
- 32Cantillon, Essai, p. 115. He does note, however, that a specific intrinsic value is one that does not change.
- 33This point was first suggested to me by Professor Hébert; see Hébert, “Was Richard Cantillon an Austrian Economist?” p. 272. Spengler also hints at this in Joseph J. Spengler, “Richard Cantillon: First of the Modems II,” Journal of Political Economy 62, no. 5 (October 1954): 407; also see Michael D. Bordo, “Some Aspects of the Monetary Economics of Richard Cantillon,” Journal of Monetary Economics 12, no. 2 (August 1983): 235–58.
- 34Cantillon, Essai, p.83.
- 35Brewer, “Cantillon and the Land Theory of Value,” p. 452; and Cantillon, Essai, p. 85.
- 36What Frenchman wouldn’t be concerned with this issue? Cantillon is clearly not against luxury per se, as he defines wealth as consumption on the first page of the Essai, including the conveniences and superfluities of life. What he is concerned with is production. It is not possible to continue to consume, or to consume greater amounts, without production. According to Cantillon, the comparative greatness of States is their reserve stock, which is savings measured in both money and materials in order to improve the State and to offset bad harvests and wars. For the State, gold is the true reserve stock, because with gold you can even buy the implements of war from your enemy. See Cantillon, Essai, pp. 89, 91.
- 37Vincent J. Tarascio, “Cantillon’s Theory of Population Size and Distribution,” Atlantic Economic Journal 9, no. 2 (July 1981): 12–18, is perceptive in noticing that Cantillon’s contribution was lost, and that neoclassical economics did not adopt the classical-population theory because real wages were clearly rising for a long time before the origins of neoclassical economics.
- 38See Cantillon, Essai, pt. 1, chaps. 7 and 8.
- 39See ibid., pt. 1, chap. 9; esp. Higgs, p. 25.
- 40Robert F. Hébert, “Richard Cantillon’s Early Contributions to Spatial Economics,” Economica 48, no. 189 (February 1981): 71–77.
- 41Hayek, Economic History, p. 264.
- 42See Bordo, “Some Aspects,” p.236; and Cantillon, Essai, pp. 111, 113.
- 43Likewise, if the money comes into the hands of spenders first, the increased consumption will stimulate investment demand and raise interest rates (as prices rise, the nominal rate will increase as well).
- 44Remember Cantillon was a banker. When he was charged with usury in the wake of the South Sea Bubble, part of his defense was to defend high interest rates.
- 45“Nothing is more amusing than the multitude of Laws and Canons made in every age on the subject of the Interest of Money, always by Wiseacres who were hardly acquainted with trade and always without effect.” Cantillon, Essai, p. 211.
- 46Anthony Brewer, “Cantillon and Mercantilism,” History of Political Economy 20, no. 3 (Fall 1988): 447–60.
- 47Hume was published before Cantillon, but we now know that Cantillon wrote before Hume, and that Hume had probably read Cantillon.
- 48Cantillon, Essai, pp.185, 323.
- 49Ibid., pp. 231, 233.
- 50Ibid., p. 319.
- 51Ibid., p. 323.
- 52See Hébert, “Was Richard Cantillon an Austrian Economist?” It is worth noting that the historians of economic thought who have hailed Cantillon’s accomplishments have been Austrian economists, such as Hayek and Rothbard, or have been fellow travelers and sympathizers, such as Schumpeter. An interesting fact is that a copy of the Essai can be found in Carl Menger’s library, and also a German language edition (1931) is in Ludwig von Mises’s library. It seems clear that the Austrian School drew much of its inspiration from Cantillon.
- 53Rothbard, Classical Economics, p. 23.
- 54One might also think of this as the rate at which an individual prefers to consume now as opposed to saving for the future.
- 55Say, Treatise, p. 348.
- 56Ibid., p. 116.
- 57Ibid., pp. xxxi, xl, 287.
- 58Ibid., p. 287.
- 59For a discussion of value that bears some strong similarities to Say’s, see Menger, Principles, pp. 114–21, 295–302.
- 60Say, Treatise, p. 285.
- 61Ibid., p. 286.
- 62Ibid., p. 285.
- 63Ibid., p. 67.
- 64Murray N. Rothbard, in his Power and Market: Government and the Economy (Kansas City: Sheed Andrews and McMeel, [1970] 1977), provides a superb analysis of this issue from a modern Austrian perspective. One cannot but believe that Say would have applauded this work quite heartily.
- 65Say, Treatise, p. 144.
- 66Ibid., p. 104.
- 67Ibid., p. 455.
- 68Ibid., p. 447.
- 69Ibid., p. 448.
- 70Ibid., p. 450.
- 71Ibid., p. lii.
- 72AT THE END of the twentieth century, the Austrian School of economics is exerting a significant influence both on the development of academic economics and on the application of economic theory to public policy. An increasing number of economics professors are sympathetic with the fundamental ideas of Austrian economics, and academic journals are taking more account of the Austrian School. A half century ago, few academic economists would even have been familiar with the Austrian School, except superficially, and among those who were, most would have disagreed with its methods and conclusions. Today, the ideas of Austrian economics are closer to the mainstream of economic thought, not because Austrian economics has changed, but because mainstream economics has moved toward the Austrian point of view. A similar shift has occurred in the public-policy arena. The policy implications of Austrian economics, once rejected as extreme, are now embraced as true. In the process, the Austrian School has become increasingly visible as an intellectual force.
- 73If the ideas of Austrian economics have made such inroads, one might wonder why, in the academic arena, Austrian economics does not play a bigger role. Part of the answer has to do with academic institutions themselves. Most university faculty teach at state institutions, which by itself may bias them toward supporting the state and being suspicious of laissez-faire ideas. Most university faculty have tenure, which slows the turnover of personnel, and perhaps of ideas. Furthermore, academic ideas find their outlets largely in academic journals, and the editorial boards of those journals tend to be controlled by the academic mainstream, further promoting mainstream ideas over alternative schools of thought. Because publication in academic journals is often a prerequisite for promotion and tenure in a university environment, academic survival often pushes young scholars in the direction of the mainstream methods and ideas in their discipline.
- 74Austrian economics has fought an uphill battle for acceptance for several reasons, but at the same time, the Austrian School has been gaining in strength, and is becoming more accepted in academia. A growing number of economics professors align themselves with the Austrian School, and even among those who do not, Austrian ideas are becoming more recognized and respected. Interestingly enough, the late-twentieth-century resurgence of interest in the Austrian School has been concentrated in the United States. This is largely due to Ludwig von Mises’s migration, and his Austrian economics seminar at New York University. One might go so far as to argue that the modern Austrian School would not exist were it not for the influence of Ludwig von Mises on his American students.
- 75Carl Menger is generally regarded as the founder of the Austrian School, but prior to about 1920, Austrian economics was not very different from economics in general. Economic theory had taken a great leap forward in the 1870s when the concept of marginal utility was independently discovered by Léon Walras, William Stanley Jevons, and Carl Menger. Each of these three individuals pushed the concept in different directions, but the integration of the marginal theory of value into economics was a major leap for all of economics. Eugen von Böhm-Bawerk’s capital theory, now seen as Austrian, was viewed more generally as a part of economics when it was published in the 1880s and 1890s, and Ludwig von Mises’s Theory of Money and Credit, published in 1912, established him as a leading authority on monetary economics.
- 76Carl Menger is generally regarded as the founder of the Austrian School, but prior to about 1920, Austrian economics was not very different from economics in general. Economic theory had taken a great leap forward in the 1870s when the concept of marginal utility was independently discovered by Léon Walras, William Stanley Jevons, and Carl Menger. Each of these three individuals pushed the concept in different directions, but the integration of the marginal theory of value into economics was a major leap for all of economics. Eugen von Böhm-Bawerk’s capital theory, now seen as Austrian, was viewed more generally as a part of economics when it was published in the 1880s and 1890s, and Ludwig von Mises’s Theory of Money and Credit, published in 1912, established him as a leading authority on monetary economics.
- 77From its low point in the middle of the twentieth century, Austrian economics has continued to gain visibility both inside academia and out. F.A. Hayek won the Nobel prize in economics in 1974, giving the Austrian School attention and respectability. By then, a small Austrian revival was already underway, led by Kirzner and Rothbard, and Hayek’s Nobel prize gave the revival additional momentum. Still, the Austrian School was branded by being on the losing side of the socialist calculation debate. In 1973, the year Mises died, Paul Samuelson, another Nobel laureate in economics and among the most prominent of mainstream academic economists, argued in his introductory textbook that even though the Soviet Union had roughly half the per capita income of the United States, their superior economic system based on central planning gave them faster growth. Based on this, Samuelson projected that per capita income in the Soviet Union could catch up to that of the United States as early as 1990, and almost surely by 2015. Keep in mind that Samuelson’s projection was in his best-selling introductory college textbook, and was the standard line taught in college classrooms at the time. Clearly, the mainstream had not accepted the ideas of Austrian economics.
- 78We should note how Mariana refers to the fact that the “common estimation” of men is the origin of the value of things, thus following the traditional subjectivist doctrine of the scholastics, which was initially proposed by Diego de Covarrubias y Leyva. Covarrubias (1512–1577), the son of a famous architect, became bishop of the city of Segovia and a minister to King Philip II. In 1554, he set forth better than anyone before the subjectivist theory of value, stating that “the value of an article does not depend on its essential nature but on the subjective estimation of men, even if that estimation is foolish,” illustrating his thesis with the example that “in the Indies wheat is dearer than in Spain because men esteem it more highly, though the nature of the wheat is the same in both places.”
- 79Covarrubias’s subjectivist conception was completed by another of his scholastic contemporaries, Luis Saravia de la Calle, who was the first to demonstrate that prices determine costs, not vice versa. Saravia de la Calle also had the special distinction of writing in Spanish, not in Latin. Its title was Instrucción de mercaderes (Instruction to merchants), and there we can read that “those who measure the just price by the labor, costs and risk incurred by the person who deals in the merchandise are greatly in error. The just price is found not by counting the cost but by common estimation.”
- 80The subjectivist conception initiated by Covarrubias also allowed other Spanish scholastics to get a clear insight of the true nature of market prices, and of the impossibility of attaining an economic equilibrium. Thus, the Jesuit Cardinal Juan de Lugo, wondering what the price of equilibrium was, as early as 1643 reached the conclusion that the equilibrium depended on such a large number of specific circumstances that only God was able to know it (“Pretium iustum mathematicum licet soli Deo notum”). Another Jesuit, Juan de Salas, referring to the possibilities of knowing specific market information, reached the very Hayekian conclusion that it was so complex that “quas exacte comprehendere et ponderare Dei est non hominum” (only God, not men, can understand it exactly).
- 81The subjectivist conception initiated by Covarrubias also allowed other Spanish scholastics to get a clear insight of the true nature of market prices, and of the impossibility of attaining an economic equilibrium. Thus, the Jesuit Cardinal Juan de Lugo, wondering what the price of equilibrium was, as early as 1643 reached the conclusion that the equilibrium depended on such a large number of specific circumstances that only God was able to know it (“Pretium iustum mathematicum licet soli Deo notum”). Another Jesuit, Juan de Salas, referring to the possibilities of knowing specific market information, reached the very Hayekian conclusion that it was so complex that “quas exacte comprehendere et ponderare Dei est non hominum” (only God, not men, can understand it exactly).
- 82Furthermore, the Spanish scholastics were the first ones to introduce the dynamic concept of competition (in Latin concurrentium), which is best understood as a process of rivalry among entrepreneurs. For instance, Jerónimo Castillo de Bovadilla (1547–?) wrote that “prices will go down as a result of the abundance, rivalry (emulación), and competition (concurrencia) among the sellers.”
- 83This same idea is closely followed by Luis de Molina. Covarrubias also anticipated many of the conclusions of Father Mariana in his empirical study on the history of the devaluation of the main coin of that time, the Castilian Maravedí. This study contained a compilation of a large number of statistics on the evolution of prices in the previous century and was published in Latin in his book Veterum collatio numismatum (Compilation on old moneys). This book was highly praised in Italy by Davanzaty and Galiani and was also quoted by Carl Menger in his Principles of Economics.
- 84This same idea is closely followed by Luis de Molina. Covarrubias also anticipated many of the conclusions of Father Mariana in his empirical study on the history of the devaluation of the main coin of that time, the Castilian Maravedí. This study contained a compilation of a large number of statistics on the evolution of prices in the previous century and was published in Latin in his book Veterum collatio numismatum (Compilation on old moneys). This book was highly praised in Italy by Davanzaty and Galiani and was also quoted by Carl Menger in his Principles of Economics.
- 85This same idea is closely followed by Luis de Molina. Covarrubias also anticipated many of the conclusions of Father Mariana in his empirical study on the history of the devaluation of the main coin of that time, the Castilian Maravedí. This study contained a compilation of a large number of statistics on the evolution of prices in the previous century and was published in Latin in his book Veterum collatio numismatum (Compilation on old moneys). This book was highly praised in Italy by Davanzaty and Galiani and was also quoted by Carl Menger in his Principles of Economics.
- 86as can be seen from experience, in France, where there is less money than in Spain, bread, wine, clothing, labor, and work cost much less; and even in Spain, at the time when there was less money, the things which could be sold and the labor and work of men were given for much less than after the Indies were discovered and covered her with gold and silver. The cause of which is that money is worth more where and when it is lacking than where and when it is in abundance.
- 87It is obvious that if Father Mariana had known the economic mechanisms that lead to the credit expansion process generated by banks and the effects of this process, he would have condemned these as robbery. He would have condemned not only the government debasement of coins but also the even more disturbing credit inflation created by banks. However, other Spanish scholastics were able to analyze the credit expansion of banks. Thus, de la Calle was very critical of fractional-reserve banking. He maintained that receiving interest was incompatible with the nature of a demand deposit, and that, in any case, a fee should be paid to the banker for keeping the money under his custody. A similar conclusion is reached by the more famous Navarro.
- 88Molina was sympathetic to fractional-reserve banking and confused the nature of two different contracts, loans and deposits, which Azpilcueta and Saravia de la Calle had clearly differentiated from each other previously. A more relevant aspect is that Molina was the first theorist to discover, in 1597 (therefore much earlier than Pennington in 1826), that bank deposits are part of the monetary supply. He even proposed the name “chirographis pecuniarium” (written money) to refer to the written documents that were accepted in trade as bank money. Our scholastics included, therefore, two incipient schools. The first is a kind of “Currency School,” formed by Saravia de la Calle, Azpilcueta Navarro, and Tomás de Mercado, who were very distrustful of banking activities, for which they implicitly demanded a one-hundred-percent reserve should be held. The second was a kind of “Banking School,” headed by the Jesuits Luis de Molina and Juan de Lugo, who were much more tolerant toward fractional-reserve banking. Both groups were to a certain extent the forerunners of the theoretical developments which were to arise three centuries later in England as a result of the debate between the Currency School and the Banking School.
- 89Molina was sympathetic to fractional-reserve banking and confused the nature of two different contracts, loans and deposits, which Azpilcueta and Saravia de la Calle had clearly differentiated from each other previously. A more relevant aspect is that Molina was the first theorist to discover, in 1597 (therefore much earlier than Pennington in 1826), that bank deposits are part of the monetary supply. He even proposed the name “chirographis pecuniarium” (written money) to refer to the written documents that were accepted in trade as bank money. Our scholastics included, therefore, two incipient schools. The first is a kind of “Currency School,” formed by Saravia de la Calle, Azpilcueta Navarro, and Tomás de Mercado, who were very distrustful of banking activities, for which they implicitly demanded a one-hundred-percent reserve should be held. The second was a kind of “Banking School,” headed by the Jesuits Luis de Molina and Juan de Lugo, who were much more tolerant toward fractional-reserve banking. Both groups were to a certain extent the forerunners of the theoretical developments which were to arise three centuries later in England as a result of the debate between the Currency School and the Banking School.
- 90that future goods are not valued so highly as the same goods available at an immediate moment of time, nor do they allow their owners to achieve the same utility. For this reason, it must be considered that they have a more reduced value in accordance with justice.
- 91Mariana concludes that, when there are many laws, “as not all of them may be kept or known, respect for all of them is lost.”
- 92Indeed, we could say that the greatest merit of Carl Menger was to rediscover and take up this continental Catholic tradition of Spanish scholastic thought that was almost forgotten and cut short as a consequence of the black legend against Spain and the very negative influence on the history of economic thought of Adam Smith and his followers of the British Classical School.
- 93It is not difficult to explain. Being the value of a thing its utility . . . if the number of units of this means increases, the need of any one of them in particular decreases; because being possible to choose among many units, none of them is indispensable. For this reason there is a necessary relation between the increase or decrease in value, and the shortage or abundance of a thing.
- 94The role of the entrepreneur is one of Cantillon’s great contributions to economic understanding. He speaks of the entrepreneur in the classic sense of the undertaker of great business adventures, but Cantillon also has a theoretical distinction between those who work for a fixed return or wages and those who face uncertain returns, including farmers, independent craftsmen, merchants, and manufacturers. These entrepreneurs purchase inputs at a given price to produce and sell later at an uncertain price. In the pursuit of profit, the entrepreneur must bear risks as he faces the pervasive uncertainty of the market. For example, the farmer has fixed expenses but:
- 95The role of the entrepreneur is one of Cantillon’s great contributions to economic understanding. He speaks of the entrepreneur in the classic sense of the undertaker of great business adventures, but Cantillon also has a theoretical distinction between those who work for a fixed return or wages and those who face uncertain returns, including farmers, independent craftsmen, merchants, and manufacturers. These entrepreneurs purchase inputs at a given price to produce and sell later at an uncertain price. In the pursuit of profit, the entrepreneur must bear risks as he faces the pervasive uncertainty of the market. For example, the farmer has fixed expenses but:
- 96The price of these products will depend partly on the weather, partly on demand; if corn is abundant relative to consumption it will be dirt cheap, if there is scarcity it will be dear. Who can foresee the number of births and deaths of the people in a State in the course of the year? Who can foresee the increase or reduction of expense that may come about in the families? And yet the price of the Farmer’s produce depends naturally upon these unforeseen circumstances, and consequently he conducts the enterprise of his farm at an uncertainty.
- 97The unsuccessful entrepreneur will live poorly or go bankrupt, while the successful entrepreneur will obtain a profit or advantage and cause entry into the market, “and so it is that the Undertakers of all kinds adjust themselves to risks in a State.” The entrepreneur brings prices and production into line with demand; in well organized societies, government officials can even fix prices of basic items without too much complaint.
- 98The unsuccessful entrepreneur will live poorly or go bankrupt, while the successful entrepreneur will obtain a profit or advantage and cause entry into the market, “and so it is that the Undertakers of all kinds adjust themselves to risks in a State.” The entrepreneur brings prices and production into line with demand; in well organized societies, government officials can even fix prices of basic items without too much complaint.
- 99Cantillon has a sophisticated understanding of the price system containing most of the elements of modern Austrian analysis. Price is determined by demand and relative scarcity. Demand is a subjective concept based on the “humors” and “fancies” of the people. It is the “consent of the people” along with the relative scarcity of a product that determines the market price, where market price is understood to be the price paid to the seller. Likewise, the market value of metals “varies with their plenty or scarcity, according to the demand.”
- 100Cantillon makes an important distinction between price and market price, and between value and market value, that has served as a source of confusion concerning the meaning of his economics. Market price and market value are the real prices that occur in the market based on forces of supply and demand. Price and value are separate and distinct concepts from market prices. They are related to Cantillon’s term “intrinsic value,” and are used to describe the opportunity cost of resources used to produce the particular good in question, the specific land and labor that were sacrificed to produce the good.
- 101in this Essai I have always used the term Intrinsic Value to signify the amount of Land and Labor which enter into Production, not having found any term more suitable to express my meaning. I mention this only to avoid misunderstanding.
- 102What is most significant about Cantillon’s achievement in the field of value and price theory is his down-playing the quest for rules and formulae that might account for the “normal” relationship between the value or price of various goods, and concentrating instead on the forces and mechanisms that are consistently at work in restoring these normal relationships.
- 103Cantillon’s conception of cost as the sacrifice of land and labor foregone is far more advanced than the land theory of cost and value advanced by the Physiocrats, or the labor theory of cost and value advanced by the classical economists. But Cantillon had a far richer understanding of cost than a simple measure of the quantity of land and labor that went into production. Cantillon stressed two important concepts throughout the Essai that provide greater depth to his conception of cost. First, Cantillon viewed all resources as heterogeneous. Each piece of land was of a different quality, and each laborer was also of a different quality. Therefore, while intrinsic value was a measure of cost, it was not possible in fact to simply count the number of hours and acres except in an abstract way or in simple illustrations. In fact, after establishing a preliminary land-and-labor theory of value in part one, he notes at the very beginning of part two that for specific goods in the real economy, it is “impossible to fix their respective intrinsic values.”
- 104The other concept that he stressed was the alternative use of resources. Land could be used to grow corn or to provide hay for horses. Labor could toil on the farm or be trained in a craft. Cantillon clearly saw that when a landlord chose to own more horses, what he was giving up was the production (and sale) of grain, and that if France wished to import fine lace, then she would have to forego a large amount of wine produced from her vineyards. Cantillon understood the concept of opportunity cost, and his Essai was an attempt to construct the concept to explain economic choice. The discovery of opportunity cost by this important precursor of the Austrian School truly marks the origin of economic theory.
- 105Cantillon took a scientific approach to population. He recognized that humans might multiply like “mice in a barn if they have unlimited means of subsistence,” or that population might fall substantially over time. Cantillon even recognized that international trade would affect the level and distribution of population, as land-poor countries could export manufactured goods to land-rich countries in return for food, fiber, and raw materials, and thus support a larger population than otherwise. Here, Cantillon is often mistakenly labeled a mercantilist, but Cantillon remains a value-free economist on the subject of population size. However, he does offer the prince technical advice of a nationalist nature on how to achieve a greater population, which supposedly is good for national defense. For example, he bemoans the export of large amounts of French wine in order to pay the very high market price of a small amount of lace imported from Brussels.
- 106Cantillon took a scientific approach to population. He recognized that humans might multiply like “mice in a barn if they have unlimited means of subsistence,” or that population might fall substantially over time. Cantillon even recognized that international trade would affect the level and distribution of population, as land-poor countries could export manufactured goods to land-rich countries in return for food, fiber, and raw materials, and thus support a larger population than otherwise. Here, Cantillon is often mistakenly labeled a mercantilist, but Cantillon remains a value-free economist on the subject of population size. However, he does offer the prince technical advice of a nationalist nature on how to achieve a greater population, which supposedly is good for national defense. For example, he bemoans the export of large amounts of French wine in order to pay the very high market price of a small amount of lace imported from Brussels.
- 107Cantillon took a scientific approach to population. He recognized that humans might multiply like “mice in a barn if they have unlimited means of subsistence,” or that population might fall substantially over time. Cantillon even recognized that international trade would affect the level and distribution of population, as land-poor countries could export manufactured goods to land-rich countries in return for food, fiber, and raw materials, and thus support a larger population than otherwise. Here, Cantillon is often mistakenly labeled a mercantilist, but Cantillon remains a value-free economist on the subject of population size. However, he does offer the prince technical advice of a nationalist nature on how to achieve a greater population, which supposedly is good for national defense. For example, he bemoans the export of large amounts of French wine in order to pay the very high market price of a small amount of lace imported from Brussels.
- 108Despite this, Cantillon’s analysis is far superior to those he influenced, like Malthus and Smith. They were concerned about population because, in their thinking, economic growth would result in a larger population of miserable people living at the subsistence level. According to Professor Tarascio, “Smith and Malthus do not reflect the spirit of Cantillon’s Essai. Hence the message has been lost to subsequent readers of the later authors.” Smith and Malthus extended the idea of the subsistence wage to industrial workers, while Cantillon recognized that there would be a tendency towards higher wages for trained workers or for those in risky occupations. In fact, Cantillon generally wrote of a maintenance wage that was not a subsistence wage at all, but rather a wage sufficient to maintain the worker in his current job. In his model, economic growth led to higher wages and a better standard of living.
- 109Despite this, Cantillon’s analysis is far superior to those he influenced, like Malthus and Smith. They were concerned about population because, in their thinking, economic growth would result in a larger population of miserable people living at the subsistence level. According to Professor Tarascio, “Smith and Malthus do not reflect the spirit of Cantillon’s Essai. Hence the message has been lost to subsequent readers of the later authors.” Smith and Malthus extended the idea of the subsistence wage to industrial workers, while Cantillon recognized that there would be a tendency towards higher wages for trained workers or for those in risky occupations. In fact, Cantillon generally wrote of a maintenance wage that was not a subsistence wage at all, but rather a wage sufficient to maintain the worker in his current job. In his model, economic growth led to higher wages and a better standard of living.
- 110Despite this, Cantillon’s analysis is far superior to those he influenced, like Malthus and Smith. They were concerned about population because, in their thinking, economic growth would result in a larger population of miserable people living at the subsistence level. According to Professor Tarascio, “Smith and Malthus do not reflect the spirit of Cantillon’s Essai. Hence the message has been lost to subsequent readers of the later authors.” Smith and Malthus extended the idea of the subsistence wage to industrial workers, while Cantillon recognized that there would be a tendency towards higher wages for trained workers or for those in risky occupations. In fact, Cantillon generally wrote of a maintenance wage that was not a subsistence wage at all, but rather a wage sufficient to maintain the worker in his current job. In his model, economic growth led to higher wages and a better standard of living.
- 111Another area in which Cantillon made an important contribution was spatial economics, a subject that permeated much of the Essai. Cantillon explained the economic geography of a state, the center of which was the capital city where the prince and government resided. Cities are regional centers with large markets and population, surrounded by market towns where the produce of the villages and farms are brought for sale. Cantillon explained that villagers bring their output to market in order to get the best price and to reduce transaction costs. He was masterful in using the role of transportation costs to explain why raw materials were more expensive near the cities, why heavy manufacturing was located near the source of raw materials, and why perishables should be produced near population centers. The role of transportation costs is a central issue in his writing on money and banking because the banker (like Cantillon himself) served as an intermediary to reduce the risk and transportation costs of shipping large amounts of money over great distances. Cantillon was the first economist to apply the principles of spatial economics in a general economic treatise. He “made original and lasting contributions to spatial economics . . . in the nature of first principles readily applicable to the fields of location theory and spatial pricing.”
- 112Cantillon’s successful career in banking played a major role in his monetary economics, which Hayek considered his greatest achievement. Cantillon was a hard-money man who understood that the nature of money as a medium of exchange drove the evolution of money to precious metals, and that princes cannot introduce imaginary money or successfully debase money. Central to his Austrian-style analysis was his rejection of the aggregate approach of the naive quantity theory of money in favor of a microeconomic-process approach to the study of the money. He showed that the type of change in the money supply and where it entered the economy were crucial to determining what the effects would be. A big gold discovery would raise the prices of goods demanded by gold mine owners and miners. Any large increase in money will give a new turn to consumption, thus changing relative prices, velocity, and the distribution of income.
- 113Cantillon’s successful career in banking played a major role in his monetary economics, which Hayek considered his greatest achievement. Cantillon was a hard-money man who understood that the nature of money as a medium of exchange drove the evolution of money to precious metals, and that princes cannot introduce imaginary money or successfully debase money. Central to his Austrian-style analysis was his rejection of the aggregate approach of the naive quantity theory of money in favor of a microeconomic-process approach to the study of the money. He showed that the type of change in the money supply and where it entered the economy were crucial to determining what the effects would be. A big gold discovery would raise the prices of goods demanded by gold mine owners and miners. Any large increase in money will give a new turn to consumption, thus changing relative prices, velocity, and the distribution of income.
- 114New money can also affect the interest rate if the money comes into the hands of lenders. Cantillon rejected the Lockean–mercantilist view that the rate of interest was a purely monetary phenomenon. Like Mises, he found that the interest rate was based on the forces of supply and demand in the market for loanable funds, and that if the new money increased supply it would lower the interest rate.
- 115Cantillon thoroughly describes the forces that cause changes in interest rates, and shows the interest rate to be a normal and important aspect of the economy. He defends the earning of high rates of interest via comparison to earning profits and rents of even higher rates. On the basis of his description of interest rates and what causes rates to be high, Cantillon ridicules the notion that government should regulate interest rates with usury laws.
- 116Cantillon thoroughly describes the forces that cause changes in interest rates, and shows the interest rate to be a normal and important aspect of the economy. He defends the earning of high rates of interest via comparison to earning profits and rents of even higher rates. On the basis of his description of interest rates and what causes rates to be high, Cantillon ridicules the notion that government should regulate interest rates with usury laws.
- 117Cantillon presented a theory of the business cycle very similar to the Austrian theory when he analyzed changes in the money supply. Increased money supply is the boom phase that kicks off the business cycle. His descriptions of this phase of the cycle are what many commentators have used to label Cantillon a mercantilist, because more money is seen as leading to a higher level of economic activity However, problems sooner or later arise. The basic problem revolves around price inflation and the collapse of domestic industry. Cantillon’s Austrian lesson is that mercantilist policy is a shortrun expediency that fails in the long run.
- 118Cantillon was the first to describe the workings of the famous specie-flow price mechanism, a crucial component of the Austrian theory of the business cycle, normally attributed to Hume. Here he analyzes changes in the domestic money supply brought about by changes in the balance of payments in a similar fashion to changes in the domestic gold supply described above. He suggests ways in which the prince might try to offset the negative effects of monetary inflation or to forestall them, but theoretically the reversal is inevitable, and Cantillon is not confident in the government’s ability to micromanage the adjustment process.
- 119Cantillon was the first to describe the workings of the famous specie-flow price mechanism, a crucial component of the Austrian theory of the business cycle, normally attributed to Hume. Here he analyzes changes in the domestic money supply brought about by changes in the balance of payments in a similar fashion to changes in the domestic gold supply described above. He suggests ways in which the prince might try to offset the negative effects of monetary inflation or to forestall them, but theoretically the reversal is inevitable, and Cantillon is not confident in the government’s ability to micromanage the adjustment process.
- 120In discussing the topics of foreign trade, the balance of payments, and banking, Cantillon clearly shows how countries that develop a skilled workforce in manufacturing, participate in foreign trade, and avoid national banks will prosper. However, his commentary also seems mercantilist when he laments the buying of fancy lace from Brussels as “burdensome and unprofitable to France,” and uses this as an example of how foreign trade can be usefully regulated.
- 121Cantillon showed why bimetallism would create shortages of money, and warned against the use of paper money and national banks. He also saw the problems of general banks of a public and private nature such as the South Sea Company, the Bank of England, and the yet-to-exist Federal Reserve System. He closed his Essai with an indictment of John Law and his system, which serves as a warning that continues to be important (and unheeded) to this day:
- 122It is then undoubted that a Bank with the complicity of a Minister is able to raise and support the price of public stock and to lower the rate of interest in the State at the pleasure of this Minister when the steps are taken discreetly, and thus pay off the State debt. But these refinements which open the door to making large fortunes are rarely carried out for the sole advantage of the State, and those who take part in them are generally corrupted. The excess banknotes, made and issued on these occasions, do not upset the circulation, because being used for the buying and selling of stock they do not serve for household expenses and are not changed into silver. But if some panic or unforeseen crisis drove the holders to demand silver from the Bank the bomb would burst and it would be seen that these are dangerous operations.
- 123No short essay can provide a complete picture of Richard Cantillon and his contributions to economics. For example, he presented a very good theory of prohibition; he had an excellent analysis of government debt; and he provided an interesting and useful perspective on the economics of slavery. Cantillon has been misunderstood as a mercantilist and objective (i.e., intrinsic) value theorist, but in fact he exposed the errors of mercantilism, and clearly understood the concept of opportunity cost, the fundamental principle in economic theory. Cantillon and his Essai are the origins of economic theory and that theory is clearly that of the latter-day Austrian School.
- 124It has been argued that the one glaring flaw in Say’s understanding of interest rates is his failure to anchor them on the bedrock of “time preferences,” that is, to explain interest rates as founded on the rate at which individuals prefer to trade present goods for future goods. While Say does indeed fail explicitly to connect interest rates with time preferences, he seems to possess at least an embryonic notion of time preference itself. He observes, for instance, that there often exists an “inducement to every one to consume the whole of his income . . . [during] times of political turbulence and confusion.” And when discussing the impact of increased frugality (a falling rate of time preference?) on the accumulation of capital, he even concludes that “the low rate of interest proves the existence of more abundant capital.”
- 125It has been argued that the one glaring flaw in Say’s understanding of interest rates is his failure to anchor them on the bedrock of “time preferences,” that is, to explain interest rates as founded on the rate at which individuals prefer to trade present goods for future goods. While Say does indeed fail explicitly to connect interest rates with time preferences, he seems to possess at least an embryonic notion of time preference itself. He observes, for instance, that there often exists an “inducement to every one to consume the whole of his income . . . [during] times of political turbulence and confusion.” And when discussing the impact of increased frugality (a falling rate of time preference?) on the accumulation of capital, he even concludes that “the low rate of interest proves the existence of more abundant capital.”
- 126It has been argued that the one glaring flaw in Say’s understanding of interest rates is his failure to anchor them on the bedrock of “time preferences,” that is, to explain interest rates as founded on the rate at which individuals prefer to trade present goods for future goods. While Say does indeed fail explicitly to connect interest rates with time preferences, he seems to possess at least an embryonic notion of time preference itself. He observes, for instance, that there often exists an “inducement to every one to consume the whole of his income . . . [during] times of political turbulence and confusion.” And when discussing the impact of increased frugality (a falling rate of time preference?) on the accumulation of capital, he even concludes that “the low rate of interest proves the existence of more abundant capital.”
- 127It has been argued that the one glaring flaw in Say’s understanding of interest rates is his failure to anchor them on the bedrock of “time preferences,” that is, to explain interest rates as founded on the rate at which individuals prefer to trade present goods for future goods. While Say does indeed fail explicitly to connect interest rates with time preferences, he seems to possess at least an embryonic notion of time preference itself. He observes, for instance, that there often exists an “inducement to every one to consume the whole of his income . . . [during] times of political turbulence and confusion.” And when discussing the impact of increased frugality (a falling rate of time preference?) on the accumulation of capital, he even concludes that “the low rate of interest proves the existence of more abundant capital.”
- 128For Say, the foundation of value is utility or the capacity of a good or service to satisfy some human desire. Those desires—and the preferences, expectations, and customs that lie behind them—must be taken as givens, as data, by the analyst. The task is to reason from those data. Say is most emphatic in denying the claims of Adam Smith, David Ricardo, and others that the basis for value is labor, or “productive agency.” Economists who subscribe to a labor theory of value have the matter precisely backwards. “[I]t is the ability to create the utility . . . that gives value to productive agency.”
- 129For Say, the foundation of value is utility or the capacity of a good or service to satisfy some human desire. Those desires—and the preferences, expectations, and customs that lie behind them—must be taken as givens, as data, by the analyst. The task is to reason from those data. Say is most emphatic in denying the claims of Adam Smith, David Ricardo, and others that the basis for value is labor, or “productive agency.” Economists who subscribe to a labor theory of value have the matter precisely backwards. “[I]t is the ability to create the utility . . . that gives value to productive agency.”
- 130The two categories of value are “exchange-value” and “use-value.” Exchange-value lies within the domain of economics, because it is a measure of what one must give up in order to acquire a good in the market. In economic terms, “[t]he only fair criterion of the value of an object is, the quantity of other commodities at large, that can be readily obtained for it in exchange.” Those things which possess exchange-value would today be called “economic goods,” but Say calls them “social wealth.” In contrast, some things, such as air, water, and sunlight, possess only use-value, because they are present in such abundance that they cannot command a price. These are now known as “free goods,” but Say labels them “natural wealth.”
- 131The two categories of value are “exchange-value” and “use-value.” Exchange-value lies within the domain of economics, because it is a measure of what one must give up in order to acquire a good in the market. In economic terms, “[t]he only fair criterion of the value of an object is, the quantity of other commodities at large, that can be readily obtained for it in exchange.” Those things which possess exchange-value would today be called “economic goods,” but Say calls them “social wealth.” In contrast, some things, such as air, water, and sunlight, possess only use-value, because they are present in such abundance that they cannot command a price. These are now known as “free goods,” but Say labels them “natural wealth.”
- 132The two categories of value are “exchange-value” and “use-value.” Exchange-value lies within the domain of economics, because it is a measure of what one must give up in order to acquire a good in the market. In economic terms, “[t]he only fair criterion of the value of an object is, the quantity of other commodities at large, that can be readily obtained for it in exchange.” Those things which possess exchange-value would today be called “economic goods,” but Say calls them “social wealth.” In contrast, some things, such as air, water, and sunlight, possess only use-value, because they are present in such abundance that they cannot command a price. These are now known as “free goods,” but Say labels them “natural wealth.”
- 133Unfortunately, by adhering to the above taxonomy of values, Say plunges into a most regrettable error. He concludes that since the measure of a good’s economic value is literally and precisely its market price, then all market transactions must involve the exchange of equal values. This, of course, must imply that neither buyer nor seller gains. Or, in other words, all market transactions are a “zero-sum game.” “When Spanish wine is bought at Paris, equal value is really given for equal value: the silver paid, and the wine received, are worth one the other.” Austrians are adamant in maintaining that exchanges, as long as they are voluntary, must be mutually beneficial in terms of the expected utilities of each the buyer and the seller. If that is not the case, then why would buyer and seller agree to trade?
- 134Unfortunately, by adhering to the above taxonomy of values, Say plunges into a most regrettable error. He concludes that since the measure of a good’s economic value is literally and precisely its market price, then all market transactions must involve the exchange of equal values. This, of course, must imply that neither buyer nor seller gains. Or, in other words, all market transactions are a “zero-sum game.” “When Spanish wine is bought at Paris, equal value is really given for equal value: the silver paid, and the wine received, are worth one the other.” Austrians are adamant in maintaining that exchanges, as long as they are voluntary, must be mutually beneficial in terms of the expected utilities of each the buyer and the seller. If that is not the case, then why would buyer and seller agree to trade?
- 135Nowhere is Say’s radicalism more evident than in his critique of government intervention into the economy. Most succinctly stated, he declares that self-interest and the search for profits will push entrepreneurs toward satisfying consumer demand. “[T]he nature of the products is always regulated by the wants of society,” therefore “legislative interference is superfluous altogether.”
- 136Nowhere is Say’s radicalism more evident than in his critique of government intervention into the economy. Most succinctly stated, he declares that self-interest and the search for profits will push entrepreneurs toward satisfying consumer demand. “[T]he nature of the products is always regulated by the wants of society,” therefore “legislative interference is superfluous altogether.”
- 137it is an advantage to one nation to domineer over others. . . . The love of domination never attains more than a factitious elevation, that is sure to make enemies of all its neighbors. It is this that engenders national debt, internal abuse, tyranny and revolution; while the sense of mutual interest begets international kindness, extends the sphere of useful intercourse, and leads to a prosperity, permanent, because it is natural.
- 138As for taxation, Say divides it into two types. Direct taxes are those levied on income or wealth. Indirect taxes are those such as sales taxes, excise taxes, and tariffs. Regardless of its specific form or method of collection, “all taxation may be said to injure reproduction, inasmuch as it prevents the accumulation of productive capital.” Therefore, contrary to what some economists have claimed, “[i]t is a glaring absurdity to pretend, that taxation . . . enriches the nation by consuming part of its wealth.”
- 139As for taxation, Say divides it into two types. Direct taxes are those levied on income or wealth. Indirect taxes are those such as sales taxes, excise taxes, and tariffs. Regardless of its specific form or method of collection, “all taxation may be said to injure reproduction, inasmuch as it prevents the accumulation of productive capital.” Therefore, contrary to what some economists have claimed, “[i]t is a glaring absurdity to pretend, that taxation . . . enriches the nation by consuming part of its wealth.”
- 140Today, one will find many writers who insist that high rates of taxation, and the concomitant high levels of government spending, somehow cause a society to be more prosperous. Naturally, Say knows this to be false, despite the fact that, from a statistical standpoint, prosperity and taxation may be positively correlated. He explains that such assertions commit the error of reversing cause and effect. That is, “[a] man is not rich, because he pays largely; but he is able to pay largely, because he is rich.” Prosperous nations, if they remain prosperous, do so despite heavy tax burdens, not because of them. Anyone who reads Say’s Treatise should not overlook the fact that the discussion of taxes and government appears in the section headed “consumption.” That is no accident, for Say does not hesitate to identify government spending as “unproductive consumption.” And “[e]xcessive taxation is a kind of suicide.”
- 141Today, one will find many writers who insist that high rates of taxation, and the concomitant high levels of government spending, somehow cause a society to be more prosperous. Naturally, Say knows this to be false, despite the fact that, from a statistical standpoint, prosperity and taxation may be positively correlated. He explains that such assertions commit the error of reversing cause and effect. That is, “[a] man is not rich, because he pays largely; but he is able to pay largely, because he is rich.” Prosperous nations, if they remain prosperous, do so despite heavy tax burdens, not because of them. Anyone who reads Say’s Treatise should not overlook the fact that the discussion of taxes and government appears in the section headed “consumption.” That is no accident, for Say does not hesitate to identify government spending as “unproductive consumption.” And “[e]xcessive taxation is a kind of suicide.”
- 142Jean-Baptiste Say has much to offer any reader, whether Austrian or not, whether an economist or not. He saw many important truths with clarity, and wrote of them with passion and lucidity. Say once called economics “this beautiful, and above all, useful science.” He left economics both more beautiful and more useful than he had found it.

