
Lectures on Political Economy
III. Capital Accumulation
BIBLIOGRAPHY.—The literature on this subject is very meagre. Among earlier writers there is virtually only H. von Mangoldt (Volkswirtschaftslehre), and among recent writers, Böhm-Bawerk (Positive Theorie des Kapitals), who have devoted detailed attention to the accumulation of capital. Karl Marx, Das Kapital, vol. i, section 7, Der Akkumulationsprocess des Kapitals, also deserves attention, despite his bias and exaggeration. Compare also Wagner, Grundlegung, part ii, vol. iii. In Schönberg’s Handbuch the whole theory of the accumulation of capital is despatched in a single page, and in Conrad’s Handwörterbuch der Staatswissenschaften in a single column. Cassel’s The Nature and Necessity of Interest contains a noteworthy attempt to carry discussion on some points further than had previously been done. The best material for an examination of the problem is probably to be found in the statistics of banks, and especially savings banks, as well as in statistics of capital wealth, though the latter are unfortunately extremely sparse and rudimentary.
So far, our discussion has been based on the assumption that productive capital, like the two other factors, is constant. In reality, however, capital is not, like land—and, for shorter periods, labour—physically limited. It can be increased at any moment by saving; it can be reduced by unproductive consumption. Neither is the supply of capital renewed in the same way as the supply of labour, by the work of nature—although it is natural to accumulate capital at certain periods of life (particularly middle age) and to consume it at others (early youth and old age). A rational theory of saving is thus necessary before we can clearly understand the conditions of a stationary society, with a constant supply of capital; and still more, of course, before we can understand and foresee the gradual changes in the amount of social capital.
Unfortunately, such a theory has not been worked out, and the phenomena which it should explain depend on a number of motives—partly selfish., partly altruistic, but in any case very complex. People save for themselves, but also for their successors. Some people often save merely for the pleasure of saving. Exceptional people may save and accumulate capital simply because they cannot help themselves—e.g. certain multimillionaires whose capacity for consumption even the ingenuity of the luxury industries cannot stimulate. Large families encourage thrift, because a source of income, say a landed estate, which has hitherto supported the family, may now be inadequate for that purpose. But, at the same time, a large family frequently constitutes an insuperable obstacle to saving, since every available source of income is urgently and immediately needed. On the other hand, if the capital in an individual’s possession is already so great that only a small portion of its yield is required for the maintenance and expenses of the family, then it will grow of itself—at least at present rates of interest—at such a pace that even great fecundity in the family cannot keep pace with it. The ever-growing wealth of certain multi-millionaires is therefore, from a social point of view, a not inconsiderable danger to society.
Among the many influences affecting the accumulation of capital, the rate of interest is undoubtedly one—although even its influence is uncertain and ambiguous. Theoretically, the individual should always carry his accumulation of capital (or it may be his consumption of capital) to the point at which the present and future marginal utilities of the goods saved is equal. By sacrificing one shilling this year he can, for example, count upon obtaining two shillings in ten or fifteen years. The question then becomes whether, at that time, two shillings will have more or less subjective value for him than one shilling now. The answer to this question naturally depends on a number of circumstances over which he himself can exercise some influence—such as the savings which he is likely to make during the immediate period. Here the rate of interest has a two-fold influence; a high rate increases the yield of present saving and consequently its future marginal utility, i.e. the future utility of the last unit of capital now saved1; but, on the other hand, at a given rate of saving, it makes provision for the future more ample and thus reduces the marginal utility of future goods for that individual. The latter tendency may even outweigh the former, so that, for certain individuals, a low rather than a high rate of interest may act as a spur to the accumulation of savings.
Individual saving is therefore a very complicated phenomenon. But if we consider society as a whole, and regard its average economic conditions as approximately stationary, the progressive accumulation of capital must be regarded as economical so long as any rate of interest, however low, exists. For the average individual, or rather for society as a whole (regarded as an individual who never dies), the accumulation of capital presupposes the exchange of a lower marginal utility for a higher—provided that it is not too rapid and does not absorb too much of the present means of consumption. Under such conditions, we should therefore expect a continual accumulation of capital—though at a diminishing rate—and, at the same time, a continual fall in the rate of interest.
In The Nature and Necessity of Interest, Cassel adduces certain apparently very striking reasons why a heavy fall of interest rates is not to be expected in the future. He rightly points out, in the first place, that every fall in the rate of interest causes a number of long-term investments which were previously unremunerative to become profitable; and every such large-scale absorption of free capital naturally acts as a brake on a further fall in interest rates. He especially observes that a general demand for larger houses, entailing extensive building operations, would arise if, as a result of a heavy fall in interest rates, expenditure on houses is practically restricted to the mere costs of maintenance—and site rent. To this it may be objected that larger premises, at least in our climate, involve various other outlays, especially for fuel and light, which are often as considerable as the rent itself. Increased housing accommodation for the poorer classes, however desirable it may be in itself, is therefore scarcely to be expected, unless their level of income can be raised. With certain reservations, however, this part of Cassel’s reasoning is undoubtedly correct—though it evidently sets no limit to the downward trend of the rate of interest, but only relates to the rather slow tempo at which the movement may be expected to occur.
The latter part of Cassel’s argument would be of much greater importance here—if it could be regarded as correct. He considers (in agreement with the classical economists) that, with a certain rate of interest which is not too low, the very desire or ability to accumulate capital practically disappears, so that the rate of interest could not fall lower.
The case which Cassel exclusively considers is that of a business man who in his prime has accumulated a fortune, upon the yield of which he lives after he has retired from business. If the rate of interest is sufficiently high, he can do this without in any way encroaching on his capital. He may therefore have the satisfaction, or indulge in the vanity, of leaving it undiminished, or perhaps even augmented, to his heirs: the interest alone is quite sufficient for his needs. If, on the other hand, the rate of interest should materially fall, say to 2 per cent or 1½ per cent, then, says Cassel, such conduct would usually become impossible. Either the capital must be so great that the efforts or good fortune of a single individual would seldom suffice for its accumulation; or else the mere yield in interest will be so small that he could no longer live on it without a serious change in his habits of life. He will therefore live on his capital, e.g. by the purchase of an annuity—Cassel shows, by detailed figures, how strong the temptation would be, since at so low a rate of interest he could multiply his annual income. And, says Cassel, he has a perfect moral right to do so. As a rule, he has already provided for the education of his children and perhaps for establishing them in life. He does not owe them more than that. On the contrary he may justly expect that they, in their turn, will act in the same way as he: work and accumulate a fortune during their youth and middle age, and consume it in their old age after they have provided for their children’s education.
Cassel’s argument may roughly be presented in this form. That it is correct in some cases cannot be denied, but as a general argument it can scarcely be accepted, for it is evidently based on the assumption that most fortunes are the fruit of the work of a single generation. But this is not the case even nowadays, and it evidently becomes less and less conceivable in proportion as the rate of interest falls. If we assume that the capitalist has inherited the whole or the greater part of his capital, the conclusion will be quite different. By consuming it, or even by failing to increase it, he would usually put his children in a more unfavourable position than he had himself occupied. This, however, conflicts with such an elementary impulse in human nature that we can safely assume that it will not usually occur. It is, therefore, rather difficult to imagine, even in a society based on private property, any limit below which the rate of interest could not fall, because the accumulation of capital would come to an end. We shall endeavour to show that the degree or rapidity of its fall depends mainly on an entirely different circumstance, which is scarcely mentioned by Cassel; namely the degree of probability with which we may expect the future growth of population to be on the same or a similar scale to the present.
If, however, the facts are not quite in accordance with theoretical speculations (such as those on p. 208) and if, in particular, the long-prophesied ideal of economists, in which interest will have fallen to a minimum, is tardy in its realization, the cause is presumably to be found in the following circumstances. In the first place, there is the effect of the subjective undervaluation of future needs and overvaluation of future resources, which was observed by Böhm-Bawerk. This, in turn, is primarily due to the fact that, to the individual, the future is always in a high degree uncertain. He does not know whether he himself, or those in whose well being he is most interested, will really profit by his sacrifices. Moreover, even if capital accumulation as a whole increases production, the return on individual capital accumulation, even the technical return, is uncertain. The enterprises in which capital is invested may perhaps yield large profits if they are very successful; but the chances of such success are not very great. And since, in accordance with the general law of marginal utility, the possibility of a loss of wealth outweighs, for the individual, the prospect of an equal gain, such an enterprise, from the point of view of individual business, must always be regarded as unprofitable unless the chances of gain considerably exceed those of loss. This is probably the general rule. The special inducement which hazardous enterprises offer to gambling or adventurous spirits is a compensation, but operates perhaps more in the destruction than in the accumulation of capital. In this connection, we need only call attention to the large extent to which the modern concentration of capital and the credit and insurance system stimulate and facilitate saving by levelling out and reducing these risks to a minimum.
In these respects, however, a collectivist society would afford a much better guarantee for the rapid accumulation of capital than does the existing individualistic society. The capital saved by united efforts would equally benefit all individuals and the whole of society in the future; and the failure of some enterprises would be of little importance, if those which succeeded yielded a correspondingly greater return. Though this is opposed to current opinion, it is precisely in a collectivist society that we should expect a progressive accumulation of capital until production was fully supplied with new capital and the national dividend reached its technical maximum—assuming that interest in the well-being of future generations was not less than in existing society.
Another reason why interest is still comparatively high is the fact that states destroy capital (especially in war and armaments) at the same time as it is being privately accumulated. The enormous national debts contracted by European and extra-European states in the course of years (especially for purposes of war) naturally presuppose a more or less corresponding amount of savings on the part of subscribers (though it is true that war-loan is generally issued below par); but they do not represent any really productive capital, only a claim by certain citizens on present and future generations of taxpayers. In this connection it may be asked, at least when the rate of interest begins to decline more rapidly than capital increases, and the earnings of capitalists consequently decline absolutely, whether this must not act as a brake on further capital accumulation. In purely abstract theory this would not be the case in an individualistic society in which each individual manages and saves on his own account. If a particular individual increases his capital, the effect on the rate of interest is not appreciable. The result of his saving will therefore be an unconditional gain for him. On the other hand, it cannot be denied that capitalists as a class will gladly welcome all measures destructive of capital, such as armaments and war—for which they will largely be compensated by the State’s contractual obligations, and which will help to raise the rate of interest. This constitutes a not inconsiderable political danger, as Adolf Wagner pointed out. But the collectivist state will be quite unaffected by a lowering of the rate of interest as such, since all sources of income would be more or less common to the whole community, and, in such a case, the other sources would necessarily increase in a more than corresponding degree.
But the most important reason why the rate of interest has not fallen is probably that our modern societies differ in a high degree from the stationary type. Hitherto, we have only considered capital accumulation on the assumption of completely stationary conditions; if we abandon this assumption the problem becomes essentially different. For example, if a country for some reason, such as the successive exhaustion of the land, passes from a higher to a lower degree of productivity and prosperity, then the same quantity of commodities will have, on the average, a higher marginal utility, and consequently a higher subjective value, in the future than in the present. The mere retention of consumption goods for future use thus becomes advantageous, although it cannot, of course, give rise to increased productivity and therefore cannot, in the usual sense, yield any interest. Even in our day, people always save stocks for the lean season, and it was formerly very common to save grain for bad years—a custom which in countries with bad communications, such as India and Russia, may still be necessary. If, on the other hand, a country passes from a lower to a higher degree of prosperity independently of the growth of capital (as a result of technical discoveries, etc., or when a colony is first peopled) capital accumulation may be uneconomical, even though technically it might give rise to an increased productivity of labour and land. A larger quantity of products might then represent a lower marginal utility, since prosperity as a whole had increased.
Again, if the growth of population is accompanied by an increased demand for all kinds of products, on the one hand, and by an increased supply of labour available in the future, on the other, then a capital accumulation which might have brought down the rate of interest to practically nothing under stationary conditions will not now be sufficient to do so; or will only just suffice to maintain capital at about the same relative level, for which reason it will continue to possess a high marginal productivity and to yield a high rate of interest. In addition, capital accumulation is here impeded by the number of unproductive consumers, large families, etc. If both these causes operate (increased productivity and great increase of population) as often happens in flourishing colonial lands, since, up to a certain point, the increase of population in itself brings improved technical conditions of production, the rate of interest may be incredibly high for a long period—as high as 50 per cent or more—as Adam Smith observed in the North American colonies. The marginal productivity of capital here is extremely high, yet capital is not rapidly accumulated, but remains just as inadequate in relation to demand. Everybody rightly expects that his own, or his children’s, economic condition will automatically improve in the future, and nobody therefore considers it desirable to sacrifice the moderate provision which he is able to make at present for himself and for them. Capital loans and investments from older countries with a lower rate of interest soon flow in, moreover, and counteract, in a greater or lesser degree, the conditions which we have just described.
But it is clear that these cases are all only exceptions to the rule. The unprecedented growth of population recently witnessed in Europe, and still more in certain extra-European countries, will certainly, sooner or later—probably in the course of the present century—prepare the way for much slower progress and possibly for completely stationary conditions. Then interest will also fall, and the capitalist will have to be content with quite a small share in the product—both absolutely and relatively—and perhaps (though, for the reasons given, this is somewhat improbable) with nothing at all. But this, of course, would not render capital unnecessary for production. On the contrary, it would then have attained its maximum importance; for just as land, when it is in excess, yields its products gratis or for a very low compensation, so a perfected capitalistic system of production, though in many respects very different from a primitive system without capital, nevertheless resembles the latter in that labour and land alone (or practically alone) will share the product.
Such a state, however, would be far from desirable in an individualistic society based on private property. So far from disappearing, the gulf between the propertied and the propertyless classes would be well-nigh impassable if land, capitalized at an extremely low rate of interest, possessed almost infinite exchange value. Even now, a very large part of what is commonly called capital and interest is, in reality, land and rent. Think, for example, of the colossal increase in site values, especially in the large towns. Even capital goods proper have their value increased in so far as the land incorporated in them is now re-assessed according to a higher standard of value; or, as it is said, because the cost of reproduction has increased. A large part of apparent annual savings is accounted for by this increase in the capital value of land and is thus not a real increase in wealth at all. Monopolies are another source of income of a similar kind which is not exhausted by increased capital accumulation, but rather becomes more abundant.
In his work, Om den ekonomiska fördelning och kriserna2 (1909), Brock (like Cassel) is sceptical of the possibility of a fall in the rate of interest, but nevertheless criticizes our analysis of the consequences of such a fall. According to him, it would occasion a fall in rents also, since a sufficiently low rate of interest would render practicable a number of substantial improvements to land which are now not profitable owing to the lack of cheap capital, and the supply of land for all productive purposes would become excessive; so that the fall in interest would benefit labour exclusively.
The abstract possibility of this cannot, as we have already said (see p. 164, n.), be denied; just as, on the other hand, it is not entirely inconceivable that a fall in interest might benefit landowners exclusively—in so far as the low rate of interest would mainly lead to the introduction of fixed automatic, or semiautomatic, machinery, so that human labour would become superfluous. To what extent the conditions observed by Brock are of practical importance, however, depends on circumstances which it is difficult to survey. There is no doubt that many swamps and much poor soil, not least in Sweden, could, with an unlimited supply of cheap capital, be converted into fertile fields. And if the crowding of human beings in the cities could, with the help of capital, be counteracted (by rapid and cheap communications by land, water, and air), then site values, which in certain countries already greatly exceed agricultural rents, might be lowered—though only on the assumption that the population was reduced or ceased to grow; otherwise a continued rise in rents is practically certain—and capital might grow, even relatively to population, to any extent.
Another related question which was much discussed in the past is the extent to which the unchecked progress of capital accumulation is of advantage to those who only indirectly profit by it, and especially to the labourers. The older economists usually had very exaggerated views on this point, because they supposed—on the basis of the wage-fund theory—that an increase or decrease in capital would produce a proportionate increase or decrease in wages. This, of course, is not the case. A great increase (or decrease) in capital may doubtless be associated with an insignificant change in the rates of wages, less in proportion as there exist opportunities for long-term investment. And since, in our day, the labourers often do some saving themselves, their position will, of course, be much better if somewhat higher wages enable them to save something on their own account than if the capitalist employers, by paying lower wages, were enabled to save a corresponding (or even larger) amount on their account. In the former case they are enabled to reap both the direct and the indirect profits of capital accumulation; in the latter case they have only the indirect profit, which may be very small.
In this connection, we may refer to a celebrated and very peculiar speculation of the famous German economist, von Thünen. He remarks that if the labourers themselves are willing to save and accumulate capital, then they are best served if wages are neither too high nor too low; for if they are too low, their savings will be insignificant, and if they are too high (in relation to the output of labour) the profits of capital and consequently the interest on their own savings will be so small that there will be no inducement to save.
If we call the product of labour ρ and wages l, then p—l will be the employer’s surplus, and interest (for as many years as capital remains, on the average, engaged in production) will be measured by  The labourer also must be able to count upon the same interest on his savings. If he consumes the quantity a only and saves the rest of his wages, then his income from interest on these savings will clearly be proportionate to:—
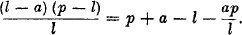
Since p and a are to be regarded as given, this equation will reach its maximum when the sum of the two negative terms (on the right-hand side) is as small as possible. But these terms have for every value of l a constant product ap; their sum therefore will be least when they are equal. Thus we obtain:—
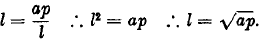
This last expression—the geometric mean of the workers’ minimum standard of life (or usual standard) and the total value of the product of labour—is therefore regarded by von Thünen as the “natural wage”—and he wished to have this formula engraved on his tombstone. We will not pause to criticize it thoroughly. In any case, the formula must be considerably modified if it is to correspond with reality. For, in the first place, the rate of interest is not reduced proportionally to the expression when l increases (which would, as will easily be seen, presuppose a constant period of production), but, as a rule, much more slowly, owing to the fact that employers react to every increase in wages by lengthening the period of production (introducing labour-saving machinery). In the second place, the interest of the labourer in his savings is not limited to the mere income which they yield, but includes the saved capital itself; he saves for furnishing his house, for his children’s education, for his old age, and so on. The most advantageous value of l is therefore probably much nearer ρ than von Thünen supposed.
What has been said may suffice to indicate, rather than to solve, the many problems associated with the question of capital accumulation—which has been so little investigated. The subject has, however, several further important and interesting phases which are related to the fact that, in our day, capital is almost always accumulated in the form of money. We shall revert to these phases when we deal with the theory of money.
On the other hand, we must be careful not to forget that money or credit is only one guise, one form, of capital accumulation. The amount of hard cash in a country can be neither increased nor decreased by saving, but remains, on the whole, constant; and credit documents of various kinds are at most only titles to material property, except in so far as they presuppose a destruction of real capital, as in the case of war-loans, etc. Real, productive, saving therefore always assumes the form of real capital. In the normal course of business this process is clearly visible. The commodities which a person foregoes by saving, and by restricting or postponing his consumption—or rather the labour and land which would otherwise have gone to the production of those commodities—he places directly (or by means of money, credit or credit-institutions) at the disposal of an entrepreneur who converts them gradually, as the savings are effected, into more or less fixed capital-goods, i.e. real capital. At the close of a boom, paper credit often seems to make up, in part (though actually it does not), for the shortage of real capital—and still more in a period of depression when investment in fixed capital hardly pays, but savings continue, though perhaps at a slower pace. The process of capital accumulation is here not a little enigmatic. It must continue in some real form, since there is no other; but in what? Further investigation of this question is highly desirable and would probably throw much light on a field which is still the darkest in the whole province of economics, namely the theory of the trade cycle (and of crises). But we cannot consider that subject here since we have, throughout, restricted our observations to the economic phenomena of equilibrium in the ordinary sense—to static analysis as distinct from dynamic.
- 1This expression is perhaps not entirely suitable, since, as will easily be seen, the essence of the argument is in both cases the same. It is therefore also possible that I ought to have endeavoured to combine sections II, 2, C and D in a single uniform presentation. I have found myself unable, however, for various reasons, to do this. As they now stand, these two collateral presentations may materially support and explain each other.
- 2Some of the matter included in this book had been published in Conrad’s Jahrbücher in the preceding year.

