
Exchange, Prices, and Production in Hyper-Inflation
XII. Business Activity and Production
CHAPTER XII
BUSINESS ACTIVITY AND PRODUCTION
§ PHYSICAL VOLUME DATA ALONE VALID
FROM data in monetary form it is clearly impossible to reach any valid general conclusions concerning the effect of inflation on German wealth and incomes. It is often alleged, for instance, that the wage earner suffered not only in being paid a sum which corresponded to the purchasing power of the currency at an earlier date but that he lost perhaps half of the real value of his pay, at the date of receipt, by reason of the necessity for spreading his expenditures over the period between pay days. The employer, on the other hand, is said to have been injured inasmuch as he had to provide for his pay roll in advance of the actual date of payment and, to do this, had to give countervalues which were greater than the purchasing power of the wages at the date they were actually paid. It is clear, however, that any change in the value of the currency unit (aside from such ulterior affects as it may have had on the physical volume of production) must have brought to someone real gains exactly compensating any losses which it entailed on others. However much distribution may be altered, the total real wealth and income of a people is not directly affected one iota by a fluctuation in the value of monetary counters. The monetary value of the wealth may change, however, not only in terms of the depreciating currency (a change inevitable in the very connotation of depreciation) but also in terms of gold or other stable money. But while the monetary value of wealth and income, expressed in the local currency, rises, its monetary value, expressed in gold, is more likely to show a fall. The latter will normally be the case when conversion into gold or foreign currency values is made at prevailing rates of exchange since those rates usually put a valuation on the depreciated currency far below that which it possesses in the country of origin. But, even when the computation in stable currency values is made according to the domestic wholesale price or cost-of-living index, the wealth of the country may seem to be declining when this is not in fact the case, because, in the prevailing uncertainty, all property tends to be capitalized at far below its earning-power value. This tendency came clearly to light in Germany in the extraordinarily low prices of stock exchange share securities throughout the whole period of inflation. Monetary data, therefore, offer a quite illusory criterion of the actual wealth and income.
The sum total of existing real wealth can be even indirectly affected by inflation only through production1 (and use) and the same is of course true of consumable income. A reasonably good impression of the real national gain or loss arising from the depreciation of the currency may therefore be obtained from a study of business activity and production in the years when inconvertible paper money held sway.
I. BUSINESS ACTIVITY
§ COMPANY FORMATIONS, BUSINESS FAILURES, EMPLOYMENT
That business in Germany was booming during most of the inflation period is a universally admitted fact. This was especially true of the year 1922 when business activity was declared to be more lively than had ever before been experienced. Evidence of the “boom” may be drawn from statistics on company formations, on business failures, and on employment.
The rate of formation of new business units is reflected in the figures on new incorporations. The number of joint-stock and limited-liability companies at the end of 1913, 1919, 1922, and 1923 is shown in Table XXIV.
This table somewhat exaggerates the degree of activity, inasmuch as many private undertakings were being converted into joint-stock or limited-liability companies, but it leaves no doubt of the general eagerness to engage in business.
Conversely, bankruptcies were greatly reduced through the depreciation of the currency. Indeed, as the rate of depreciation became accelerated, it was next to impossible for a business concern to fail. Obligations in marks tended constantly to diminish and, in addition, it was ultimately so hard to obtain credit that there was no basis for bankruptcy left. Figures on business failures are shown in Table XXV, below.
Perhaps the best index of business activity, however, is furnished by the state of employment. Partly as a result of other causes and partly as a result of inflation, there had been large accessions to the working classes, accessions which much more than balance, in numbers at any rate, the loss of workers through war casualties.2 But from the beginning of rapid depreciation of the mark in mid-1921 practically up to the time of the Ruhr invasion there was a progressive absorption of the unemployed till, in the autumn of 1922, there were only some 10,000 to 15,000 persons in the whole Reich in receipt of out-of-work relief. The figures of those in receipt of relief are not to be taken as accurately stating the absolute number of individuals out of work, but they are, nevertheless, a reliable index of the general movement of employment. The situation was better than it had ever been since the beginning of industrialization. Unemployment increased somewhat in the final months of 1922 and very greatly in early 1923 following the dislocation of industry consequent upon the occupation of the Ruhr. But within a few months the effects of even such a shock as this were largely dissipated by the persistent inflationary winds and unemployment, in the unoccupied area, again diminished from April to August 1923. Any tendency inflation may ultimately have had in curtailing business activity would seem therefore to have been postponed to within two or three months of currency stabilization. Figures on unemployment, by quarters, are given in Table XXVI.
TABLE XXIV
NUMBEROF GERMAN JOINT-STOCK AND LIMITED-LIABILITY COMPANIES IN 1913, 1919, 1922, AND 1923
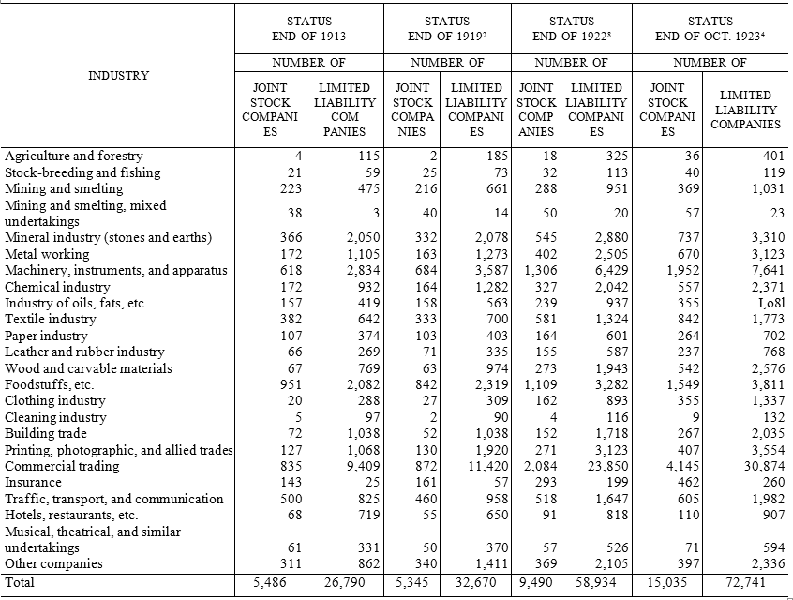
TABLE XXV
NUMBER OF BANKRUPTCIES IN GERMANY
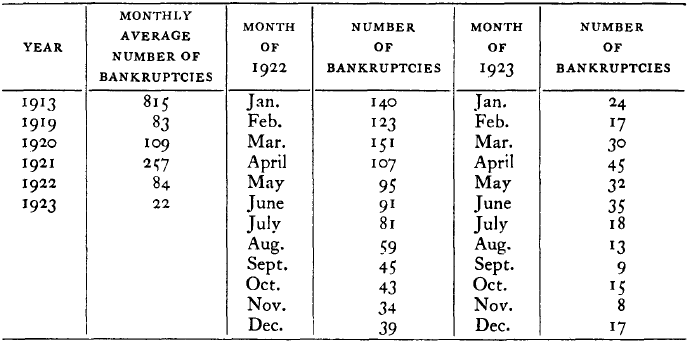
TABLE XXVI
PERCENTAGE OF TRADE UNION WORKERS UNEMPLOYED; 1913, 1920-1923
| END OF | 19136 | 1920 | 1921 | 1922 | 1923 |
| First Quarter | 2.3 | 1.9 | 3.7 | 1.1 | 5.6 |
| Second Quarter | 2.7 | 4.0 | 3.0 | 0.6 | 4.1 |
| Third Quarter | 2.7 | 4.5 | 1.4 | 0.8 | 9.9 |
| Fourth Quarter | 4.8 | 4.1 | 1.6 | 2.8 | 28.2 |
In a less tangible but equally convincing way the activity of business during the inflation years is attested by the practically unveiled opposition of the most influential business men of the time, Hugo Stinnes in particular, to proposals for currency reform. The business men were not, it is true, perfectly satisfied with the existing situation. But they were fairly content and insisted only upon the necessity of longer hours and more intense effort (for their workers) and not at all upon the need for monetary stabilization. The urge toward spending the depreciating money which affected the whole population made sales delightfully easy, and lagging costs made profits high. Why should so pleasant a status be disturbed ?
The facts on new incorporations, bankruptcies, employment, and the attitude of business men place beyond doubt the assertion that business activity was intense during most of the inflationary period. The real question is, was it productive?
II. PRODUCTION
§ FAVORABLE AND UNFAVORABLE FACTORS
So much has been written about the “apparent” prosperity of boom periods in general, and of inflationary booms in particular, and the business world is so impressed with the inevitability of depression in sequence to industrial activity, that the benefits of so-called booms, which may simply mean capacity production, are persistently minimized. A high degree of industrial activity may even become a subject of dread. The prosperity of such a period is, however, by no means merely apparent. German factory chimneys were not smoking because their owners liked to burn coal. The factories were producing goods, and production means real income however that income may be shared. It is true that product, as distinct from activity, was impaired by some causes with which inflation had nothing to do, and by some for which it was responsible, but this impairment has ordinarily been exaggerated. Furthermore, it was in part compensated by forces acting in the other direction. The several forces acting on one side or the other are noted in the succeeding paragraphs.
The factors tending to increase the total output of German industry in the post-war inflation period were :
(1) All but complete abolition of the standing army and of the navy.
(2) Employment of women in industry on a large scale. Such employment was perhaps less widespread than in the war-period but much more so than in the period prior to 1914.
(3) Elimination of the idle rich through loss of the value of fixed-interest incomes and the forced “descent” of this group into the ranks of workers.
(4) Decline in unemployment.
All of these factors operated to enhance aggregate production, through an increase in the number of workers engaged in earning occupations, but only the last three were in any measure due to inflation.
On the other hand, the productivity per worker, and therefore of the economy as a whole, tended to be reduced by :
(1) Losses of real (as distinguished from monetary) capital during and immediately after the war. This was especially marked in agriculture, where the soil and animal equipment had been exhausted, and in transportation, but it was also true of manufacturing industry.
(2) The decline in the vitality of the population as a result of the privations of war, particularly underfeeding.
(3) The “dilution” of the working population by the admission of unskilled or otherwise incapable workers. Complaints are numerous in the economic literature of the time that the tempo of industry was being greatly retarded by the forced employment of war wounded, the lack of properly trained workers, and the admission of those with no training at all.7
(4) The increase of parasitic occupations, largely speculative in character. This phenomenon may best be noted in the excessive augmentation in the number of business concerns and in the growth of trading as contrasted with industrial activities.8
(5) The rising ratio of ancillary to primarily productive workers. This was particularly prominent in governmental activity. Between 1918 and 1923 the list of Reich officials increased by 242%, that of the States by 61%, and of the municipalities by 27%.9At the latter date the total of governmental employees (which includes railroad workers) was about 43/2 million out of perhaps 30 million earners in the whole country. As inflation proceeded clerical forces were perforce greatly augmented, especially in banking and similar occupations. But the number of clerical workers in industrial life, though absolutely much increased, still remained a relatively small fraction of the whole.
Of these factors tending to diminish productivity, inflation played some part in the last three10 and the primary role in the last two.
It is impossible to gauge exactly the net effect of all these forces on the aggregate output of German industry or clearly to distinguish the influence of inflation. But it is probable that the total number of formerly voluntarily unemployed persons forced to work by the vicissitudes of the time was at least as great as the increase in the number of individuals unproductively engaged, and this, together with the larger productivity resulting from the practical elimination of unemployment (except at the very end of the period studied), should be set to the credit of inflation so far as its effect on the national income is concerned.
Total and per capita productivity in physical terms may be measured for the inflation period with as much accuracy, perhaps, as is ever present in such calculations. But to distinguish, with any precision, between such evil effects of the war as would have been present under any monetary system whatever and those which may have been due to an unstable currency is extremely difficult. A still more serious confusion arises from the occupation of the Ruhr. It will later appear that the German output in the year 1923 suffered an extraordinary decline. Part of this was certainly due to the paralyzing effect of the invasion, not only upon the industries in the Ruhr but upon all German economic life. The Ruhr is the heart of the German industrial system and the whole system felt acute distress when the action of the heart was crippled. Raw materials for the rest of German industry were suddenly cut off and a reduction in activity was inevitable. But whether the invasion was directly responsible for all, or even the greater part, of the decline is a question to which no assured answer can be given. Until late 1922 currency depreciation had been more or less orderly, and the pace, while rapid, had not been beyond possibility of prevision. The change in its character in the fall of 1922 may have turned it from a capricious but, in some respects, benign influence into a ravening and purely destructive force. Even a tehtative judgment on the respective influences of the invasion and of the collapse of the currency must be reserved until the figures for production have been examined.
§ MEASURES OF PRODUCTION
Productivity may be measured forthright or by indirection. In the immediately succeeding sections direct estimates of production will be set forth. Following this, the volume of transport, as an index of general production, will be presented. Since production and total consumption (including in the latter term the net additions to, and replacement of, capital goods) are practically equal, figures on direct consumption and on the output (and consumption) of capital goods will then be offered. Finally, the aggregate real income of the German laboring population will be examined. All the direct and indirect indices of production will then be drawn upon to furnish a composite picture of the output of German economy. The effects of inflation will be developed through a running comparison with the presumptive output under a stable monetary standard.
1. DIRECT ESTIMATES OF PRODUCTION
§ GENERAL INDICES
Indices of the physical volume of agricultural and industrial production have been calculated for Germany, and six other countries, by M. Jean Dessirier and have been published in the Bulletin de la Stanstique Generale de la France.11 The year taken as a base was 1913 and the figures were weighted, for the agricultural index, according to the relative values of the several crops, and for the industrial index, according to the relative number of workers engaged in the several industries in each of the countries in the base year. M. Dessirier gives two sets of figures, the one covering the actual production and the other adjusted to meet changes in population.12 The latter only will be reproduced at this point as it is alone significant for the purpose in hand. This index shows production on the basis of a constant population or, alternatively, production per capita of the total population. Post-war figures take into account territorial changes. For purposes of convenient comparison, only the data for Germany, France, England, Belgium, Italy, West Europe, and the United States13 are here given, and these merely for the years 1920-1927. This period covers the inflation years in Germany and the four years following stabilization of the currency. A judgment on the effects of inflation in the sphere of domestic production is afforded through the contrast between Germany and those countries where currency depreciation was mild or non-existent in the years under review.
§ THE INDEX OF AGRICULTURAL OUTPUT
The figures on agricultural production are given in Table XXVII.
TABLE XXVII
INDEX OF PHYSICAL VOLUME OF PRODUCTION OF AGRICULTURAL PRODUCTS:
1920-1927
(Per capita of the total population. 1913 = 100)14
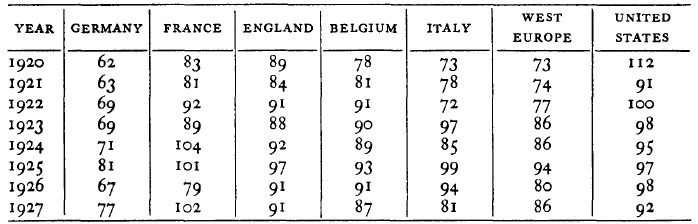
So far as trust is to be reposed in the figurest 15the table shows that German agriculture has yielded persistently lower returns relative to the situation in 1913 than that of any other of the countries for which statistics are here presented. But this is clearly due to the effects of the war rather than to those of inflation. Except for the bad season of 1926 (due to weather conditions and reflected in the statistics of all the European countries), improvement in Germany since 1919 has been steady and was about as great throughout the inflation years as during the years of stabilization. The fact is that the German soil, which is in general of rather poor quality and requires constant fertilization if yields are to be maintained, deteriorated to a greater degree during the war than did that of any other of the countries engaged. The neglect which it suffered was inevitable. The pressure for food supplies led to as intensive cultivation as was in the circumstances possible while no adequate replenishment of the soil elements was made owing, in part, to the fact that some important fertilizers were simply not then to be had on any terms. The restoration to pre-war productivity is a matter of many years. Agriculture was further ineffective in the early post-war years because of a shortage of draught animals and the sequestration of farm equipment by the victors. The low status of the German per capita production since 1920, relative to that of 1913, may also be due in some measure to superior productivity in the separated territories as compared with the average of the lands within the present confines of the Reich, and to influx of population from the separated territories.
So far as inflation of the currency is concerned, there is every reason to believe that it stimulated rather than depressed agricultural yields. The wiping out of the burden of mortgages which attended the decline in the value of the mark was a boon to the farmer and the price structure during the period of monetary depreciation was not unfavorable to him. The throes of currency collapse in late 1923, which affected industrial production considerably, took place within too short a period to have any influence on agricultural output. The crops had already been planted and their yield was independent of the movement of prices. The farmers, moreover, were in a strategic position both then and in earlier years. Producing, for the most part, the most essential products, consumption of which could not be interrupted except at the cost of life itself, they were able to provide for their own needs and to protect themselves against exploitation even in the face of semi-confiscatory governmental action. The great difficulties of the German farmer began only after the mark had been stabilized and they had nothing to do with money, qua money. In the agricultural branch of production the national economy suffered no losses which can be laid at the door of abuse of the currency.
§ THE INDEX OF INDUSTRIAL OUTPUT
Turning now to industrial production, the situation was as appears in Table XXVIII.
TABLE XXVIII
INDEX OF PHYSICAL VOLUME OF INDUSTRIAL PRODUCTION: 1920—192716
(Per capita of the total population. 1913 = 100)
This index, for most countries, is perhaps not as authentic as is that of agricultural output. In the case of Germany it is composed of the separate indices for mining (coal, lignite, iron ore, potash), metallurgy (pig iron and steel), mechanical industries (according to the consumption of steel), textile industries (according to the consumption of cotton and of wool), and building (for 1926 and 1927 only). This is a fair selection of basic industries but is not comprehensive enough to give assurance of its precision as a criterion of total industrial output. There is, however, no reason to doubt its representative character, and whether or not it gives a true picture of total industrial activity in the several countries relative to the 1913 situation in each, or relative to one another at any given date, it should reflect with some accuracy the changes from year to year. It more probably does so by reason of the shortness of the period covered since, in the eight years of its duration, no very sweeping alteration in the production and use of the index materials in their relation to total industrial activity did, in fact, take place.
§ CONTRAST BETWEEN THE SITUATION IN GERMANY IN I92I AND I922 AND IN THE OUTSIDE WORLD
The most striking feature of Table XXVIII is the contrast between the movement of the German index in the inflation years and those of all the other countries at the same time. In every other listed country production fell off very materially in 192117 and in most cases had not fully recovered by the end of 1922. Germany not only did not share in the general slump in 1921 but raised its production by 23% in that year and by an additional 12% in 1922. Since Germany, and one or two other countries with depreciating currencies,18 were alone unaffected adversely by the deflation crisis which ran round the world after the collapse of gold prices in mid-1920, the presumption is certainly in favor of conceding to depreciation the credit for the sustention and increase of industrial activity in the Reich at this period. There is no reason to believe that, had the German price movement paralleled the downward trend in other countries, production in Germany would not have been subject to the decline which took place in the outside world. In all the other countries for which statistics are above given the fall in prices, regardless of the nature of their currency, was sharp. In Germany prices fell slightly in the latter part of 1920 and in the spring of 1921 but, by May of the latter year, the upward movement of prices was resumed and industrial activity rose coincidently. Not only was production stimulated by increasing domestic demand (measured in monetary terms) but the low exchange value of the mark relative to its internal purchasing power gave Germany a large share of such international business as was to be obtained. That it was the fall in the value of the mark which enabled Germany to escape the depression which at this time afflicted practically the whole outside world is further evidenced by the facts that in France and Italy, where post-war deflation was moderate, the decline in 1921 production was slight (12% and 11% respectively) as compared with that in countries like England and the United States (31% and 25% respectively) where deflation was severe, and that, in 1922, coincidently with a renewed rise in prices in the former countries, production advanced beyond the 1920 level, whereas, in England and the United States, where deflation had been as definitive as it was severe, production still remained below the 1920 standard.19 Further than this, the index for 1926 production in France, the highest up to that time ever attained in that country, applies to the year of greatest depreciation of the currency, and the same is true of Italy in 1925 and 1926.
§ STABILIZATION CRISES IN GERMANY
Germany suffered from business depression in 1924,20 after currency stabilization had been effected, but this was slight as compared with that which occurred in England and the United States in 1921, or even with that in France and Italy. The latter countries went through the experience twice, once in 1921, when a measure of deflation occurred, and again in 1927, after their currencies had been put on a de facto gold basis.21 It would thus seem that Germany accomplished the actual process of transition from the war to a stable post-war monetary structure at a lower real cost in actual production than did any of the other countries here considered. The reason for this is doubtless that there was at no time in Germany any substantial deflation and no expectation of continuously falling prices. It is the prospective appreciation of a continuing unit of account which is most crippling to business. The transition to the stable-value rentenmark in Germany was a shift to an entirely new monetary unit and, far from involving any fall in prices in the old paper mark, was accompanied by a rapid increase in such prices. Paper marks continued to circulate for more than a year alongside of the rentenmark and were for a considerable time the principal of the two media of exchange, though they were no longer the unit of account. After November 20, 1923, they were exchangeable into the new currency at a trillion to one but between the fourteenth of November, the day before the introduction of the rentenmark, and the twentieth, only six days later, when the official rate of conversion was established, the exchange value of the old mark against the new currency fell from 300 billion to one trillion. From the twelfth to the fourteenth of November it had already fallen from 150 to 300 billion. In the final week of a free value for the old paper mark, during the period when the new currency was in process of introduction, the old unit thus lost five-sixths of the very exiguous value it had possessed at the beginning of the week in question. The transition to the stable standard therefore involved an immense access of inflation rather than, as in some countries, a severe lowering of prices. Business contracts made only a week before stabilization (or even within that week), which called for the payment at any later date of a fixed amount of paper marks, could be fulfilled at a very low real cost.22 There were, in consequence, no such difficulties to business men (who are predominantly debtors) as are inherent in the appreciation of a monetary standard which continues to be legal tender and in which all accounts are expressed.23 After November 20, 1923, German business had to get along without any inflation stimulant but it was not subjected to the burden of contracts payable in a more valuable money than that current at the time the contracts were made. There were difficulties in adjustment to the new monetary standard but they were not exacerbated by those twin evils of deflation, the increase .in the weight of debts, and the difficulty of adjusting comparatively fixed costs to steadily declining prices.
The difficulties actually incurred appeared in two separate depressions. The first ran from the introduction of the rentenmark, November 15, 1923, to March 1924, a period of uncertainty, doubt, and hesitation due to the shift to an entirely new monetary unit, to apprehension as to the permanent nature of the currency reform, and to the rigid control of credit necessary to ensure its success.24 This depression, though sharp, was short; the immediate transition was achieved at a relatively slight cost in national productivity. A second, more lasting, depression broke forth at the end of 1925 and carried through most of 1926. Whether or not this depression is to be regarded as a phase of the process of currency stabilization, or merely as one of the downs in the vicissitudes of business under any monetary standard, is an open question. The 1926 depression was apparently due to credit difficulties and these in turn were occasioned by the failure of domestic saving to recuperate other than haltingly from the terrific shock to which it had been subjected in the inflation years. One is perhaps justified, therefore, in attributing this second depression to the aftermath of currency depreciation.
§ BALANCE OF GAINS AND LOSSES IN DOMESTIC PRODUCTION
Disregarding for the time being the year 1923, which was dominated by the dislocation of industry attendant upon the events in the Ruhr as well as by the phenomena of extreme inflation, and going back to 1922, a year of high industrial activity, for a criterion of what the Germany of 1924 might have been expected to accomplish if it had not been in the throes of the birth of the new monetary system, we find that actual industrial production in 1924 was about 10% below par. This loss may properly be traced and assigned to the abuse of the currency in the previous years. Similarly, taking 1925, a good year, as a criterion of what might have been expected in 1926 if the German economy had not been plagued by the legacies of inflation, industrial production may be computed to have been adversely affected in the latter year by from 4% to 5%.25 Both of these estimates may seem somewhat small in view of the general upward trend in production which makes one year’s output too low a standard for the next. But since industry was still depressed in 1924 by non-monetary evils attendant on the Ruhr occupation, and since the depression in 1926 is probably not, in full measure, attributable to the prior abuse of the currency, the percentages given would seem not to understate the degree of industrial slump really due to adjustment to a stable currency and so to be attributed to the monetary disturbances to which that adjustment was an inevitable sequel.
These losses are small compared with the gains assignable to inflation in the upward swing of German production in 1921 and 1922. It has already been pointed out that the war left the productive equipment of Germany in a condition probably worse than that of any other country engaged26 and that the situation was aggravated by the delivery, in accordance with the armistice agreement, of a large amount of the best railroad rolling stock, of machines, stationary engines, tools and implements of all sorts. On the human side the loss in man power in the war and the decline in efficiency arising from a long period of undernourishment of the civilian population was equally great. The relatively low index of production in 1920, 61 on a base of 100 in 1913, was clearly due to these factors rather than to such depreciation of the currency as occurred in that year. Production was bound to be low whatever the monetary situation might be. There is no reason, indeed, to believe that inflation was not as effective in speeding up production in 1920 as it seems to have been in 1921 and 1922. Whether or not this is so, the impact of inflation on German domestic production, aside from 1923, seems, on the basis of the statistics so far examined, to have been beneficial rather than the reverse. So far as 1923 is concerned the falling off in German output was unquestionably due in large measure to the occupation of the Ruhr. It is quite possible that, though the production of the Ruhr district and of unoccupied Germany would have declined in any case, it fell farther because of the uncertainties attendant upon chaotic currency conditions, but it is arguable, on the other hand, that manipulation of the currency was the only thing which kept the Ruhr industries going at all.27 Evidence later adduced will go to show that, even in 1923, inflation was not a retarding influence except for a very short period.
The conclusions expressed in the preceding paragraphs are tentative only. Formed on the basis of an index of general productivity which is subject to a wide margin of error they should be checked by reference to alternative indices. To some such indices attention will now be directed.
§ PRODUCTION OF BASIC MATERIALS
In the general index of industrial production the output of coal, iron ore, pig iron, and steel plays an important part. A substantial measure of correlation between the figures for these basic materials and the general index is, therefore, to be expected. Since however the statistics in the mining and metallurgical industries are more accurate than for other branches of production it may be worth while to present them separately. Table XXIX gives the output, and index numbers of production, of these four materials in the inflation and in the two post-inflation years, and contrasts it with the average of the five pre-war years. The index of general industrial production has been added for comparative purposes.
TABLE XXIX
PRODUCTION OF COAL AND LIGNITE, IRON ORE, PIG IRON AND FERRO-ALLOYS, AND STEEL IN GERMANY;28 AVERAGE OF 1909-1913, ANNUALLY 1920-1925
(Absolute figures in thousands of metric tons)
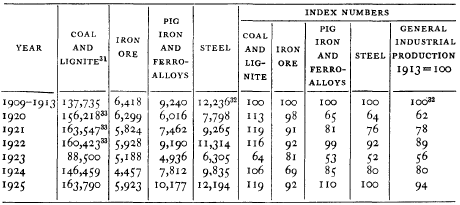
It will be noted that from the end of the war to 1923 there was a fairly steady all round increase (except in the case of iron ore where the output remained substantially stable), and that, in all cases, 1922 production compares well with that of the pre-bellum production. The 1923 output of these materials was affected by the invasion of the Ruhr far more adversely than German production in general, seriously as the whole German economy was hit by that event. The occupied districts produce approximately 85% of the German pit coal and 75% of the total output of coal and lignite, between 75% and 80% of the production of pig iron, and about 85% of that of raw steel. The decline in the Reich production of these basic materials in 1923 is therefore almost solely attributable to the occupation. Inflation played a minor, if any, role in the matter.
§ PER CAPITA PRODUCTIVITY IN SPECIFIC INDUSTRIES
So far, the figures given have been of output in general or of output in those branches of production which may be regarded as typical of industry as a whole. Other types of industry for which comparable figures are available do not in themselves provide good indices of general productivity since they may be advancing or declining relative to total production. Thus, while statistics for cotton, artificial silk, and other similar products are available, they will not here be introduced. The cotton industry, since the war, has almost everywhere shown a tendency toward stagnation in districts where it has been long established. The artificial silk industry, on the other hand, is growing much more rapidly than production as a whole. But, though total production in any branch of industry which does not produce the raw material for a wide variety of manufactures is, when taken alone, of no value as an index of production in general, something can be learned from the output per worker per hour. The only data of this sort, relative to manufactured goods, that have come to light are provided in scattered investigations made by the Frankfurter Zeitung. The results are too fragmentary to furnish a reliable index of output of finished goods but, with relatively few exceptions, they show an upward trend in per capita per hour output in a variety of industries and a performance, in the later inflation years (figures for 1923 not available), considerably better than in the pre-war period.29 Hours of labor were reduced in many industries in the postwar period and this tended, on the whole, to lower total production, a fact which should be kept in mind when comparing 1913 figures of other than hourly output with those of the period 1920-1923. The general impression obtained from a study of the Frankfurter Zeitung’s figures on finished goods industries is that, in these lines, production was at a higher level relative to the pre-war period than was the case in the basic industries and that it advanced more rapidly during the regime of inflated currency.
Thus, though the index of general production is largely made up from total output in the basic industries and does not show production per worker30 and, though the number of workers engaged in some of the basic industries rose relatively to production,31 it would seem fair to assume that the increase in man-hour output in the finishing industries counteracted any tendency toward lower performance in the raw material group, and that total production per head continued, without doubt, to rise till 1923. The bulk of the basic products produced were consumed at home.32Total production must therefore have moved in some correspondence with the output of industrial raw materials. If, in the raw material industries in any year, the number of workers engaged was larger relatively to total output (1913 being taken as a standard) than the ratio between the production of raw materials in the year in question and the production in 1913, the finishing industries must have been as much above the average current man-hour productivity as the raw material industries were below it.
2. INDIRECT ESTIMATES OF PRODUCTION. TRANSPORT
§ FREIGHT TONNAGE AS AN INDEX OF PRODUCTION
Perhaps the best indirect criterion of productivity is furnished by an index of the physical volume of freight transported. The chief defect in an index of this sort is the fact that an alteration in the relative tonnage of a few commodities of small value per unit of weight, such as coal, iron ore, stone, clays and the like, may make a difference in the index quite disproportionate to the real significance of the change so far as total value productivity is concerned. The transfer from Germany to France and to Poland of territory where heavy industry was prominent led to a great diminution in the weight of freight carried in Germany. The difficulty here involved is in part obviated by taking for the base year, 1913, only the present German territory. But, even so, complications arise from the fact that the traffic between two former German districts which are now politically segregated, one in Germany and one outside, would not be likely to take place on the same proportionate scale after as before the separation. This being so, the composition of German freight traffic might easily change from a greater weight of less valuable goods to a lesser weight of more valuable goods without any alteration in the total value output of German industry or even of the value of transported goods. Weighting according to value, however, being impracticable in the chaotic price situation during the period under review, it seemed best to take as the index of total freight transported, and so of production, a simple average of the indices (on a 1913 base) of the volume of traffic in each of the separate commodities listed in the German State Railroad’s freight-classification. The influence of any alteration in the volume of freight in a heavy commodity, such as coal, which might materially affect the actual weight of freight moved and so exaggerate the change in productivity, is thus minimized and is brought into reasonable conformity with the real change in the output of economic values. While the index of transportation presented in the ensuing pages is an index of weights the method of construction is therefore such that it should offer a fair criterion of the total relative value of the transported goods.
following figures of production in the Dortmund mines are probably typical of coal mining in general :
DORTMUND MINES. INDEX OF OUTPUT PER MAN-HOUR
| Date | 1919 | 1920 | 1921 | 1922 |
| Jan. | 89.2 | 91.8 | 82.4 | 85.5 |
| Feb. | 88.1 | 94.0 | 84.2 | 86.6 |
| Mar. | 90.2 | 844 | 84.0 | 87.5 |
| April | 76.6 | 83.6 | 85.3 | 86.8 |
| May | 91.7 | 85.8 | 86.1 | 85.8 |
| June | 94.7 | 86.1 | 87.1 | 86.8 |
| July | 96.4 | 83.6 | 85.4 | 85.8 |
| Aug. | 95.9 | 82.9 | 85.1 | 85.8 |
| Sept. | 94.6 | 82.9 | 85.1 | 84.1 |
| Oct. | 94.1 | 82.2 | 84.7 | 83.6 |
| Nov. | 995 | 82.9 | 84.4 | 83.0 |
| Dec. | 89.7 | 82.7 | 84.8 | — |
Hours worked were 8 ½ in 1913, 8 for the first three months of 1919, 7½ in April 1919, and 7 thereafter, so that the output per shift and per year, for a given number of workers, was considerably less than these figures would indicate. Enquête sur la production, Bureau International du Travail, Rapport General, Vol. II, Berger-Levrault, Paris, 1923.
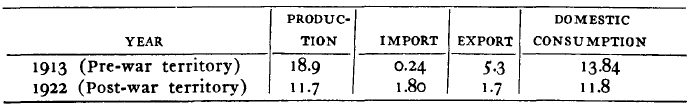
The volume of freight carried, even so computed, and its value, too, may of course have varied independently of the volume and value of production as a whole. An increase in the territorial specialization of industry, for instance, would augment the volume of transport per unit of output and, on the other hand, developments might occur which would diminish freight transport relative to production. The troubles encountered when a shortage of fuel developed in Germany,33 for instance, were in part solved by the expansion of lignite production and the conversion of this lignite into electric power at the mines. This process considerably reduced the volume of freight transport which would have been essential to an equal production of finished goods had coal been used in the old way. Changes of this sort cannot, however, be computed with any precision, and the index of transport must be taken as representative of total production with whatever reservations on this or other accounts may be necessary.
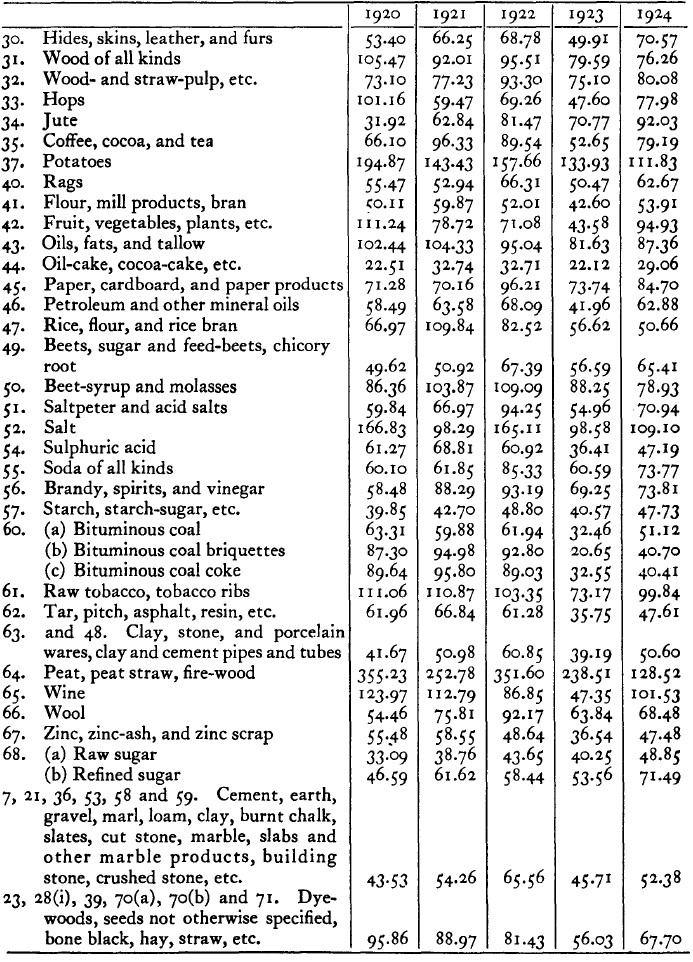
TABLE XXX
INDEX OF COMBINED RAILROAD TRAFFIC AND TRAFFIC ON INLAND WATERWAYS IN GERMANY; 1920-192434
(1913 = 100)
§ RAILROAD AND WATERWAYS TRAFFIC
Table XXX, above, gives index numbers, for the years 1920 to 1924 (base 1913 = 100), of the combined traffic on railroads and inland waterways for the 79 different categories of freight which can be separately distinguished, throughout the period, in the statistics covering these two methods of transportation. The 79 categories include all the freight transported either by railroad or inland waterways.
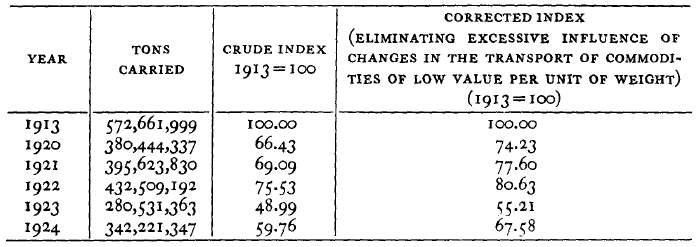
The average of the indices, the general index number at the bottom of the table, is probably fairly representative of the total production measured by value. A well recognized effect on the composition of German industry of the losses of territory in Alsace-Lorraine, Posen, West Prussia, and Upper Silesia is the transition to more highly wrought products, so that the gross weight of freight carried, if taken without correction, would provide a much less satisfactory index of production. There can be little doubt that the corrected index here offered gives a truer picture of the actual value of the output of German industry than do the relative total weights of goods carried in the pre- and post-war years.35The difference between the crude and corrected indices for traffic in general, one representing total traffic by gross weight, and the other traffic according to the method above described, is shown in Table XXXI.
TABLE XXXI
COMPARATIVE INDICES OF TRAFFIC ON GERMAN RAILROADS AND INLAND WATERWAYS
1913, 1920-1924
(Present territory)
§ COMPARISON OF TRANSPORT AND GENERAL PRODUCTION INDICES
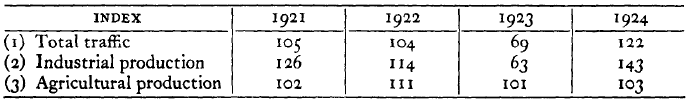
Let now the index of production, as evidenced by the corrected index of transport of commodities, be compared with the directly calculated indices of agricultural and industrial output. See Table XXXII.
TABLE XXXII
INDEX NUMBER OF COMBINED TRAFFIC ON GERMAN RAILROADS AND INLAND WATERWAYS COMPARED WITH INDEX NUMBERS OF PRODUCTION;36 1920-1924
1913 = 10037
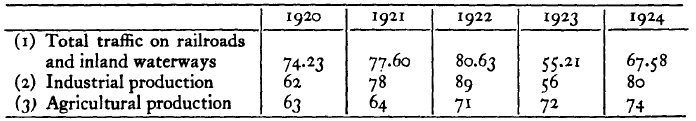
The three indices show a by no means bad correspondence with one another. Industrial production and traffic are in close relationship in 1921 and 1923 and the traffic index is intermediate between those of industrial and agricultural production in 1921 and 1922.38 In 1920, however, the traffic index is considerably higher and, in 1924, considerably lower than either of the other two. The deviations in 1920 and 1924 may be due either to defects in the indices or to actual shifts between the volume of production and the volume of freight carried. On the whole it is probable that the transport index is more reliable in 1920 than are the direct indices of production39 while, in 1924, it seems likely that total production revived rather more rapidly than did the volume of freight carried.
Taking the year 1920 as the first after 1913 in which war phenomena were not a dominating factor, and assuming that each of the three indices represents conditions in which, at that date, some considerable degree of adjustment to the new situation had been effected, it will be worth while to compare the relative movements in, rather than the status of, the several indices through the years 1920-1924. Such movements are shown in Table XXXIII which gives link relatives of the three indices here under review.40 It will be noted that the correlation of movement in the three indices is close and that the index of the movement of traffic conforms with theoretical expectation in being intermediate between that of the two direct indices of production except in 1922 when all three indices show much the same relationship to the 1921 figures. The absolute agricultural production index grew steadily, if slowly, from 1921 to 1924 and its growth presumably affected in proportionate degree the index of transport. If all the indices here employed are to qualify as really good criteria of total production, the fluctuations in the index of transport ought, in consequence, to follow, with less marked variations, the year to year changes in the index of industrial output. A glance at Table XXXIII will show that this is in fact the case and it can therefore be assumed with some degree of assurance that the figures arrived at give a reasonably good indication of the actual value of German production in the inflation years. The index of transport corroborates the directly derived figures on production about as fully as could well be expected.
TABLE XXXIII
LINK RELATIVES OF THE INDICES OF COMBINED TRAFFIC ON RAILROADS AND WATERWAYS, OF INDUSTRIAL, AND OF AGRICULTURAL PRODUCTION
3. INDIRECT ESTIMATES OF PRODUCTION. CONSUMPTION
§ STATISTICS ON CONSUMPTION INADEQUATE
A comprehensive index of national consumption, with; allowances made for foreign commercial and financial transactions and for the growth or decline in capital equipment, would be as good a criterion of production as direct statistics on the output of goods.41 Consumption of currently produced goods, including capital equipment, must be equal to production plus import minus export. Though, in the inflation years, the Germans gave a large amount of commodity exports per unit of imports, the decline in consumption relative to production42 (both being measured in physical rather than value units) which this would normally necessitate was more than compensated by the receipts from the sales of currency never redeemed. Statistics on general consumption ought therefore to check fairly closely with those on production, 1913 being taken as a base in both cases.
Most of the available statistics on consumption, however, apply to foodstuffs. A large part of the consumption of foodstuffs ordinarily takes place within the confines of the middle-income class. But this was the very class which was brought to ruin by the depreciation of the currency. It is not to be expected that the prosperous group which was benefiting at the expense of the middle-income class would expand its consumption of foodstuffs in anything like the same measure as the latter class was forced to cut it down. The type of consumption, rather than its total volume, was entirely changed by the phenomena of inflation and this change is not reflected in the statistics available. There was a showy but probably not absolutely very large expenditure on luxuries by the “profiteers.” A considerable share of this expenditure was made outside of Germany and the foreign journals of the day are full of references to the objectionable display, by certain classes of Germans, of their new-found wealth. German newspapers mark, the same tendency at home though the total import of luxuries greatly declined. Consumption of domestically produced luxuries is very inadequately reported.
Of much greater absolute importance than this luxury expenditure, however, were the outlays, on capital account, of funds which would ordinarily have accrued to the population at large and have been spent, at least in part, on consumable goods. The volume of new industrial building, of renewal, repair, and expansion of equipment in manufacturing, transportation, agriculture, and mercantile life was large, especially when currency depreciation became so rapid as to make outlays on capital almost the sole means of preserving the substance of profits. These investments were for the most part made directly from undistributed profits. Under stable monetary conditions the funds thus employed would have first gone to private individuals who would have exercised their volition as to whether they would invest them or use them for immediate consumption and would in many, and perhaps in the majority of cases, have decided for the latter.
The expenditures for improvements in productive equipment43 of course lowered the ratio of immediate final consumption to total production. Further than this, in the relationship between production and consumption, it should not be forgotten that domestic consumption was diminished relatively to output by the payment of reparations both in cash and in kind. While cash reparations were of greater import in wrecking the exchange value of the mark, the payments in kind involved a larger sum of values and were consequently more significant in reducing home consumption below the level of production. Large deliveries of goods were required, in addition, to cover the costs of the armies of occupation and the restitution of Allied nationals’ property seized during the war. In the three years, 1920 to the end of 1922, goods to a total value of about 9 billion gold marks were delivered to the Allies out of current production44 in addition to total cash payments of approximately 2 billion. Such deliveries amount to more than 25% of the total German monetary income in 191345 or, if allowance be made for the higher gold price level in post-war times, to some 17% of the total real income in 1913. They were spread over a period of four years and therefore average yearly between 4% and 5% of the 1913 income. Insofar, however, as the total German output was less in the period of inflation than in 1913, these deliveries to the victors would represent a larger share of the post-war production and would correspondingly lower the relation of domestic consumption to output. Quite apart then from the question of the relative division of output between producers’ and consumers’ goods, indices of per capita consumption of commodities, other than raw materials of industry, might therefore reasonably be expected to run some 6% or 7% below indices of production.
§ INDICES OF CONSUMPTION
Table XXXIV gives indices of per capita consumption of certain important foodstuffs (the only available data which seemed relevant to the purpose in hand) as compared with indices of production.
TABLE XXXIV
INDICES OF PER CAPITA CONSUMPTION OF CERTAIN FOOD PRODUCTS COMPARED WITH INDICES OF PRODUCTION; 1920/21-1924/25
(1913/1914 = 100)
It should be noted that, on a diminution of income, the consumption of basic foodstuffs will not be curtailed in anything like the same measure as consumption in general. The use of non-essential foods and drinks, for instance, fell off to a much greater degree than did that of the commodities shown above. If the figures here given therefore seem low relative to the indices of production this is probably due to the defects of an index of the consumption of foodstuffs as a criterion of general output under the circumstances to which it here applies. In view of what has already been said as to the general relation between production and consumption in Germany in the period under review, and as to the peculiar conditions affecting the consumption of foodstuffs, it may perhaps be asserted that the indices of consumption and of production corroborate one another reasonably well. This assertion is in some degree supported by such fragmentary evidence as is at hand on the output of producers’ goods.
§ OUTPUT OF PRODUCERS’ GOODS
The share of total production which took the form of producers’ rather than consumers’ goods, and its relation to the pre-war division of total output between these two groups, is far from being an open book but it seems probable that a somewhat larger proportion of total output went into capital goods in the inflation years than was the case before the war. Consumption of consumers’ goods was necessarily reduced pro tanto. Saving, in the old manner, was destroyed by the depreciation of the currency but this was replaced by the ardor for investing in durable commodities which possessed the mind of every holder of any surplus in the monetary form. It is by no means certain that there was not more actual saving than there would have been under a stable monetary regime but it was done by direct investment rather than through financial institutions. The bulk of the population no doubt spent on immediate consumption a larger proportion of their incomes than in former times but a much smaller share of the total national income came into their hands. Final consumption relative to output was thus considerably reduced. It will be worth while to consider some forms of capital accumulation for which usable figures are available.
( 1 ) The Mercantile Marine.
The mercantile marine, which had been almost completely confiscated by the Allies, was by the end of 1923 more than half rebuilt. Activity in this line was stimulated by the governmental policy of reimbursement of the shipowners for their losses to the Allies, on the condition that the funds so received go into new construction. In this way the administration was imposing upon the people a forced saving since the money paid to the shipowners was taken from consumers through the inflation process in precisely the same manner as would have occurred under orderly arrangements in public finance had taxes been levied to the required amount. New construction in German yards for the years 1921-1923 as compared with the average of 1909-1913 was as follows:
SHIPBUILDING IN GERMAN YARDS
TONNAGE OF MERCHANT VESSELS LAUNCHED
Average of 1909-1913; annually, 1921-1923)
| YEAR | THOUSAND TONS46 |
| Average 1909-1913 1921 1922 1923 |
272.8 509.1 525.8 345.1 |
The high output of this type of capital good during inflation is obvious. Even in the disastrous year 1923 the tonnage produced was considerably above that of the annual average of the quinquennium immediately preceding the war.
(2) Railroad Equipment.
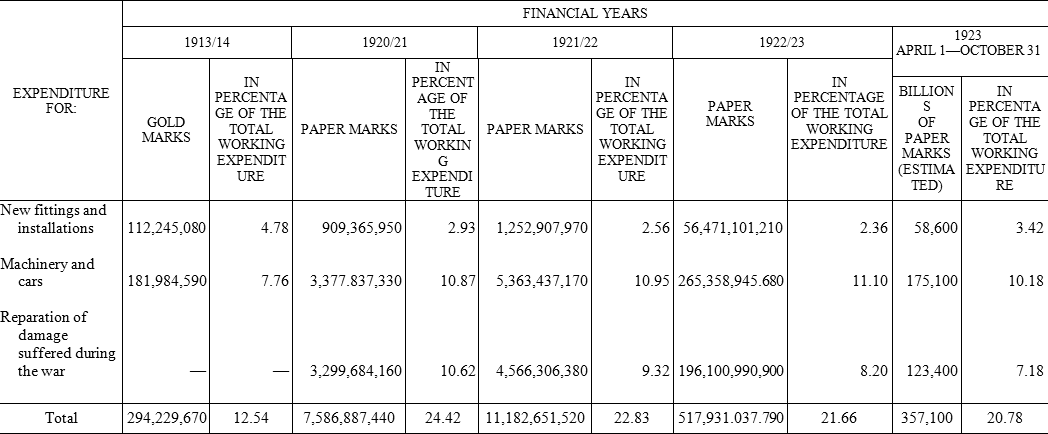
As with the mercantile marine so with the railroads reconstruction was vigorously pushed in the inflation years. Here, as elsewhere, monetary statistics are a very uncertain guide but in Table XXXV expenditures for new installations out of the ordinary railroad budget (that is without emission of new capital) are expressed not only as absolute sums but also as a percentage of total expenditures and so, to some degree, avoid the difficulty inherent in the use of data in monetary form.
From one-fifth to one-fourth of total working expenditures in the inflation years were outlays for new installations whereas in 1913-1914 only one-eighth of the total was so spent. On the other hand, expenditures made out of the proceeds of new capital issues were much less in the later years than in 1913-1914: inflation was leading to the making of the greater share of improvements out of current income. Taking the two items together the total expenditures (in terms of real purchasing power) were undoubtedly larger than in pre-war years.47
The conclusion that the capital equipment of the railroads was being more than ordinarily extended and improved is confirmed by statistics on the number of locomotives put into service and by those on rolling stock in general. Of the locomotives in operation in Germany in 1925 there were put into service in the designated years the following numbers :
NUMBER OF LOCOMOTIVES IN USE IN 1925 PUT INTO SERVICE IN THE YEARS 1910—192548
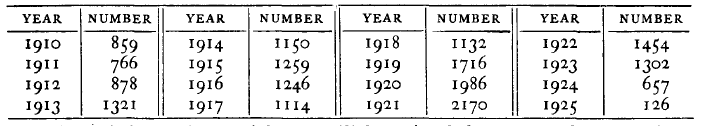
Practically all locomotives put into service later than 1913 were still in operation in 1925. The figures here given therefore closely represent the number of new locomotives acquired by the railroads in the years after 1913 to which they refer. The additions in the inflation years are markedly greater than at any other period and, to the extent of the difference, capital equipment was more than ordinarily extended. Furthermore, the quantity of locomotives under repair fell from 43.2% of all locomotives on April 1, 1920 to 27.2% on January 1, 1924, and the number of freight cars from 100,010 on August 1, 1920, to 45,400 on January 1, 1924.49 The quality of the existing equipment was thus being constantly improved in the period under review.
TABLE XXXV
EXPENDITURES FOR PROFIT-YIELDING INSTALLATIONS CONTAINED IN THE ORDINARY BUDGET OF THE GERMAN STATE RAILWAY (AMORTIZATION) AND THEIR SHARE IN THE TOTAL WORKING EXPENSES
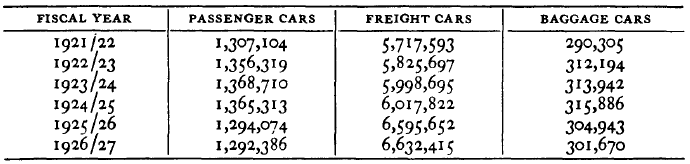
Except for locomotives no figures on the additions to rolling stock in 1920 are available. The gap left by the Allies’ sequestration of railroad property was, however, rapidly mended in that year and the increase in equipment was undoubtedly large. By 1921 the rolling stock had been brought fairly well up to the volume requisite for the existing traffic though there were some additions in the next two years. Table XXXVI shows the weight in tons of certain classes of rolling stock from 1921 to 1926.
TABLE XXXVI
WEIGHT (IN TONS) OF CERTAIN CLASSES OF ROLLING STOCK ON GERMAN RAILROADS; 1921-1926
Source of data: Statistik der im Betriebe befindlichen Eisenbahnen Deutschlands, Reichsverkehrsministerium, Vols. 44, 47, Berlin, 1925, 1927, passim.
The fact that the total weight of passenger and baggage cars in operation showed a declining tendency after the currency was stabilized would seem to indicate that these types of rolling stock had been somewhat overbuilt during the inflation years. Though the total weight of freight cars markedly increased in 1925 and 1926, this was due to increased need in those years rather than to any shortage in 1922 and 1923 relative to the freight then being carried. By 1923 the deficiency, which was acute immediately after the war, had apparently been made up. On the whole, in spite of inadequate statistics, there can be little doubt that the restoration of the railroads from the bad shape into which they had fallen during the war50 necessitated and called forth an unusually heavy outlay on improvements and extensions in the inflation years and inflation appears to have been a distinctly facilitating factor.
(3) Industrial Building.
The capital outlays on transportation were paralleled in other branches of industry though for this it is difficult to cite chapter and verse. The area of industrial constructions is said to have increased by 25% from 1920 to 1923.51 The vast amount of reconditioning carried out in these years is noted in foreign official reports52 and the German Under-Secretary of State in the Ministry of the Interior, Dr. Julius Hirsch, is quoted as follows: “Until the Ruhr conflict. . . . the income of Germany’s work showed a slow but fairly steady increase, whereas direct consumption, although it also was again growing, was growing somewhat more slowly,”53 the implication being that a larger share of production was going into capital expenditures.
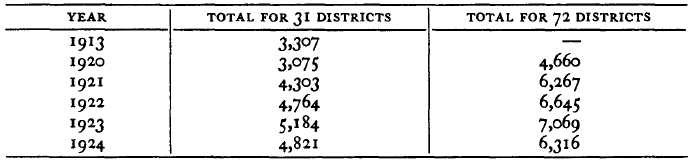
Industrial building statistics are meager. All that is available in the official statistics is the total number of new buildings put up within the year, with the number of dwellings stated separately. The difference between the two totals would no doubt consist largely of industrial and commercial building but the mere number of erections for business purposes is of no great significance without some indication of the size of the individual units. The data on non-dwelling constructions are, however, set forth in Table XXXVII for whatever value they may have.
The steady growth throughout the inflation period in the number of business buildings constructed, the substantial margin by which the figures for 1921, 1922, and 1923 overtop those of 1913, which was itself a very active business year, and the decline in activity with the coming of currency stabilization as shown by the figures for 1924, furnish at least some statistical verification for the assertion that in the years of currency depreciation a much larger than usual share of total output took the capital form.
(4) Industrial Equipment.
Evidence that investment in equipment other than buildings was active is also meager but goes to show that here too a relatively large share of total output was producers’ goods. The number of workmen employed in the construction of machinery, instruments and apparatus in 1913 and in 1920 to 1922 was, in thousands:54
TABLE XXXVII
CONSTRUCTION OF NEW BUILDINGS OTHER THAN DWELLINGS; 1913, 1920-192455
(Number of buildings)
| YEAR | 1913 | 1920 | 1921 | 1922 |
| Workers employed on Machinery, | ||||
| Instruments, and Apparatus | 1173 | 1420 | 1462 | 1654 |
These figures cover iron works, shipbuilding, and vehicle manufacture as well as the more strictly engineering trades. In the engineering industry proper the number of persons employed is estimated at five to six hundred thousand in 1913 and seven to seven hundred and fifty thousand in 1922.56 Since productivity per worker in these lines seems to have been at least as great as in 1913 the output in the inflation years was in all likelihood not less than in proportion to the number of workers engaged. It is significant that, after stabilization of the currency, the number of workers in these industries declined from 700 to 750 thousand in 1922 to about 550 thousand in 1924 and 1925.
(5) Agricultural Equipment.
Investment in agricultural machinery probably kept pace with that in industrial equipment, though the only evidence at hand is very inconclusive. Figures have been compiled showing the machine equipment of German farmers in 1924/25 in contrast with that of 1906/07. The increase during these years is remarkable and a sizable share of this increase must, it would seem, have occurred in the inflation period since equipment was neglected during the war. It cannot be alleged that the data provide any assurance on this point but they are given for what they may be worth. See Table XXXVIII.
TABLE XXXVIII
NUMBER OF MACHINES OWNED BY GERMAN FARMERS; 1906/07 AND 1924/25
POST-WAR TERRITORY (LESS SAAR BASIN)
| Type of Machinery | 1906/07 | 1924/25 |
| Power ploughs | 304 | 8,552 |
| Mowing machines | 307,454 | 1,023,381 |
| Machine hoers | 14,633 | 145,638 |
| Potato planting machines | 1,986 | 47,837 |
| Potato digging machines | 10,064 | 173,703 |
| Power threshers | 732,772 | 1,055,151 |
| Rough grinding mills | 25,588 | 319,670 |
| Cream separators | 293,795 | 1,415,699 |
Source of data: Wirtschaft und Statistik, 1927, p. 764.
(6) Activity in Industries Manufacturing Producers’ Goods.
It may be of interest to present the number of workers employed in various branches of production in order to note the relative growth of industries producing capital and consumers’ goods respectively. Table XXXIX shows the number of persons employed in the several industries for the years 1913, 1919, 1922, and 1923 and the percentage of workers in each of the industries in 1922 in relation to the situation in 1913. The year 1922 was chosen for comparison with 1913 as being most representative of the effects of inflation since production in 1923 was greatly influenced by non-monetary causes. The industries are ranked according to their relative status in 1922 as compared with the pre-war and pre-inflation period. It will be noted that all the industries which show a large relative growth are producers of capital goods.57 The building, and stone and earth, industries, it is true, bring up the rear but this was due to the falling off in the construction of dwellings rather than in industrial building. Dwelling construction was not checked by inflation, as such, but by rent limitation laws which rendered it impossible to build new houses to rent on a competitive basis with the old.
TABLE XXXIX
NUMBER OF WORKERS EMPLOYED IN VARIOUS INDUSTRIES; 1913,1919,1922,1923
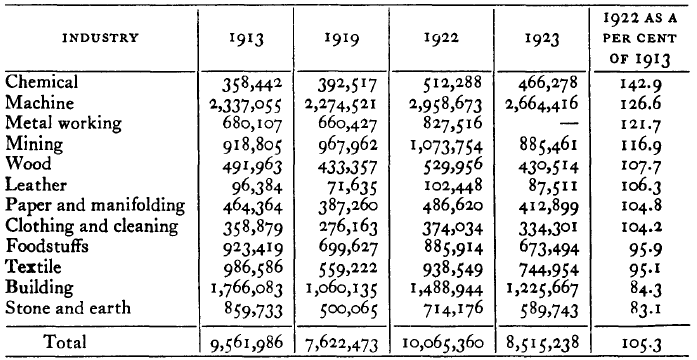
Source of data: Wirtschaft und Statistik, 1926, p. 171. The figures are derived from the annual reports of the Berufsgenossenschaften except for the metal-working industry where they come from the reports of the Gewerbeaufsichts-behörden.
With the single exception of 1923, a year in which all production was low, it is clear that in most branches of capital accumulation progress was comparatively rapid during all the years of currency depreciation. This does not mean that the country was prosperous, even if the great distress caused by inequity in the distribution rather than insufficiency in the total amount of income, be left out of account. Total production was much below the ante-bellum level and consumption was curtailed in a still greater degree. But the reasons for this are to be traced to the war rather than to the currency. Restoration of capital equipment used up during the period of hostilities was not checked by inflation but went on more rapidly than would have been likely to have occurred under a stable monetary standard. The accessions to capital, as always, were at the expense of current consumption, which would in any case necessarily have been low, and the relative growth of capital explains part of the discrepancy between production and immediate standards of living. The remainder of such discrepancy as exists was presumably due to exactions under the Treaty of Versailles.
4. INDIRECT ESTIMATES OF PRODUCTION. REAL WAGES
§ SPECIAL FACTORS AFFECTING WAGES IN GERMANY
The bulk of the total income of an industrial country like Germany takes the form of wages and even the stupendous shift in distribution which currency depreciation brought about did not alter this situation very profoundly. Real wages ought, therefore, to furnish still another check on the figures of production. The statistics on wages as a criterion of production are, however, open to the same objections as apply to the available figures on consumption. They show only the returns to the middle and lower classes, not those to the classes which benefited from inflation. For a given volume of production they also tended to be low relative to the pre-war situation in the degree to which capital was saved through unusually large direct investment of profits and to the extent that the burden of reparations payments fell on the worker. In addition to this, other government outlays, financed by inflation, were being met by a form of taxation which came out of wage and other incomes before, rather than after, those incomes were received, since, with every rise in prices attendant upon new issues of currency, a given payment in marks represented lower real wages. Taxes were thus levied at the source with a vengeance.58 On all these grounds real wages tended to be comparatively smaller than production, 1913 being taken as a standard in both cases. On the other hand, governmental control of prices, particularly rents, may have operated to raise real wages. It is indeed probable that the practical confiscation of the property of house owners enured almost wholly to the benefit of industrial entrepreneurs who offered propor-tionately lower money wages than they would otherwise have been forced to pay. So far, however, as the worker derived any advantage therefrom, his real wages, reckoned on the basis of cost of living (including rent), would on this account tend to be higher than current general productivity would warrant.59
Statistics of real wages, moreover, are appropriate indices of production only so far as the classes of the population to which they refer secured an unvarying proportion of the total national output. There is no probability of any strict constancy in this matter but it is probable that the proportionate share of unskilled laborers in the total income did not fall very greatly and that the aggregate income of the industrial population was not much below its pre-war percentage of production.
The best study of wages in Germany in the inflation period is that of the International Labor Office. Their estimate of aggregate real income of the German industrial population,60 relative to 1913-14, is as follows :61
INDEX OF AGGREGATE REAL INCOME OF GERMAN INDUSTRIAL POPULATION, 1920-1923 62
| YEAR | APPROXIMATE INDEX NUMBER (1913-1914 = 100) |
||
| Yearly average | 1920 | . . . . . . . . . . . . | 60-85 |
| ““ | 1921 | . . . . . . . . . . . . | 75-105 |
| ““ | 1922 | . . . . . . . . . . . . | 70-90 |
| Jan. to August | 1923 | . . . . . . . . . . . . | 58-76 |
| November | 1923 | . . . . . . . . . . . . | 36-47 |
These figures are expressly declared to be but very rough approximations from which conclusions should be drawn only with the greatest caution. But there is no doubt that the real income of the working class in Germany rose greatly in 1921 while it fell heavily in almost every other country, that the decline in 1922 was due to a smaller share in the total national income rather than to a falling off in the national output,63and that the low yield for 1923, especially in the first half, is in large measure due to the effects of the Ruhr invasion.
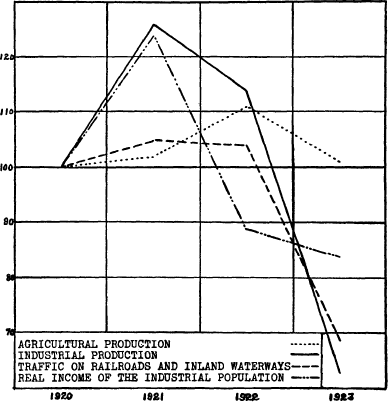
Except in 1922 there is a fairly good correlation between this index of the aggregate real income of the industrial population and the production indices presented earlier in this chapter. All the indices of production which have been examined do, in fact, square fairly well with one another. The most comprehensive are those of agricultural yields, of general industrial output, of transportation, and of aggregate income of the working classes. Chart XXXIV shows the relation between these four indices.64 The correspondence is sufficiently close to warrant the use of the general indices of production (agricultural and industrial) as fairly representative of the actual situation. All the indices are rough, of course, but corroboration of the general indices comes from the similar results obtained through the several methods of approach. It would therefore seem that the margin of error involved in the direct estimates of production is not unduly wide.
CHART XXXIV
LINK RELATIVES OF THE INDEX NUMBERS OF AGRICULTURAL PRODUCTION, INDUSTRIAL PRODUCTION, TRAFFIC ON RAILROADS AND INLAND WATERWAYS, AND AGGREGATE REAL INCOME OF THE INDUSTRIAL POPULATION ; 1920-1923
§ CONCLUSIONS AS TO THE EFFECT OF INFLATION ON DOMESTIC PRODUCTION
Most authorities would readily concede that inflation in its early stages exercises a stimulating influence on business activity, and might increase production, but they would be loth to admit that this effect could be more than temporary. In the German case, however, there is little evidence up to the end of 1922 or, indeed, till late 1923, to show that the stimulus was losing its power. As contrasted with business activity production can, it is true, be increased by inflation only up to the point at which unemployment practically disappears. After this point is reached any further fluctuation in production, so far as it is affected by inflation, must, in the first instance, be downward. Opinion is unanimous that in the final weeks of inflation in Germany the depreciation of the currency was, to say the least, a deterrent to productive effort. The turning point came with the refusal of the employed classes to suffer further losses and with the demand for stable value payments in every type of transaction, that is, with the repudiation of the mark. The inability of entrepreneurs further to exploit the situation to their own advantage came quite suddenly. A fair index is furnished by monthly statistics on unemployment in the unoccupied part of the country. It was not until the first of September, only ten weeks before the introduction of the rentenmark, that the number of people entirely out of work began rapidly to increase, though partial unemployment had risen a month earlier. The degree of unemployment is indicated by the preceding Table XL, the figures of which, though referring only to trade unionists, nevertheless cover a large portion of the population and include all the principal industries.
TABLE XL
UNEMPLOYMENT AMONG TRADE UNION MEMBERS, BY MONTHS; 1922-192365
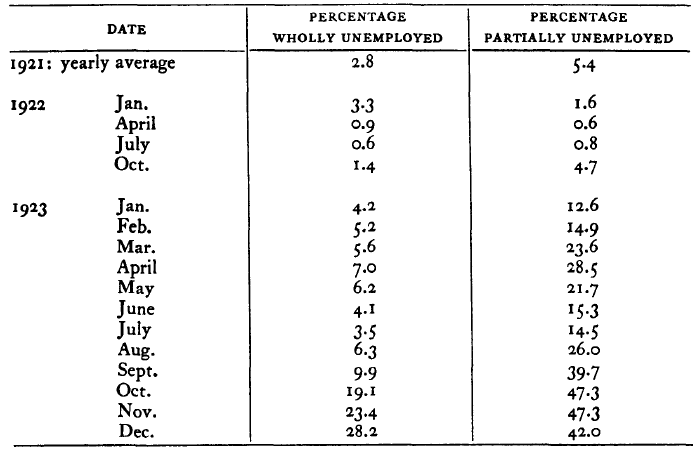
Since the increase in the numbers of unemployed had already begun in October 1922, it is probable that some part of the depression in the early months of 1923 was directly due to the dislocation issuing out of the immense acceleration in the rate of currency depreciation (which began in the fall of 1922 and was almost uninterrupted thereafter), rather than to the Ruhr invasion. But, though this may possibly be true, the recovery in the summer of 1923 does not offer any corroboration of such a view. Not until the final three months of the paper mark regime can a deleterious effect on industry be clearly traced to the collapse of the currency. Something between a quarter and a third of the decline in output in 1923 (estimated at 37% lower than 1922) should therefore be assigned to monetary disturbances with the probability running toward the lower rather than the higher figure.66 The fall in 1923 production which was due to inflation may thus be fairly put at about 10% of a normal year’s output at that time.
If the conclusion just reached as to the effect of inflation on production in the final year of life of the old mark is justified, it follows that, so far as the total of domestic production goes, the gains from the employment of inconvertible and depreciating currency more than outweighed the losses. Counting in both the two post-inflation crises, for which inflation can with some reason be held responsible, and the falling off in production in late 1923 attendant upon the dying throes of the old currency, the reduction in output can scarcely have exceeded the benefits which inflation seems to have brought in 1921 and 1922. The decline in production due to the stabilization crises in 1924 and 1926 has been set at 10% and 5%, respectively, of a normal year’s output at that time.67 The decline due to the phenomena of complete currency collapse in late 1923 has just been estimated at perhaps 10% of the output which might have been realized in that year had a stable monetary standard been in operation. A rough notion of the extent of all of these losses, measured in current gold values, may be obtained from the following computation :
ACTUAL AND POTENTIAL OUTPUT IN GERMANY IN 1923, 1924, AND 1926
(Millions of Gold Marks)
Total losses in domestic production traceable to inflation in the years when its influence was adverse, may thus be set, in round figures, at 11 billion gold marks. These losses are much more than offset by the presumable gains from inflation in the year 1921 alone. Estimating in the same manner as above, the industrial output of the German economy in that year was raised over that of 1920 by nearly 10 billion gold marks,68 whereas, if a gold standard had prevailed, a sharp drop, perhaps equal to the 25% fall in industrial production which occurred in the gold standard United States69 or the 31% of Great Britain, would have been almost certain. If a 25% fall had occurred, the net loss, as compared with the situation which in fact eventuated, would have amounted to about 19 billion gold marks. As for 1922, it has already been pointed out that it is most improbable that production in Germany, where industrial activity was at its maximum, would have been as great under stable monetary conditions as it actually proved to be under the stimulus of currency depreciation since this was a year of but slow recovery from the depression of 1921 in all countries where prices were kept on an even keel.70
So far as output is concerned there is therefore little support in actual statistics for the contention that the evils of inflation were other than evils of distribution. Domestic production seems on the whole to have been greater than would have been attained if the currency had been solidly based on gold. Taking the nation as a unit, the collapse of the currency was thus far from being an unmixed curse.
71 It is true that the ownership of this wealth might change from German to foreign hands owing to the pressure on its original possessors arising from the consequences of a depreciating currency. Such changes in ownership have been treated in Chapter xi.
72 Figures for 1919 do not include the then ceded territories but do include Upper Silesia.
73 The ceded parts of Upper Silesia are excluded.
74 From January to October, 1923, increases only have been included.
75 It is estimated, somewhat loosely perhaps, that the number of persons in earning occupations in 1922 was three millions higher than would have been the case had there been no war and no inflation, cf- Mythology of Reparations, Robert Crozier Long, London, Duckworth, 1928, p. 108. The estimate is not Long’s own but he does not give his source. Furthermore, as a result of the marked decline in the birth rate in the war years the average age of the population had risen and the number of workers per thousand of the total population had increased by a substantial amount.
76 1913 was itself a year of great activity in which new high records were set in many branches of German industry.
Source of data : Vierteljahrshefte zur Statistik des deutschen Reichs, passim.
77 The loss of capable workers killed or completely incapacitated in the war also gravely affected the average efficiency of the working class as compared with pre-war standards.
78 See supra, Table XXIV.
79 Economic Review, Vol. VIII, No. 16, London, October 19, 1923, quoting Deutsche Allgemeine Zeitung.
80 A marked feature of the inflation was the reduction of the difference between the wages of skilled and unskilled workers. The consequent lack of stimulus toward the acquisition of technical skill had its natural effect in diminishing the supply of well trained employees.
81 Vol. XVIII, section 1, October-December 1928, pp. 65-110. A uniform method of calculation and analogous indices already published by official agencies were used as far as possible.
82 Changes in population issuing out of transfers of territory are also taken into consideration in the former of the two sets of figures.
83 Russia is omitted owing to the extreme economic disturbances in that country, quite apart from those attributable to inflation. West Europe includes Germany, France, Belgium, and Italy. Figures for West Europe are weighted according to the population of the different countries included in the index.
84 Bulletin de la Statistique Generale de la France, loc. cit. The crops used for Germany were wheat, rye, barley, oats, potatoes, wine, hops, tobacco, hay. Figures from Statistisches Jahrbuch. For 1927 the index is calculated from the provisional results published by the International Institute of Agriculture at Rome.
85 There was some concealment by German farmers of their yields for the purpose of avoiding their full obligation on the required delivery of part of their crop at fixed (low) prices. The consequent understatement of yields in the official statistics has been alleged (not very responsibly) to have amounted to as much as 20%. This is improbable, but it might well have been as great as 10%.
86 Bulletin de la Statistique Generale de la France, loc. cit.
87 The index here given is checked by reference to the post-inflation indices of the Institut für Konjunkturforschung and of the Reparations Commission, both of which are computed by methods quite different from that here used but nevertheless give like results.
88 The decline in the English index in this year was mainly due to the coal strike.
89 The maintenance of the same figure for West Europe in 1921 as in 1920 is due solely to the increase in Germany’s production which was sufficient to balance the decline in the three other countries (France, Italy, and Belgium).
90 Poland, for instance.
91 For Belgium there are no satisfactory general price level statistics prior to August 1921 so that the 1921 fall in prices cannot be precisely determined. Belgium has therefore, of necessity been omitted from the comparison.
92 Relative, that is, to 1922. The year 1923 for Germany forms no proper basis of comparison in the determination of the effects of stable and unstable money since production in that year was gravely affected by non-monetary causes.
93 It is, of course, impossible accurately to impute the degree of depression due to falling prices as distinct from other causes. Under perfectly stable monetary conditions business cycles would perhaps recur much as they now do and price changes may be effects rather than causes of cycles. We do not know what production would have been if monetary conditions had been other than they were. Comparison with other countries where monetary conditions were different affords some, but by no means an infallible, criterion,
94The bulk of contracts made at this time were actually drawn, of course, in stable-value terms. But, even so, business men were subject to no disability; they simply failed to receive undue gains.
95 Gold prices in Germany fell by something over 10% in 1924 but the limits on the decline were always clearly discernible.
96 In practically all cases of transition from a situation in which the currency is rapidly falling in value to one in which it is stable or appreciating, the rate of monetary turnover is greatly retarded. Unless large new additions to the volume of circulating medium are made there will develop a shortage of “liquid capital,” that is, money, and prices will tend to fall. But caution in issue is necessary if a renewal of depreciation is to be prevented, and this is as true of credit as of money. Confidence must be restored at whatever cost, but confidence develops but slowly. The circulation in Germany was greatly expanded after stabilization had been effected. The process was somewhat too greatly accelerated at first and success was ultimately achieved only after the relative excess of circulating medium had been reduced through a sharp restriction of bank credit.
97 There is no evidence that agricultural yields in 1924 or 1926 were adversely affected by monetary phenomena.
98 The authors of Germany’s Capacity to Pay, quoting M. Tardieu, set the losses due to depreciation of plant and equipment at 43 billion gold marks. The total wealth of all kinds in Germany in 1913 has been estimated to have been approximately 300 billion gold marks but this includes land at 70 billion and foreign investments at 20 billion. See Deutschlands Volkswohlstand 1888-1913, Karl Helfferich, Verlag von George Stilke, Berlin, 1914, p. 113.
99 The enormous paper mark credits granted by the government to the Ruhr industrialists would have been practically impossible under stable monetary conditions.
100 Post-war territories ; Saar not included.
101 Lignite is expressed in terms of coal according to thermal efficiency (9 units of lignite = 2 of coal).
102 1913 only; 1909-1913 average not available. 1913 was an exceptionally good year. Index of general production is the Dessirier unweighted index.
103 The relatively large output of coal was called forth by the deliveries on reparation account.
104 cf. Die Wirtschaftskurve (the quarterly statistical publication of the Frank-furter Zeitung), Frankfurter Societäts-Druckerei G.m.b.H., Frankfurt-am-Main, passim.
105 It merely shows production per head of the total population.
106 This is shown both directly and by statistics on output per man-hour. The following figures of production in the Dortmund mines are probably typical of coal mining in general:
107Take for example, steel. The figures for 1913 and 1922, in million tons, are:
108This shortage was largely occasioned by reparations deliveries.
109 Figures for the base year, 1913, and all other years refer to the present German territory. The method of calculating the combined index of traffic (tons of freight) on railroads and inland waterways was as follows:
(1) Coalescence of freight categories was effected wherever necessary in order to make the commodity groups consistent for the two kinds of traffic and throughout the period covered.
(2) The 1913 figures were corrected for changes in territory. To do this, the “Lokalverkehr” (traffic within a given freight district) and “Auslandsverkehr” (traffic of a given freight district with foreign countries) for those districts separated from Germany after the war were subtracted from the total traffic in 1913. Traffic between the now separated districts and the rest of Germany has been included in the figures for 1913. It was then German domestic, it would now be German foreign, trade. The boundaries of the 1913 freight districts in the separated territories do not correspond exactly with the new political boundaries. The error involved in the overlapping one way or the other is unavoidable but is not large.
(3) Index numbers were calculated by commodity categories (79 in all) for both railroad and inland waterway traffic, with 1913, present territory, figures taken as a base.
(4) The ratio of the volume of each category of traffic in 1913 to total traffic in that year was then calculated for both types of transport.
(5) The index numbers resulting from step (3) were then multiplied by the ratios obtained in step (4) and added. The resulting index numbers of traffic on railroad and inland waterways are those given in the above table.
(6) The arithmetic mean of these 79 index numbers has been taken as the final index of total traffic on railroads and inland waterways combined.
110 The numbers given are those in the official statistics where the goods are classified alphabetically in German.
Sources of data: Statistik der Güterbewegung auf deutschen Eisenbahnen, 1913, 1920-1923, Vols. 80, 87-90, Statistisches Reichsamt; “Die Güterbewegung auf deutschen Eisenbahnen im Jahre 1924,” Statistik des deutschen Reicks, Vol. 325, Statistisches Reichsamt; “Verkehr der deutschen Binnenwasserstrassen im Jahre 1913, 1920-1924,” Statistik des deutschen Reichs, Vols. 274, 300, 306, 308, 313. 322, Statistisches Reichsamt, passim.
111 Average of all the items. Railroad traffic runs from 80 to 90% of the total in each year.
112 The transport of coal, for instance, which in 1913 formed 27% of the total railroad traffic, shows an index number in the later years consistently much below that for all commodities. The effect on the value of freight transported is, however, slight.
113 As computed by M. Dessirier in the Bulletin de la Statistique Généale de la France. The production indices here given are indices of total volume of production unweighted for changes in population except those due to a transfer of territory. Such unweighted figures are more comparable with the freight indices than are the weighted statistics.
114 Base figures refer to the present territory of Germany in both cases.
115 This would, of course, be generally expected.
116 The statistics on which the production indices are based are not to be greatly trusted in 1920.
117 The index for each year is set down as a percentage of that of the preceding year.
118 The general index of production cited in the earlier part of the chapter is partly made up from figures on the consumption of certain important raw materials.
119 By consumption is meant here, and in the sequel, delivery to the final consumer of the commodity in question whether it is a producers’ good or a consumers’ good. Similarly, production is whatever is delivered. In any one year goods may be fabricated in excess of the deliveries to the final consumer, or there may for that year be a deficiency made up out of stocks, but such differences are negligible where the margin of error in the statistics is certainly much greater than the change in unsold stocks from year to year. After the occupation of the Ruhr, accumulation of stocks was great enough to exert a considerable influence on the figures, since a large number of concerns then worked only for stock. No reliable figures, however, are available as to the volume of goods so accumulated.
120 The forced conversion of many plants from war to peace purposes must be regarded as an increase in true productive equipment. Much labor, however, was expended, at the behest of the Allied powers, in mere destruction of potential war equipment. This of course lowered production and domestic consumption coincidently. It should also be noted that, though industrial building was more than usually active, residential building was very slack.
121 This estimate is derived from German sources (Germany’s Economic and Financial Situation, Statistisches Reichsamt, Berlin, 1923), but unlike the property delivered under the armistice agreement, as to the value of which a huge difference exists between the estimates of the Germans and of the Reparations Commission, these deliveries from current production are valued at current world prices. The estimates may therefore be regarded as substantially accurate.
122 According to Karl Helfferich’s estimate in his Deutschlands Volkswohlstand 1888-1913, Verlag von Georg Stilke, Berlin, 1914, p. 97.
123 Figures for consumption of meat refer to calendar years, 1913, 1922, 1923.
124 Figures for consumption of sugar refer to years from Sept. l-Aug. 31.
125 The indices of production are for the calendar years 1913, 1920-1923, and are the Dessirier indices weighted for changes in population. Whatever differences may from year to year appear in the indices of agricultural and industrial production should not greatly affect consumption of foodstuffs since, in short crop years, imports of foodstuffs would tend to rise.
Source of data: Statistisches Jahrbuch 1924/25, 1926.
126Vessels of less than 100 tons gross omitted.
Source of data: Documents of the International Economic Conference, League of Nations Publications, C.E.I. 8., Geneva, 1927, p. 8.
127 The assertion here made might not be warranted if paper mark outlays should be converted into gold at current rates of exchange. But the exchange rate is not appropriate for this conversion. The wholesale price index is much better and, using this index, the assertion made in the text is true.
128 cf. Statistik der im Betriebe befindlichen Eisenbahnen Deutschlands, Reichs verkehrsministerium, Vol. 46, Berlin, 1926, p. 151.
129 Germany’s Economy, Currency and Finance, p. 104.
130 cf. “German Railway System After the War,” G. Francke, Manchester
Guardian Commercial, Reconstruction Supplement, Section VIII, Manchester, September 7, 1922, p. 405.
131 Mythology of Reparations, Robert Crozier Long, London, Duckworth, p. 106.
132 cf. British Dept. of Overseas Trade ; Report on Economic and Financial Conditions in Germany, London, 1924, p. 129. The reference is to the metallurgical industry but the condition is, elsewhere in the report, assumed to have been general.
133 Mythology of Reparations, R. C. Long, p. 125.
134 Statistics for only 31 districts are available throughout the period covered but figures for 72 districts from 1920 on are at hand. Each of the several districts represents, in the main, one of the largest cities so that the figures practically present industrial and commercial building in the cities. The table nowhere appears in this form in official statistics but is compiled from data in : (1) Statistisches Jahrbuch 1921/22; (2) Vierteljahrs hefte zur Statistik des Deutschen Reicks, 1920, IV ; 1922, I ; 1923,I ; 1924,I ; 1925, I.
135 Documents of the International Economic Conference, League of Nations Publications, C.E.I. 15, Vol. I., Geneva, 1927, p. 85. Figures derived from the Jahresberichten der Gewerbe-Aufsichtsbeamten und Bergbehörden.
136 ibid., according to data compiled by the Verein deutscher Maschinenbau-Anstalten.
137 The chemical industry is a partial exception but a large part of the increase in output of this industry was in artificial fertilizers, a capital good for agriculture.
138 As inflation progressed, the worker, it will be remembered, also paid a larger and larger share of the standard taxes since the income tax on wages was deducted at the source and therefore when it meant something in purchasing power. Although the total receipts from the income tax fell far, the worker paid as much as 10% of his wage in some months of 1922 and 1923. High surtaxes were levied on the larger incomes. Even a bare cost of living worker’s income became nominally large, however, with the progress of inflation. The worker could not postpone payment and consequently bore a heavy burden, cf. Deutschland und Frankreich, edited by R. Kuczynski, Verlag von R. L. Prager, Berlin, 1924, p. 27.
139 Measured, that is, by pre-war standards.
140 Aggregate real income is a combination of money wages, cost of living, and volume of employment.
141 See Workers Standard of Life in Countries with Depreciated Currency, International Labor Office, Series D., No. 15, Geneva, 1925, p. 25.
142 It should not be forgotten that the social insurance provided for the German worker has been much more extensive since the war than in 1913.
143 The extraordinary degree of activity in German industry in 1922 has already been noted. But this was the year in which the rate of depreciation of the currency began to rise with extreme speed. Wages lagged far behind prices. In 1923, however, the lag was reduced, and the wage figure in that year therefore corresponds more closely with production.
144 For the index of aggregate real income of the industrial population the mean of the yearly estimates of the International Labor Office has been taken. The 1923 figure is based on the estimate for the eight months January to August.
145 cf. The Workers Standard of Life in Countries with Depreciated Currency, p. 21.
146 To assign to inflation even as much as a quarter of the decline may perhaps be too much. The evil effects of the Ruhr occupation ran throughout that year and into 1924. Though the policy of passive resistance was officially abandoned on October 6, and though the German government announced on October 24 that it was ready, in principle, to resume the payment of reparations after impartial examination of Germany’s capacity had been made, there was no immediate relaxation of the grip of the occupying powers. After the rentenmark had been introduced an agreement was reached between the German industrialists and the Mission Interalliée de Controle des Usines et des Mines (under which the so-called “Micum” contracts were negotiated) which restored control of their properties to the German industrialists on condition that they deliver a sizable proportion of their output to the occupying Powers. (The German government was to reimburse the industrialists.) Activity in the Ruhr then began slowly to pick up. The crippling effect of the invasion, however, lasted well beyond the inflation period.
147 See supra, p. 291.
148 Helfferich’s estimate of 42 billion gold marks total income in 1913 is first reduced to 36 billion in order to apply to post-war territory only and to eliminate the computed difference in the return on foreign investments in 1913 and in the years here considered. This 36 billion is converted to post-1920 gold values (approximate index of gold prices on a 1913 base =150). The resulting 54 billion gold marks is then multiplied for each year by the appropriate index (Dessirier’s index weighted for changes in population) of industrial production (1923 = 56; 1924 = 80; 1926 = 90). The final figure should approximate the gold value of the total output of the German economy for the year to which it applies. The index of gold prices used for conversion is that of the United States Bureau of Labor Statistics. Since all other calculations of gold values are based on prices in the United States this seemed the best index to use, though gold prices in Germany were somewhat lower. The estimates of German income here made check fairly closely with computations otherwise derived. Thus the Institut für Konjunkturforschung, on the basis of income tax returns, estimated the German income in 1925 at 50 to 55 billion marks. (Vierteljahrshefte, 1926, I.) According to the method here used the 1925 income works out at approximately 51 billion marks.
149 Actual production has been estimated as being less than potential production in 1923, 1924, and 1926 by 10%, 10% and 5% respectively.
150 The 1920 income works out at 36.6 billion gold marks and the 1921 at 46.0 billion.
151 25% according to the index corrected for changes in population, 22% for the uncorrected index.
152 Business cycles do not, of course, show the same pattern synchronously in all parts of the world. But the depression of 1921 was evident in all countries in which prices followed the movement in the value of gold.
- 1cf. Foreign Banking Systems, H. P. Willis and B. H. Beckhart, editors, Chap, VIII, “The Banking System of Germany,” Paul Quittner, Henry Holt and Company, New York, 1929, p. 632, where it is declared that it would be useless to try to connect the development of the German currency system from 1919 to 1923 with any theories of money.
- 2A form of currency issued by officially established Loan Bureaus against the pledge of securities (or commodities) by borrowers other than the government and the larger banks and business concerns. During the war these notes formed an important share of the circulating medium but thereafter remained comparatively stable in absolute figures (7 to 14 billion marks) and were of constantly declining relative importance. They played but a slight ròle from 1921 onward.
- 3In the matter of mark exchange rates, for instance, sizable differences developed, in the later stages of inflation, between the Berlin and other markets. These were due to the obstruction of arbitrage transactions. At the time that this occurred, however, the Berlin rate was alone of much significance. The Berlin rates have therefore been used throughout. In the matter of prices the alternative sources are the indices of the Berliner Tageblatt, the Frankfurter Zeitung, and the Industrie- und Handelszeitung.
- 4The latter compilation was published in English, as well as in German, for use by the Committees of Experts of the Reparations Commission.
- 5Treasury notes, a fiduciary currency. These were, however, issued rather sparingly. The maximum issue was 356 million marks. Reichskassenscheine had been legal as cash cover in pre-war days but their issue had been closely restricted and few had been available. These Treasury notes are to be carefully distinguished from Treasury bills, a short-term security not used as money.
- 6Germany’s Economic and Financial Situation, Statistisches Reichsamt, Zentralverlag G.m.b.H., Berlin, 1923, p. 28.
- 7Zahlen zur Geldentwertung in Deutschland 1914 bis 1923, Statistisches Reichsamt, Verlag von Reimar Hobbing, Berlin, 1925, p. 46.
- 8Committee on Currency and Foreign Exchanges After the War (Cunliffe Committee) First Interim Report, H. M. Stationery Office, London, 1924, p. 5.
- 9Total bank deposits, exclusive of those of small private banks, were £716 million on June 30, 1914, and £1361 million on June 30, 1919. European Currency and Finance, United States Senate Commission of Gold and Silver Inquiry, Serial 9, Vol. I, Government Printing Office, Washington, 1925, pp. 277, 278.
- 10ibid., Vol. I, pp. 308, 470.
- 11ibid., Vol. I, pp. 534. 477, 455.
- 12Of this amount approximately 97 billion marks had been obtained through long-term loans.
- 13The climax in the reparations conflict came with the invasion of the Ruhr, an action which had no support from some of the creditor Powers. Much as the invasion is to be regretted or condemned, however foolish it may have been as a method of collecting payment, and however evil its immediate results, it was the thunderclap that cleared the air. It showed the obdurate creditors how little could be obtained by a policy of force and, on the other hand, it brought such distress to Germany as to convince even the stoutest opponent of the policy of fulfilment (and they were many and powerful) that it was better to accept a moderated burden of payments which, in spite of strong convictions to the contrary, it might be possible for the country to carry, than to continue in an attitude of stubborn intransigence.
- 14When force had led to disaster, the repercussions of which affected the creditors as well as the debtors, the way was at last open to men of conciliatory spirit, and a solution of the problem, or at any rate a working compromise, could be reached. The invasion was a tragic but triumphant vindication of the policy of moderation, and it led to sympathetic, even if selfish, efforts on the part of the creditor Powers to rehabilitate the economy and finances of the Reich. Once order had been restored progress was possible.
- 15Inflation was therefore combated but half-heartedly at best. Though several of the administrations of the years 1920 to 1923 made valiant attempts to arrest its progress they could not summon the sustained powers necessary to success. All of their efforts came to naught, largely through the apathy or active opposition of powerful business groups who were disposed neither to aid their government in imposing regular taxation nor to cooperate with it in carrying out its obligations under the Treaty of Versailles. Whatever might have been possible to a government backed by a people determined to have no further traffic with inflation, the will to establish a stable standard was lacking until the drama had run its course. It may well be doubted whether a stable standard could in any case have been set up while immense reparations debts were plaguing the situation. But this must remain an open question. So long as wealth and income were being merely transferred by the decline in the value of the monetary unit and not, as a sum, diminished, so long as scapegoats could be found to assume the burdens and yield of their substance to those who knew how to profit from the situation, projects of reform were treated cavalierly. It was only when enterprisers, instead of surely profiting from inflation as they long did, were suddenly plunged into a sea of uncertainties, only when business activity passed from the stage of exhilaration to panic, only when resistance to a further assumption of losses on the part of the public at large became general, that influential opinion veered to a conviction of the necessity of restoring a stable standard. The pass to which matters had then come is shown in Table III.
- 16The successful introduction of the rentenmark in November 1923, a currency without gold backing and, indeed, nothing more than a new tenor of inconvertible paper, with the monetary stabilization thus effected, has been hailed as a miracle. It was certainly a remarkable achievement and bears strong witness to the steadfastness of the German character. The time was ripe but extremely unpropitious. The people had lost all confidence in their currency and in the possibility of its reform. Foreign troops were in possession of their chief industrial districts and the coercive measures adopted by the occupying powers had paralyzed the industrial life of the country. The masses of the urban population were living from hand to mouth, nay, had nothing in their hands but worthless bits of paper which the farmers would no longer accept in exchange for grain. Food riots were general. Political dissolution was in imminent prospect and armed revolt had already raised its head. Affairs were indeed so black that it is clear, in retrospect, that they actually facilitated the reform by imbuing the people with the resolution of despair. The conduct of currency matters was given to Dr. Hjalmar Schacht who possessed the temperament necessary to the situation. His powers were presently enlarged by his election to the Presidency of the Reichsbank. The former President Havenstein had died on the very day that conversion of the old currency into the new was under-taken, a demise which cannot be thought of as other than opportune.
- 17The history of reparations till the adoption of the Dawes Plan in 1924 is an almost incredible tale of stupid persecution. The confusion of counsels and the vacillation in action which prevailed among the creditor Powers until the adoption of the Dawes Plan, the bickering and endless negotiation, the frustration of all attempts at compromise, were fatal to an orderly process of payments on the part of Germany even if payments in the amount demanded had, at the time, been practicable. The Allies began by demanding the impossible and they capriciously imposed sanctions when the impossible was not performed. Pending final determination of claims, the Versailles Treaty, effective January 10, 1920, required the Germans to deliver bonds as an instalment on their total debt to the value of 100 billion gold marks. Of this amount 20 billion were to mature on May l, 1921. Prior to that date the Reparations Commission was to fix the total of Germany’s obligations and, on the total so fixed, interest was to run at 5%. The Commission did not hand down its decision till April 27, 1921, when the debt was set at 132 billion gold marks. Meanwhile Germany had been making large payments in kind, the value of which was estimated by the Commission at 2.6 billion gold marks and by the Germans at several times that amount, but these were declared to have been inadequate to meet the costs of the armies of occupation. Though, in addition to the enormous levy on existing wealth under the Armistice and Treaty, the Germans had now for nearly two years been making large deliveries out of current production, they were held not only to have failed to pay any reparations at all, but to be steadily incurring still greater capital obligations through the accumulation of unpaid interest charges.
- 18The history of reparations till the adoption of the Dawes Plan in 1924 is an almost incredible tale of stupid persecution. The confusion of counsels and the vacillation in action which prevailed among the creditor Powers until the adoption of the Dawes Plan, the bickering and endless negotiation, the frustration of all attempts at compromise, were fatal to an orderly process of payments on the part of Germany even if payments in the amount demanded had, at the time, been practicable. The Allies began by demanding the impossible and they capriciously imposed sanctions when the impossible was not performed. Pending final determination of claims, the Versailles Treaty, effective January 10, 1920, required the Germans to deliver bonds as an instalment on their total debt to the value of 100 billion gold marks. Of this amount 20 billion were to mature on May l, 1921. Prior to that date the Reparations Commission was to fix the total of Germany’s obligations and, on the total so fixed, interest was to run at 5%. The Commission did not hand down its decision till April 27, 1921, when the debt was set at 132 billion gold marks. Meanwhile Germany had been making large payments in kind, the value of which was estimated by the Commission at 2.6 billion gold marks and by the Germans at several times that amount, but these were declared to have been inadequate to meet the costs of the armies of occupation. Though, in addition to the enormous levy on existing wealth under the Armistice and Treaty, the Germans had now for nearly two years been making large deliveries out of current production, they were held not only to have failed to pay any reparations at all, but to be steadily incurring still greater capital obligations through the accumulation of unpaid interest charges.
- 19The history of reparations till the adoption of the Dawes Plan in 1924 is an almost incredible tale of stupid persecution. The confusion of counsels and the vacillation in action which prevailed among the creditor Powers until the adoption of the Dawes Plan, the bickering and endless negotiation, the frustration of all attempts at compromise, were fatal to an orderly process of payments on the part of Germany even if payments in the amount demanded had, at the time, been practicable. The Allies began by demanding the impossible and they capriciously imposed sanctions when the impossible was not performed. Pending final determination of claims, the Versailles Treaty, effective January 10, 1920, required the Germans to deliver bonds as an instalment on their total debt to the value of 100 billion gold marks. Of this amount 20 billion were to mature on May l, 1921. Prior to that date the Reparations Commission was to fix the total of Germany’s obligations and, on the total so fixed, interest was to run at 5%. The Commission did not hand down its decision till April 27, 1921, when the debt was set at 132 billion gold marks. Meanwhile Germany had been making large payments in kind, the value of which was estimated by the Commission at 2.6 billion gold marks and by the Germans at several times that amount, but these were declared to have been inadequate to meet the costs of the armies of occupation. Though, in addition to the enormous levy on existing wealth under the Armistice and Treaty, the Germans had now for nearly two years been making large deliveries out of current production, they were held not only to have failed to pay any reparations at all, but to be steadily incurring still greater capital obligations through the accumulation of unpaid interest charges.
- 20Under Dr. Schacht’s firm grip it was but a short time before financial order was restored. The permanent success of Schacht’s measures was assured through the work of Chancellor Stresemann and Finance Minister Luther. The government balanced its budget, reparations were presently put upon a practicable basis with the adoption of the Dawes Plan in 1924, and German finances were once again given a solid footing.
- 21All this time cash reparations had been in abyance. Several conferences had been held, to some of which German representatives had been summoned and to others not, but, aside from the determination of the distribution of the payments when received, and demands for a series of annuities graduated steeply to 6 billion gold marks yearly, nothing decisive was done until the London Conference of March 1921. The Germans proposed at this meeting that they should assume a capital liability of 50 billion gold marks. Their offer was scornfully rejected, the Allies proceeded to occupy Düsseldorf, Duisburg and Ruhrort, to set up a customs barrier between the occupied and unoccupied parts of Germany, to sequestrate customs receipts on the Western frontier, and to enact Reparation Recovery Acts under which a large part of the value of their imports from Germany were retained for reparations purposes. The Reparations Commission followed this up with new demands which the Germans felt it impossible to meet. They again offered, however, to undertake an obligation of a capital sum of 50 billion gold marks and to pay annuities upon it up to a total of 200 billion. Though this is a much larger sum than will ever be paid under the arrangement now in operation, and was probably more than the Allies even then ever expected to receive, it was contumaciously spurned, on the ground, apparently, that Germans bearing gifts were to be suspected beyond measure. On May 5, 1921, a schedule of payments, drawn up at London by the Supreme Council of the Allies, required the delivery of bonds to the value of the gold mark total of the debt as set by the Reparations Commission, ordered annual payments of two billion gold marks plus 26% of German exports, and demanded the immediate delivery of one billion gold marks in cash.
- 22Revenues, apart from borrowing, then covered about 60% of expenditures including payments under the Treaty of Versailles. By the end of the year they covered only about 28%.
- 23Cash reparations actually paid no longer played a dominating rôle in inflation though the then hopeless prospect of a relaxation of the Allied demands, and the general expectation of the imposition of further sanctions, were potent influences. On July 12, 1922, Germany applied for a complete lifting of all further obligations for that year and stated that the desperate position of the fise would make it impossible to meet the Allied demands for a further period of two years or more. After weeks of bickering among the creditors, during which Germany was held to the schedule earlier laid down, matters reached an impasse at the end of August. The deadlock was finally broken when the Belgians, who were to receive the balance of the 1922 payments, agreed to accept six months’ Treasury bills (payable in gold and guaranteed by the Reichsbank) in lieu of immediate cash. The respite thus gained by the Germans was of no avail. The toboggan of currency depreciation was then travelling much too rapidly to be checked by any such puny means and, before the notes fell due, the occupation of the Ruhr pushed it over the precipice. Except to take up the bills given to Belgium in the preceding summer, no cash reparations were paid in 1923 and though, on the invasion of the Ruhr, reparations in kind were suspended toward the occupying Powers only, that action was generalized in August. After the collapse of the attempt to support mark exchange in the first four months of the invasion, and of a second similar, but much feebler, essay in July, the era of astronomic monetary magnitudes began. Prices, exchange rates, and the volume of circulating medium vied with one another in daily and hourly upward leaps. The Reichsbank was finally reduced to making apologies for its inability to provide for a weekly output of more than several billion (or trillion) of marks of the required denomination and to an expression of its hope that this situation would be quickly remedied by an improvement in the speed of the printing presses! The printing presses did their bit. By the end of inflation the daily output of currency was over 400,000,000,000,000,000 marks. But, strange as it may seem, this did not effect the expected cure!
- 24Cash reparations actually paid no longer played a dominating rôle in inflation though the then hopeless prospect of a relaxation of the Allied demands, and the general expectation of the imposition of further sanctions, were potent influences. On July 12, 1922, Germany applied for a complete lifting of all further obligations for that year and stated that the desperate position of the fise would make it impossible to meet the Allied demands for a further period of two years or more. After weeks of bickering among the creditors, during which Germany was held to the schedule earlier laid down, matters reached an impasse at the end of August. The deadlock was finally broken when the Belgians, who were to receive the balance of the 1922 payments, agreed to accept six months’ Treasury bills (payable in gold and guaranteed by the Reichsbank) in lieu of immediate cash. The respite thus gained by the Germans was of no avail. The toboggan of currency depreciation was then travelling much too rapidly to be checked by any such puny means and, before the notes fell due, the occupation of the Ruhr pushed it over the precipice. Except to take up the bills given to Belgium in the preceding summer, no cash reparations were paid in 1923 and though, on the invasion of the Ruhr, reparations in kind were suspended toward the occupying Powers only, that action was generalized in August. After the collapse of the attempt to support mark exchange in the first four months of the invasion, and of a second similar, but much feebler, essay in July, the era of astronomic monetary magnitudes began. Prices, exchange rates, and the volume of circulating medium vied with one another in daily and hourly upward leaps. The Reichsbank was finally reduced to making apologies for its inability to provide for a weekly output of more than several billion (or trillion) of marks of the required denomination and to an expression of its hope that this situation would be quickly remedied by an improvement in the speed of the printing presses! The printing presses did their bit. By the end of inflation the daily output of currency was over 400,000,000,000,000,000 marks. But, strange as it may seem, this did not effect the expected cure!
- 25Though the war, and the peace, dealt heavy blows to the German economy and though poverty was for some years inevitable, the losses in domestic income like those in territory, natural resources, and property, furnish no adequate explanation of the collapse of the internal value of the currency. Not even state bankruptcy is, in itself, a sufficient cause. “The existence of ‘budgetary equilibrium’ is not necessary [to stability of the currency]. ... An absolutely bankrupt State can have a perfectly good currency without a trace of inflation.” But this possibility can be realized only by the outright repudiation of state obligations. The consequences of such repudiation must always be weighed against the dangers involved in meeting the situation by the issue of fiat money. In the case of Germany, repudiation of recurring reparations obligations would have meant an early application of military sanctions by the victor Powers and complete loss of German sovereignty. Few would deny that to keep things going even temporarily, by inflation of the currency, was the lesser of the evil courses open to the German government and people.
- 26Though the war, and the peace, dealt heavy blows to the German economy and though poverty was for some years inevitable, the losses in domestic income like those in territory, natural resources, and property, furnish no adequate explanation of the collapse of the internal value of the currency. Not even state bankruptcy is, in itself, a sufficient cause. “The existence of ‘budgetary equilibrium’ is not necessary [to stability of the currency]. ... An absolutely bankrupt State can have a perfectly good currency without a trace of inflation.” But this possibility can be realized only by the outright repudiation of state obligations. The consequences of such repudiation must always be weighed against the dangers involved in meeting the situation by the issue of fiat money. In the case of Germany, repudiation of recurring reparations obligations would have meant an early application of military sanctions by the victor Powers and complete loss of German sovereignty. Few would deny that to keep things going even temporarily, by inflation of the currency, was the lesser of the evil courses open to the German government and people.
- 27State bankruptcy lay on the knees of the gods. To repair the ravages of war and to restore order in public finance it was urgently necessary that all remaining economic resources should be carefully husbanded and that the fise should be replenished with revenues derived entirely from taxation. But, along with peace, revolution was ushered into Germany and the energies of the people were wasted in internal conflict. The struggle for control of the new republic not only prevented remedial measures in public finance but enormously increased the existing difficulties. The continuation of the war blockade till after the signing of the Peace of Versailles, June 28, 1919, further augmented the troubles of the government, for though circuses were denied, the people had to be supplied with bread.
- 28In the course of the year 1919 the outstanding volume of discounted Treasury bills rose from 55 to 86 billion marks, the index of the cost of dollar exchange from 1.97 to 11.94 (1913=1) and the index of wholesale prices from 2.45 to 8.03 (1913=1). The increase in the currency from 33 to 50 billion marks was comparatively slight, showing that, in spite of the disturbances, the public or commercial banks were buying the discounted Treasury bills from the Reichsbank. This buying was especially marked after the internal political situation had somewhat cleared but the sale of government securities was perforce confined to short-term issues since the future was too obscure to permit the flotation of bonds.
- 29The administration was far from dilatory and the reform of the finances was attacked with vigor at the earliest practicable moment. The old central government had always been without direct taxing powers and the new did not for some time acquire any greater authority. The constitution, adopted at Weimar August 11, 1919, gave to the Reich the right of legislation over the revenues to be devoted, in whole or in part, to its own purposes but it was not until December 13, 1919, that a federal tax administration could be provided for. Meanwhile, customs duties had been put on a gold basis, an extraordinary single levy had been imposed on corporations, and a heavy tax laid on war profits. Before the year was out legislation establishing a turnover tax had been passed and a special capital levy, the Reichsnotopfer, or National Emergency Contribution, had been ordered. Under the leadership of Finance Minister Erzberger the whole taxing system was revised in March 1920, control of taxation was largely transferred from the States to the federal government, and new impositions were laid on corporations and on the yield of capital. Few sources of revenue remained unexplored and the rates imposed were heavy. But the government was running a losing race with inflation. Its efforts to balance its budget were unsuccessful, the deficiency was made up by short-term loans necessitating constant new issues of currency, and the resulting depreciation depressed revenues still further. Classes of property easy to tax and capable in normal times of providing large revenues were falling rapidly in real value. This was true of all securities yielding a fixed monetary return and also of rentals. The latter were practically confiscated by inflation and by housing legislation felt to be socially indispensable. The depreciation of the currency led to a proper resistance to the taxation of such paper mark incomes as were wholly illusory but the resentment against injustice was perverted to secure unwarranted exemptions. The resulting complexity of the tax structure, the administration of which was necessarily inefficient, still further reduced the revenues. The greatest source of loss, however, lay in the fact that, between the period for which a tax was levied and the dates of assessment and collection, a decline in the value of the currency might wipe out all but a small portion of the purchasing power of the sum received.
- 30The administration was far from dilatory and the reform of the finances was attacked with vigor at the earliest practicable moment. The old central government had always been without direct taxing powers and the new did not for some time acquire any greater authority. The constitution, adopted at Weimar August 11, 1919, gave to the Reich the right of legislation over the revenues to be devoted, in whole or in part, to its own purposes but it was not until December 13, 1919, that a federal tax administration could be provided for. Meanwhile, customs duties had been put on a gold basis, an extraordinary single levy had been imposed on corporations, and a heavy tax laid on war profits. Before the year was out legislation establishing a turnover tax had been passed and a special capital levy, the Reichsnotopfer, or National Emergency Contribution, had been ordered. Under the leadership of Finance Minister Erzberger the whole taxing system was revised in March 1920, control of taxation was largely transferred from the States to the federal government, and new impositions were laid on corporations and on the yield of capital. Few sources of revenue remained unexplored and the rates imposed were heavy. But the government was running a losing race with inflation. Its efforts to balance its budget were unsuccessful, the deficiency was made up by short-term loans necessitating constant new issues of currency, and the resulting depreciation depressed revenues still further. Classes of property easy to tax and capable in normal times of providing large revenues were falling rapidly in real value. This was true of all securities yielding a fixed monetary return and also of rentals. The latter were practically confiscated by inflation and by housing legislation felt to be socially indispensable. The depreciation of the currency led to a proper resistance to the taxation of such paper mark incomes as were wholly illusory but the resentment against injustice was perverted to secure unwarranted exemptions. The resulting complexity of the tax structure, the administration of which was necessarily inefficient, still further reduced the revenues. The greatest source of loss, however, lay in the fact that, between the period for which a tax was levied and the dates of assessment and collection, a decline in the value of the currency might wipe out all but a small portion of the purchasing power of the sum received.
- 31There is, however, every reason to believe that, apart from the recurring impositions of the Treaty of Versailles, a budgetary balance would have been achieved and inflation checked. Tax revenues in 1920 yielded the equivalent of 4090 millions of gold marks and in the following year 5235 millions. Expenditures in 1921, exclusive of the deficit of the state railways and payments under the Treaty of Versailles, were equal to 5738 million gold marks. The railway deficit was eliminated in the following year. Leaving it out of account, the ratio of taxes to outlays for domestic purposes in 1921 was 91.2%, an achievement which compared very favorably with that of most of the victor nations. The expenditures under the treaty, however, were themselves approximately equal to all other expenditures combined, and therefore to the total yield from taxes. Unless the improvement in the finances should proceed steadily forward the handwriting on the wall was clear and startling.
- 32There is, however, every reason to believe that, apart from the recurring impositions of the Treaty of Versailles, a budgetary balance would have been achieved and inflation checked. Tax revenues in 1920 yielded the equivalent of 4090 millions of gold marks and in the following year 5235 millions. Expenditures in 1921, exclusive of the deficit of the state railways and payments under the Treaty of Versailles, were equal to 5738 million gold marks. The railway deficit was eliminated in the following year. Leaving it out of account, the ratio of taxes to outlays for domestic purposes in 1921 was 91.2%, an achievement which compared very favorably with that of most of the victor nations. The expenditures under the treaty, however, were themselves approximately equal to all other expenditures combined, and therefore to the total yield from taxes. Unless the improvement in the finances should proceed steadily forward the handwriting on the wall was clear and startling.
- 33The facts are that neither in gold mark values nor in the purchasing power of paper marks did revenues continue to advance. The appended Chart II shows the matter clearly. By the middle of 1921 the tax reforms of 1919-1920 had produced their maximum effect but it was far short of the requirements of the Reich and a further twist of the screw of taxation was obviously necessary. But tax revision takes time. A greatly extended and intensified tax program was adopted in the spring of 1922 and tax revenues once again, for a month or so, approached the level of expenditures. But it was then too late. The approach to a balance had been achieved only through a partial moratorium on reparations and the threatening attitude of the principal creditors left no hope of a permanent alleviation on this score. Moreover the last bulwark against currency collapse was crumbling. The people at home began to lose all confidence in their money. Exchange rates, prices, and governmental expenses soared, but tax revenues, while increasing in paper mark totals, lagged hopelessly behind. Finally, in late 1923, taxes covered only 1% to 2% of expenditures and many taxes did not yield the cost of collection.
- 34The facts are that neither in gold mark values nor in the purchasing power of paper marks did revenues continue to advance. The appended Chart II shows the matter clearly. By the middle of 1921 the tax reforms of 1919-1920 had produced their maximum effect but it was far short of the requirements of the Reich and a further twist of the screw of taxation was obviously necessary. But tax revision takes time. A greatly extended and intensified tax program was adopted in the spring of 1922 and tax revenues once again, for a month or so, approached the level of expenditures. But it was then too late. The approach to a balance had been achieved only through a partial moratorium on reparations and the threatening attitude of the principal creditors left no hope of a permanent alleviation on this score. Moreover the last bulwark against currency collapse was crumbling. The people at home began to lose all confidence in their money. Exchange rates, prices, and governmental expenses soared, but tax revenues, while increasing in paper mark totals, lagged hopelessly behind. Finally, in late 1923, taxes covered only 1% to 2% of expenditures and many taxes did not yield the cost of collection.
- 35But whether the fall in the exchange value of the currency at any time was or was not greater than the decline in its domestic purchasing power, the result was merely to accentuate or mitigate the lag of revenues which was inherent in the depreciation itself. This is especially true of the period after the middle of 1922. For the year May 1921 to April 1922, a year of heavy cash payments on reparations account, the low relative value of the mark on the exchange markets was of great importance in determining the condition of the Treasury, but the mere fact of currency depreciation, regardless of the relation between the internal and external value of the monetary unit, was thereafter the sole significant factor. For the greater part of 1923 there was a steady rise in the relative value of the mark on the exchanges but this was of slight consequence since the government was then making no cash reparations payments and the precipitous fall in the absolute value of the currency, both within and without the country, led, in any case, to exiguous revenues in comparison with the enormous increase in outlays.
- 36Taxes on commodities tended to increase in paper mark totals as prices rose but, as the pace of depreciation waxed, even these were of little value by the time they accrued to the Treasury. The one gray spot on the otherwise immaculate blackness of the Treasury’s position from mid-1922 to the end of inflation came as a result of the temporary stabilization of exchange rates and prices in the spring of 1923. This result, achieved through intervention by the Reichsbank on the exchange market, cost the bank heavily and, in the existing state of government finance, it was a gesture only. It temporarily raised the ratio of revenues to expenditures but the marked increase in the latter, consequent upon the policy of passive resistance, would have led to another reversal even if the support of the mark had been maintained for much longer than in fact proved possible. From May onward the ratio of the monthly increase in the floating debt to state revenue from all other sources grew higher and higher. In the last half-year of inflation, only an insignificant fraction of expenditures was covered other than by the discount of Treasury bills and the ensuing emission of Reichsbank notes. In practical effect the government had ceased to collect ordinary taxes and was financing its activities all but solely through issues of fiat money.
- 37As of November 15.
- 38The illustration is taken from Germany Since the War, Peter P. Reinhold, Institute of Politics Publications, Yale University Press, New Haven, 1928, p. 53.
- 39cf. Valuta, Karl Diehl and Paul Mombert, Verlag G. Braun, Karlsruhe, 1925, p. 13.
- 40Prices and volume of circulating medium showed generally similar movements.
- 41“Speculative” is to be construed broadly to include the activities of commercial houses who took claims to future marks in exchange for goods.
- 42Purchases made with the intent of holding the currency indefinitely.
- 43cf. Die Reichsbank, Gert von Eynern, Verlag von Gustav Fischer, Jena, 1928, p. 74. Von Eynern thinks that the exports which had gone out in response to the low exchange value of the mark were primarily responsible for this improvement in the exchange situation.
- 44The quid pro quo is usually a claim to future goods (securities) though capital may of course be exported as a gift or as tribute.
- 45Other than sight bills of exchange would not strictly meet this definition but, though payment in this case is not immediate, it is deferred for a few months at most. As a national matter payment may, however, be deferred indefinitely whenever a fund of foreign exchange is acquired by the creditor country the constituent units of the fund constantly coming to maturity and as constantly being replaced by new units. There was some export of capital, in this sense, from Germany, but the amount involved does not appear to have been large, cf. infra, Chap. x.
- 46*Vessels of less than 100 tons gross omitted.
- 47The exporter of capital acquires rights to future not to present goods.
- 48The scintilla of truth in the expression lies in the degree in which Germans bought foreign exchange with immediately cashed claims to marks and held a fund of it as an investment. But even this was compensated, many times over, by foreign holdings of marks.
- 49There would, however, be no effect on mark exchange if the marks were sold to another foreign investor who would otherwise not have been in the market.
- 50Exchange dealings were authorized only for mercantile transactions. The idea was that by diminishing the offers of marks the exchange rate would be sustained. It is an open question whether the policy did not defeat its own end since the passion to sell marks merely impelled their possessors to offer them clandestinely on ever cheaper terms in the competition to obtain buyers in a greatly narrowed market. The mark was, as it were, squeezed into a funnel.
- 51It should be noted that, while in the absence of a sufficient export of goods and of investment opportunities in Germany, buyers of marks as a group were almost sure to lose, no matter how apparently cheap the German currency on the exchange markets seemed to be, this was not necessarily true of individual buyers. It was a question of how quickly the marks could be turned into real values. This led to a scramble, with the devil taking the hindmost, but with the foremost emerging with considerable gains. The latter possibility was always a force on the bullish side of mark exchange. It was not sufficient, to keep exchange rates at anything like par with internal prices, since the chance of large gains had to be present, but it imposed some limit on the upward movement of foreign currencies.
- 52In the chart the relatively slower rise of exchange rates is shown by a ratio declining with respect to prices.
- 53cf. Currency and Credit, R. G. Hawtrey, Longmans, Green and Co., London, 1923, pp. 51, 52. Hawtrey points out that in countries like Germany, where deposit credit is not highly developed, the control of credit by the central bank is comparatively easy.
- 54Over the period of 60 months from January 1919 to December 1923 a reduction in the Reichsbank end-of-the-month holdings of bills was generally accompanied by an improvement in the exchange value of the mark and an increase in holdings was generally accompanied by a decline in that value. This inverse correlation fails to occur, however, in 19 of the 60 months. Assuming a lag of exchange rates behind holdings of Treasury bills of one month, there are only 17 points at which the movements of the two series are in the same direction. Considering only the period from February 1920 through December 1923 (47 months), the number of points where the two series do not move in opposite directions are as follows : with no lag, 16 points; with a lag of exchange of one month, 13 points; with a lag of exchange of 15 days, 11 points.
- 55From the end of the war onward the circulation of notes in France was a fairly constant quantity. It fluctuated between 35 and 40 billions of francs from the middle of 1919 to the end of 1924. In the latter year an increase began which carried it to 56 billion in 1926 and France was, for a time, in grave danger of treading in Germany’s footsteps. Only at the eleventh hour was the process checked by the vigorous measures adopted by the Coalition Cabinet under Premier Poincaré.
- 56Notes might be issued against “cash” cover consisting of gold, German coin, Treasury notes (Reichskassenscheine), or Loan Bureau notes (Darlehnskassenscheine) or against non-cash cover consisting of Treasury bills (Reichsschatzwechsel) or commercial bills. In May 1921, (inauguration of cash reparations), the regulation requiring that at least one-third of the note circulation must be backed by “cash” cover was indefinitely suspended.
- 57No one was willing to leave sums on deposit only to have their value melt away. The commercial banks, moreover, did not follow the Reichsbank lead in keeping their interest rates low but stepped them up in some degree of correspondence with the presumptive loss of value between the date of borrowing and of repayment. Up to the end of 1921, however, bank deposits had fairly well kept pace with the depreciation of the currency. Dr. Alfred Lansburgh, writing in Die Bank, July 1922, attributes this to the deposit in German banks of actual mark currency reimported from abroad.
- 58The excess of the total of bills discounted over the issue of notes is presumably due either to private holding of Treasury bills or to deposit credits (in lieu of notes) with the Reichsbank.
- 59Through an arrangement made by the government with the Reichsbank and the Rentenbank.
- 60The figures for December are convertible into rentenmarks at a trillion to one.
- 61See Workers Standard of Life in Countries with Depreciated Currency, International Labor Office, Series D., No. 15, Geneva, 1925, p. 25.
- 62A good share of the borrowing was for the purpose of buying foreign exchange as an investment, cf. Deutsche Währungs- und Kreditpolitik, Rudolf Dalberg, Verlag von Reimar Hobbing, Berlin, 1926, p. 12. Foreign exchange could be used as collateral for further loans. Business concerns were therefore under no disability in acquiring accumulations of exchange. The privilege of borrowing on foreign exchange collateral was eventually withdrawn but exchange might then be used to buy stable-value German government loans which were, in turn, used as collateral for borrowings in marks.
- 63In March 1922 the Reichsbankgesetz had been so amended as to make the institution “completely” independent of the government. The legislation was adopted under external political pressure and was a dead letter from the beginning.
- 64Besides the Reichsbank, the four quasi-official banks of Bavaria, Saxony, Würtemberg and Baden had the right to issue notes. (These banks are usually designated “the private banks of issue.”) While their quota was from time to time, during the inflation years, extended, it was always insignificant in relation to Reichsbank issues and declined in comparative importance as inflation proceeded.
- 65cf. The Workers Standard of Life in Countries with Depreciated Currency, p. 21.
- 66To assign to inflation even as much as a quarter of the decline may perhaps be too much. The evil effects of the Ruhr occupation ran throughout that year and into 1924. Though the policy of passive resistance was officially abandoned on October 6, and though the German government announced on October 24 that it was ready, in principle, to resume the payment of reparations after impartial examination of Germany’s capacity had been made, there was no immediate relaxation of the grip of the occupying powers. After the rentenmark had been introduced an agreement was reached between the German industrialists and the Mission Interalliée de Controle des Usines et des Mines (under which the so-called “Micum” contracts were negotiated) which restored control of their properties to the German industrialists on condition that they deliver a sizable proportion of their output to the occupying Powers. (The German government was to reimburse the industrialists.) Activity in the Ruhr then began slowly to pick up. The crippling effect of the invasion, however, lasted well beyond the inflation period.
- 67See supra, p. 291.
- 68The 1920 income works out at 36.6 billion gold marks and the 1921 at 46.0 billion.
- 69Figures are available only on the basis of deposits payable within seven days. These are construed as demand deposits.
- 70Computed from data in the Memorandum on Currency and Central Banks 1913-1924, League of Nations Publications, Geneva, 1925, Vol. II, p. 269. The figure for 1923 is based on data in which no figures from the Deutsche Bank were included. It has been assumed that the movement in the Deutsche Bank paralleled that in the other institutions.
- 71CLIFFE-LESLIE once remarked that in social matters the greatest scientific progress is made when economic disorders raise vexing questions as to their causes. In the study of social phenomena, disorder is, it is true, the sole substitute for the controlled experiments of the natural sciences. But it sometimes happens that, in the midst of disorder, events move so rapidly that we are not able properly to observe them; disorder may be excessive even to the most detached of scientists. The course of inflation in Germany in the first post-war quinquennium had so much of this character that it has seemed to many to be incapable of throwing any light upon monetary problems. This most striking of monetary experiences has, in consequence, evoked a minimum of scientific curiosity. In spite of the fact that statistics—those notes of process on which the social scientist must so heavily rely—were for some phenomena abandoned in Germany in this period and for others are open to grave objection on the score of accuracy, it has seemed to me that such an attitude implies an unwarranted surrender in the face of difficulties which might with perseverance be surmounted. This book is an attempt, therefore, to discover what actually happened in Germany and either to bring the observed phenomena within the fold of accepted theory or else so to modify that theory as to give it a more catholic character. The actual course of events during inflation has not merely an historical and scientific interest but is of considerable practical importance. Germany’s present position as a nation with heavy international obligations has led to apprehension, both within and without the Reich, as to the future in international finance. The fears of such German competition as may issue out of the debtor status may be dismissed as but thinly-veiled mercantilism but the question as to the possibility of ultimate transfer of the large sums involved in reparations and interest payments must, perhaps, be treated with more respect. The ability of the German economy to provide, within Germany, the funds required, is, on the other hand, no longer seriously doubted. It is hoped that the sequel will throw some light on the disappearance of the latter doubt as also on the prospect of future transfers undisturbed by any serious economic friction.
- 72in Germany. It is based very largely on official German statistics as published by the Statistische Reichsamt and the Institut für Konjunkturforschung. These statistics, for the period studied, are, no doubt, far from perfect, but nothing is gained by attempting to go behind them and there is no reason to suppose that such alternative sources as are available are at all superior. The hope is cherished, perhaps not without justification, that such errors as are involved do not vitiate the conclusions reached. The immense nominal magnitudes attained by all -monetary phenomena in Germany in the inflation-time tend to dwarf the influence of even very considerable imperfections in the statistics. I am far from supposing, nevertheless, that the results obtained are to be taken as clearly proven and I trust that the reader will be no more credulous. They are merely hypotheses
- 73The publications of the Statistische Reichsamt which have been principally used are : Statistisches Jahrbuch für das deutsche Reich, Statistik des deutschen Reichs, Wirtschaft und Statistik, Monatliche Nachweise über den auswärtigen Handel Deutschlands, Zahlen zur Geldentwertung in Deutschland 1914 bis 1923, and Germany’s Economy, Currency and Finance. Sparing use has been made of forms of statistics already available in these sources and, where tables are given in the text, they are, in nearly all cases, the result of computations from the original data.
- 74The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 75The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 76The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 77The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 78The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 79The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 80The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 81Wholesale prices in Germany, Great Britain and France at the end of 1918 were respectively 2.45, 2.30 and 3.53 times their pre-war height. In the United States they were just about twice their 1913 level.
- 821
- 83The occupation, by French and Belgian troops, took place in the early days of January 1923. The British government of the day adopted an attitude of passive disapproval and Italy, while assenting to the measures taken, refused to participate actively in the occupation.
- 84The exchange value of French currency, for instance, was brought very low when it became apparent that the French fise could not count on any large receipts from Germany.
- 85When the administration proposed a capital levy to meet the burdens imposed, the industrialists countered with the offer of a loan of one billion gold marks. But, as negotiations proceeded, the industrialists demanded a remission of future taxes and the turning over to them of the state railroads. The government properly refused and resorted to a forced loan which, however, yielded only 50 million gold marks.
- 86The provisions for redemption in “rentenbank certificates” and the mortgage cover provided had, as all students of monetary phenomena will recognize, but a psychological value. The success of the rentenmark was due entirely to the rigid limitations on issue.
- 87The reform was carried out without foreign assistance of any sort. Rather was there covert opposition from certain powerful foreign groups who would have welcomed the threatened political, as well as financial, dissolution of the Reich.
- 88Dr. Schacht has written an excellent account of the reform in his Stabilization of the Mark, George Allen and Unwin Ltd., London, 1927.
- 89
- 90Though practically all of the various administrations in Germany up to the invasion of the Ruhr made sincere efforts to satisfy the claims of the victors, a measure of persecution may have been necessary to break down the overt or covert resistance of financially powerful Germans in private life. The defiance offered the Allies by men like Hugo Stinnes greatly increased the suspicion and hostility toward the Germans, as a people, and was a fateful error. But though persecution may have been necessary to the securing of such reparations as the Germans could pay, if they would, the stupid malice of certain Allied politicians was heartrending. Much of it was due to the still ardent passions of war, either in the breasts of the politicians themselves or in those of their constituents, but a great deal must be attributed to sheer ineptitude. For a time it seemed as if reparation demands were being used merely as a weapon to bring about the disintegration of the Reich. But, if this purpose was ever held, the double-edged character of the sword soon became apparent. For years thereafter the policy was simply one of vacillation. The Bourbons were of the same mind as ever but they had somewhat lost in influence. Liberals grew stronger as time went on but for long the issue hung in the balance. Either party might attain a superiority and temporarily dominate the situation but the final adoption of a policy of moderation was not attained till the “spirited” group had had their fling in the Ruhr.
- 91This sum is almost half the estimated total wealth of Germany in 1913. The maximum payments under the Dawes Plan were about one-third of the interest on this sum and even these have now been recognized by the creditors to have been excessive.
- 92Shortly after the inauguration of the reform Stresemann was followed by Marx as Chancellor, but Stresemann remained in the Cabinet.
- 93In exchange for the 100 billion originally delivered.
- 94Just at this point the German government had brought its tax revenues into some semblance of equivalence with outlays, foreign exchange rates had shown no rising trend for more than a year, domestic prices had been steady, and the circulation of Reichsbank notes, while increasing, had not risen consistently or at a very rapid rate. Under threat of further sanctions the Germans paid in May (1921) 150 million gold marks in cash (foreign exchange). Drafts on the Treasury maturing within three months and guaranteed by the German banks were tendered, and accepted, for the remaining 850 millions immediately payable. The purchase of foreign bills with which to cover these drafts drove the exchange value of the mark steadily downward. At the end of August 400 million gold marks were still unpaid but a six-weeks covering credit was arranged in Holland and England. The repayment of this loan extended the pressure on mark exchange into October. The index of the monthly average of dollar exchange rates (number of paper marks to the dollar equivalent of one gold mark) rose from 14.8 in May to 62.6 in November, the index of wholesale prices (1913 = 1) from 13.1 to 34.1, and the ratio of the monthly increase in the floating debt to all other state revenue from 50% to 155%.
- 95The Reichsbank held gold reserves much more than adequate to cover this obligation.
- 96The justification alleged for this action was that the Germans had voluntarily defaulted in making the full timber deliveries required of them.
- 97The reparations demands might, however, have caused a fall in the exchange value of the mark regardless of its value in the domestic markets.
- 98See An Economist’s Protest, Edwin Cannan, P. S. King & Son, Ltd., London, 1927, P. 393.
- 99In order to prevent Communistic disorder relief had to be given to the unemployed and subsidies provided for the import of such foodstuffs as could, at whatever price, be obtained. A large part of the gold reserve of the Reichsbank was devoted to the procuring of food imports.
- 100This increase was equivalent to about $2,000,000,000 according to the average of wholesale prices for the year.
- 101Except in a limited measure the taxing power had been reserved to the constituent States.
- 102Before the war the federal government had had but the rudiments of a fiscal administration. All taxes were handled by the fiscal organization in the several States. Direct taxes were, in principle, confined to the States while indirect taxes were left to the central government. In the later years of the war, however, an excess profits tax had been levied by the federal government in addition to new and increased indirect taxes. Such a tax might come under the German concept of indirect taxes.
- 103As passed, the latter tax, instead of being a single contribution as originally intended, was distributed over a considerable period.
- 104When prices were rapidly rising goods might be sold for more than they had cost (in monetary terms) but for less than the sum at which they could be replaced. If so an accounting profit was actually a real loss.
- 105The system and the personnel were new and had no precedents on which to build.
- 106cf. Germany’s Economy, Currency and Finance, p. 96. Paper marks are con-verted according to the index of cost of living which is the most representative index for expenditures other than those arising under the Treaty of Versailles.
- 107It reappeared, however, as inflation advanced.
- 108Gold mark values are obtained by converting paper mark figures according to the index of wholesale prices. Government expenditures were partly determined by exchange rates (cash reparations), partly by wholesale prices (reparations in kind and other purchases of commodities), and partly by the cost of living (wages and salaries). An official investigation showed, however, that the gold value of expenditures of the several sorts, when measured by the appropriate index, corresponded closely, at this period, with the gold value of the total paper mark expenditures converted according to the index of wholesale prices, cf. Germany’s Economy, Currency and Finance, p. 95.
- 109Adjustment of yields was attempted for the different taxes through:
- 110The marked influence of exchange rate fluctuations on the condition of the German fise will be apparent when it is noted that from April 1920 to May 1921 foreign exchange showed no upward tendency, that from June to November the dollar was five times multiplied in mark value, that from December 1921 to June 1922 a second period of relative stability in exchange intervened, and that from July 1922 onward the upward march, or flight, of exchange rates was practically continuous.
- 111This table is an average of three sets of figures calculated on the cost of living index, wholesale price index, and dollar index, respectively. The original figures are given in millions and tenths of millions of gold marks. Since they run to the first decimal place only, slight discrepancies occur between the totals and the sums of the individual items when the average of the three sets is taken. The decimal place has been omitted in the above table and minor corrections made in order to secure consistent totals. The balancing of the original tables leaves something to be desired and some small adjustments were necessary on this account.
- 112cf. infra, Chart VI. The relative rise appears in the decline in the index of foreign exchange rates relative to that of wholesale prices.
- 113Inflation was, of course, a concealed method of taxation. It has been stated, with apparent accuracy, that the German government would actually have been better off if it had given up ordinary tax collection altogether. Taxes, as a whole, cost more to collect than they brought in. The issues of fiat money would therefore have been smaller if the whole of the ordinary taxing machinery had been discarded.
- 114
- 115Table V shows by months the total amount of discounted bills outstanding and the volume of Reichsbank note issues. The figures in the table are not, of course, to be interpreted as representing the difference between financing the state requirements partly by taxation, as in the earlier years, and wholly by fiat money, as in the later. They reflect this situation very obscurely and show, in the main, simply the depreciation of the currency. The hundreds of quintillions of marks, in November 1923, were actually of much less gold value than the comparatively insignificant totals of discounts and note issues in earlier years. The depreciation of the currency thus not only wiped out the pre-inflation federal debt but also was continually reducing the burden of the enormous current borrowings. If one were to take thousand-mark notes and pile them tightly together one on top of the other the sum of values would not equal the government’s borrowing from the Reichsbank until the pillar was twenty-five billion times as high as the loftiest mountain on earth. Yet, at the rate at which the mark was converted into the new stable-value currency (a trillion to one), the total discounted bills outstanding on November 15, 1923, were worth less than fifty million dollars.
- 116Great has been the abuse heaped upon the exchange speculator as a destroyer of currencies. Most of this abuse is due to the conscious or unconscious search for a scapegoat and is unwarranted by the facts. But though speculators who persistently operate against the trend of fundamental forces are certain to be eliminated, and so cannot long affect the market, it is not to be denied that bear speculation may depress the exchange value of a monetary unit, that the fall in the currency’s exchange value may provoke retrogression in its domestic purchasing power and in the public finances of the country concerned, that new issues of notes may thus be induced, that the consequent further fall in exchanges may justify the speculation from the point of view of private profit and may lead to continued bearish operations which, in the manner just indicated, actually bring about the depreciation on which the operators count.
- 117Speculation in the mark was rampant both on the bull and on the bear side of the market though the two movements did not by any means coincide. The post-war history of German inflation, so far as foreign exchange is concerned, shows several clearly marked major movements as follows:
- 118In the immediate post-war period the speculative dealing was predominantly on the bull side of mark exchange and, indeed, till late in 1922, the persistent foreign speculative buying of German currency was one of the most striking aspects of inflation. It is doubtful whether bear activities ever fully counteracted this steady buying. As a result, however, of the operation of forces much more fundamental than speculation, the mark sagged in 1919 at a steady and, for that time, rapid rate, and the speculators as a group took heavy losses. Those who had played the part of bears of course iriade money but the situation was reversed after March 1920 when, in the course of a little more than two months, the mark rose nearly 200% (100.13 to the dollar on March 4; 34.75 to the dollar on May 25). This was the heyday of the bull movement and as usual it was overdone. The exchange value of the mark had been carried beyond the point at which it would be sustained by basic factors and it slowly slid back toward the current equilibrium level. In the ensuing months speculation was not very active except for the so-called investment demand but, with the beginning of cash reparations, the bears were presented with a near certainty of success. Knowing that the government must procure foreign exchange in large volume, and that it had no means of doing so except by further note issues, the “spot” purchase of foreign exchange or the sale of mark futures carried a rich promise of profits to the speculator. This situation continued from June to November 1921. Investment buying of marks was then on the decline and it is probable that speculative selling operated to produce the situation it anticipated. The farther bear speculation drove the mark down the worse became the situation of the fise. The discounts of Treasury bills and emissions of Reichsbank notes consequently grew larger, with a reflex again on the exchanges, and so on in indefinite repetition. The only escape was to have mark exchange fall so far below the domestic purchasing power of the currency as to lead to purchases for present use or to speculation for a rise. If this should occur the spin of the circle would be checked and perhaps reversed. It actually was checked when relief from reparations payments was temporarily obtained in late 1921.
- 119In the immediate post-war period the speculative dealing was predominantly on the bull side of mark exchange and, indeed, till late in 1922, the persistent foreign speculative buying of German currency was one of the most striking aspects of inflation. It is doubtful whether bear activities ever fully counteracted this steady buying. As a result, however, of the operation of forces much more fundamental than speculation, the mark sagged in 1919 at a steady and, for that time, rapid rate, and the speculators as a group took heavy losses. Those who had played the part of bears of course iriade money but the situation was reversed after March 1920 when, in the course of a little more than two months, the mark rose nearly 200% (100.13 to the dollar on March 4; 34.75 to the dollar on May 25). This was the heyday of the bull movement and as usual it was overdone. The exchange value of the mark had been carried beyond the point at which it would be sustained by basic factors and it slowly slid back toward the current equilibrium level. In the ensuing months speculation was not very active except for the so-called investment demand but, with the beginning of cash reparations, the bears were presented with a near certainty of success. Knowing that the government must procure foreign exchange in large volume, and that it had no means of doing so except by further note issues, the “spot” purchase of foreign exchange or the sale of mark futures carried a rich promise of profits to the speculator. This situation continued from June to November 1921. Investment buying of marks was then on the decline and it is probable that speculative selling operated to produce the situation it anticipated. The farther bear speculation drove the mark down the worse became the situation of the fise. The discounts of Treasury bills and emissions of Reichsbank notes consequently grew larger, with a reflex again on the exchanges, and so on in indefinite repetition. The only escape was to have mark exchange fall so far below the domestic purchasing power of the currency as to lead to purchases for present use or to speculation for a rise. If this should occur the spin of the circle would be checked and perhaps reversed. It actually was checked when relief from reparations payments was temporarily obtained in late 1921.
- 120In the immediate post-war period the speculative dealing was predominantly on the bull side of mark exchange and, indeed, till late in 1922, the persistent foreign speculative buying of German currency was one of the most striking aspects of inflation. It is doubtful whether bear activities ever fully counteracted this steady buying. As a result, however, of the operation of forces much more fundamental than speculation, the mark sagged in 1919 at a steady and, for that time, rapid rate, and the speculators as a group took heavy losses. Those who had played the part of bears of course iriade money but the situation was reversed after March 1920 when, in the course of a little more than two months, the mark rose nearly 200% (100.13 to the dollar on March 4; 34.75 to the dollar on May 25). This was the heyday of the bull movement and as usual it was overdone. The exchange value of the mark had been carried beyond the point at which it would be sustained by basic factors and it slowly slid back toward the current equilibrium level. In the ensuing months speculation was not very active except for the so-called investment demand but, with the beginning of cash reparations, the bears were presented with a near certainty of success. Knowing that the government must procure foreign exchange in large volume, and that it had no means of doing so except by further note issues, the “spot” purchase of foreign exchange or the sale of mark futures carried a rich promise of profits to the speculator. This situation continued from June to November 1921. Investment buying of marks was then on the decline and it is probable that speculative selling operated to produce the situation it anticipated. The farther bear speculation drove the mark down the worse became the situation of the fise. The discounts of Treasury bills and emissions of Reichsbank notes consequently grew larger, with a reflex again on the exchanges, and so on in indefinite repetition. The only escape was to have mark exchange fall so far below the domestic purchasing power of the currency as to lead to purchases for present use or to speculation for a rise. If this should occur the spin of the circle would be checked and perhaps reversed. It actually was checked when relief from reparations payments was temporarily obtained in late 1921.
- 121The greatest effect exerted by speculators in exchange is ordinarily supposed to have occurred after the middle of 1922 when the home population, having lost all confidence in the currency, rushed in a frenzy into the exchange markets and initiated, the so-called export of capital. The export of capital and the flight from the mark, so far as the latter phrase means the exchange of the mark for foreign currency, have been generally used as synonymous expressions. In reality they have no connection with one another. The essence of an export of capital is the transfer to residents of a foreign country of the ownership of immediate claims to goods (and later, when the claims are exercised, of the goods themselves), without any obligation on the capital importer to furnish similar immediate claims in return. A foreign exchange transaction is not of this type but is a barter of immediate monetary claims to goods in one national market against immediate monetary claims to goods in another. It is true that either or both of the bartered claims may have been obtained in exchange for deferred obligations in the other currency (a claim to future goods) or may later be used to purchase them. But there is nothing in the sale of a currency itself to show that this is occurring. There can, indeed, be no net export of real capital in the actual purchase and sale of exchange. All that happens is a swapping of claims on currencies, with the nationals of each country, after the transaction, owning the equivalent in present goods (or claims thereto) of their former possessions. This is true whether, for instance, a German sells for marks American exchange to another German, to an American, or to a foreigner not a citizen of the United States. Whatever the details, in no case would either country send out capital in the exchange transaction.
- 122The greatest effect exerted by speculators in exchange is ordinarily supposed to have occurred after the middle of 1922 when the home population, having lost all confidence in the currency, rushed in a frenzy into the exchange markets and initiated, the so-called export of capital. The export of capital and the flight from the mark, so far as the latter phrase means the exchange of the mark for foreign currency, have been generally used as synonymous expressions. In reality they have no connection with one another. The essence of an export of capital is the transfer to residents of a foreign country of the ownership of immediate claims to goods (and later, when the claims are exercised, of the goods themselves), without any obligation on the capital importer to furnish similar immediate claims in return. A foreign exchange transaction is not of this type but is a barter of immediate monetary claims to goods in one national market against immediate monetary claims to goods in another. It is true that either or both of the bartered claims may have been obtained in exchange for deferred obligations in the other currency (a claim to future goods) or may later be used to purchase them. But there is nothing in the sale of a currency itself to show that this is occurring. There can, indeed, be no net export of real capital in the actual purchase and sale of exchange. All that happens is a swapping of claims on currencies, with the nationals of each country, after the transaction, owning the equivalent in present goods (or claims thereto) of their former possessions. This is true whether, for instance, a German sells for marks American exchange to another German, to an American, or to a foreigner not a citizen of the United States. Whatever the details, in no case would either country send out capital in the exchange transaction.
- 123The greatest effect exerted by speculators in exchange is ordinarily supposed to have occurred after the middle of 1922 when the home population, having lost all confidence in the currency, rushed in a frenzy into the exchange markets and initiated, the so-called export of capital. The export of capital and the flight from the mark, so far as the latter phrase means the exchange of the mark for foreign currency, have been generally used as synonymous expressions. In reality they have no connection with one another. The essence of an export of capital is the transfer to residents of a foreign country of the ownership of immediate claims to goods (and later, when the claims are exercised, of the goods themselves), without any obligation on the capital importer to furnish similar immediate claims in return. A foreign exchange transaction is not of this type but is a barter of immediate monetary claims to goods in one national market against immediate monetary claims to goods in another. It is true that either or both of the bartered claims may have been obtained in exchange for deferred obligations in the other currency (a claim to future goods) or may later be used to purchase them. But there is nothing in the sale of a currency itself to show that this is occurring. There can, indeed, be no net export of real capital in the actual purchase and sale of exchange. All that happens is a swapping of claims on currencies, with the nationals of each country, after the transaction, owning the equivalent in present goods (or claims thereto) of their former possessions. This is true whether, for instance, a German sells for marks American exchange to another German, to an American, or to a foreigner not a citizen of the United States. Whatever the details, in no case would either country send out capital in the exchange transaction.
- 124The greatest effect exerted by speculators in exchange is ordinarily supposed to have occurred after the middle of 1922 when the home population, having lost all confidence in the currency, rushed in a frenzy into the exchange markets and initiated, the so-called export of capital. The export of capital and the flight from the mark, so far as the latter phrase means the exchange of the mark for foreign currency, have been generally used as synonymous expressions. In reality they have no connection with one another. The essence of an export of capital is the transfer to residents of a foreign country of the ownership of immediate claims to goods (and later, when the claims are exercised, of the goods themselves), without any obligation on the capital importer to furnish similar immediate claims in return. A foreign exchange transaction is not of this type but is a barter of immediate monetary claims to goods in one national market against immediate monetary claims to goods in another. It is true that either or both of the bartered claims may have been obtained in exchange for deferred obligations in the other currency (a claim to future goods) or may later be used to purchase them. But there is nothing in the sale of a currency itself to show that this is occurring. There can, indeed, be no net export of real capital in the actual purchase and sale of exchange. All that happens is a swapping of claims on currencies, with the nationals of each country, after the transaction, owning the equivalent in present goods (or claims thereto) of their former possessions. This is true whether, for instance, a German sells for marks American exchange to another German, to an American, or to a foreigner not a citizen of the United States. Whatever the details, in no case would either country send out capital in the exchange transaction.
- 125The greatest effect exerted by speculators in exchange is ordinarily supposed to have occurred after the middle of 1922 when the home population, having lost all confidence in the currency, rushed in a frenzy into the exchange markets and initiated, the so-called export of capital. The export of capital and the flight from the mark, so far as the latter phrase means the exchange of the mark for foreign currency, have been generally used as synonymous expressions. In reality they have no connection with one another. The essence of an export of capital is the transfer to residents of a foreign country of the ownership of immediate claims to goods (and later, when the claims are exercised, of the goods themselves), without any obligation on the capital importer to furnish similar immediate claims in return. A foreign exchange transaction is not of this type but is a barter of immediate monetary claims to goods in one national market against immediate monetary claims to goods in another. It is true that either or both of the bartered claims may have been obtained in exchange for deferred obligations in the other currency (a claim to future goods) or may later be used to purchase them. But there is nothing in the sale of a currency itself to show that this is occurring. There can, indeed, be no net export of real capital in the actual purchase and sale of exchange. All that happens is a swapping of claims on currencies, with the nationals of each country, after the transaction, owning the equivalent in present goods (or claims thereto) of their former possessions. This is true whether, for instance, a German sells for marks American exchange to another German, to an American, or to a foreigner not a citizen of the United States. Whatever the details, in no case would either country send out capital in the exchange transaction.
- 126THOUSAND TONS*
- 127Now the flight from the mark was not due to an impulse on the part of Germans to export capital, that is, an impulse to give to foreigners immediate claims on German goods in exchange for a postponed command over foreign commodities, but merely to a desire to swap present purchasing power in their own currency for anything which would retain its value. If capital had really been in process of exportation from Germany there would have been no trouble. It is just because there was almost no capital capable of export that mark exchange fell so rapidly. Insofar as German exchange was held by foreigners as an investment, and thus approached the category of securities, it is much more nearly true to say that capital was being imported into Germany, either actually, in the shape of an excess of commodity imports which would otherwise not have been possible, or constructively, in the acquisition by sellers of marks of present property in foreign countries. In exchange for the capital actually or constructively imported the Germans offered marks or mark claims which were, in effect, promises to pay on demand, throughout an indefinite period, an undetermined but steadily diminishing amount of purchasing power over German goods—provided the withdrawal of those goods were permitted by the German authorities. So far as the marks were bought and held by foreigners till they became worthless this process was not even an exchange of capital, to say nothing of a net export. It is therefore all but quite erroneous to speak of the flight from the mark into foreign currencies as an export of capital.
- 128Now the flight from the mark was not due to an impulse on the part of Germans to export capital, that is, an impulse to give to foreigners immediate claims on German goods in exchange for a postponed command over foreign commodities, but merely to a desire to swap present purchasing power in their own currency for anything which would retain its value. If capital had really been in process of exportation from Germany there would have been no trouble. It is just because there was almost no capital capable of export that mark exchange fell so rapidly. Insofar as German exchange was held by foreigners as an investment, and thus approached the category of securities, it is much more nearly true to say that capital was being imported into Germany, either actually, in the shape of an excess of commodity imports which would otherwise not have been possible, or constructively, in the acquisition by sellers of marks of present property in foreign countries. In exchange for the capital actually or constructively imported the Germans offered marks or mark claims which were, in effect, promises to pay on demand, throughout an indefinite period, an undetermined but steadily diminishing amount of purchasing power over German goods—provided the withdrawal of those goods were permitted by the German authorities. So far as the marks were bought and held by foreigners till they became worthless this process was not even an exchange of capital, to say nothing of a net export. It is therefore all but quite erroneous to speak of the flight from the mark into foreign currencies as an export of capital.
- 129Marks could not be sold without being bought and when foreigners purchased marks, or claims to marks, they could do one of three things with them. ( 1 ) They could hold them either abroad or on deposit in Germany or they could lend or otherwise invest them in Germany. In this case the original support given the mark by their demand would be subject to no diminution. (2) They could later buy exportable goods with them. If these goods would not otherwise have been purchased the upward impetus to mark exchange arising from the original demand for the marks would be sustained. (3) They could sell the marks already purchased. In this case the original support given the mark by the investor’s purchase might in part be cancelled. But even here any decline in the value of the mark between the date of the original and the later transaction would make the pressure on mark exchange much lighter than an equivalence with the support originally given.
- 130It is clear that, taking the whole period of post-war inflation into consideration and assuming that a fixed amount of foreign exchange was unconditionally required by the Germans, the sale of the currency was a bullish factor on its exchange value. This was specially true of the earlier years. In the final stages of inflation, moreover, it was not the sale of the currency (the so-called export of capital) which was of any significance in depressing its value but the fact that sellers were intensely eager and sales extremely hard to make. In the first place they were prohibited by the German government but, more important perhaps, the lists of gullible foreign buyers had by this time been fairly well exhausted. There were few individuals ready to buy, with stable-value currencies, a monetary unit which was rushing to its doom. Clearly it was the attitude of the buyers and sellers of marks toward the wares of which they were making disposal and acquisition, and not the sales themselves, which was the fundamental influence in driving the value of the mark downward and, per contra, in raising to the sky the mark value of foreign exchange.
- 131It is clear that, taking the whole period of post-war inflation into consideration and assuming that a fixed amount of foreign exchange was unconditionally required by the Germans, the sale of the currency was a bullish factor on its exchange value. This was specially true of the earlier years. In the final stages of inflation, moreover, it was not the sale of the currency (the so-called export of capital) which was of any significance in depressing its value but the fact that sellers were intensely eager and sales extremely hard to make. In the first place they were prohibited by the German government but, more important perhaps, the lists of gullible foreign buyers had by this time been fairly well exhausted. There were few individuals ready to buy, with stable-value currencies, a monetary unit which was rushing to its doom. Clearly it was the attitude of the buyers and sellers of marks toward the wares of which they were making disposal and acquisition, and not the sales themselves, which was the fundamental influence in driving the value of the mark downward and, per contra, in raising to the sky the mark value of foreign exchange.
- 132From the beginning of 1923, at latest, practically the sole sources of foreign exchange were the proceeds of German commodity exports or of such property as foreigners bought in Germany. Exchange dealings involving the mark must have been confined largely to the Germans themselves since foreign sellers of goods to Germany were invoicing in stable currencies, German sellers were in large measure also following this practice, there was no foreign investment demand for marks, and the supply of marks purchased by foreigners in previous years, and subject to sale, cut no appreciable figure at the value to which the mark had then fallen. Practically the sole market for marks thus lay with German exporters who had acquired foreign exchange and were ready to part with it at a price which would enable them to employ immediately, and at a profit, the mark proceeds of the sale of their exchange. The transaction thus resolved itself into a close calculation of the relative advantages of holding foreign exchange or of selling it against marks and buying goods at home. There was thus no tendency for exchange rates to rise far in advance of prices, and internal prices at this time did, in fact, advance even more rapidly than foreign exchange. (See infra, Chart VI.) There is thus no reason to believe that the panic flight from the mark expressed itself primarily in the exchange markets. On the contrary the evidence runs in the opposite direction. The final cataclysm can therefore not be attributed to speculation on the exchange markets even when that term is extended to include German buying of foreign currencies as a safeguard against ruin and with the intention of holding the purchased moneys indefinitely. Purchases of foreign exchange were only one, and it would seem not the dominating, aspect of a general repudiation of the mark. The exchange market was closed to legal speculation and, even if exchange bootlegging had been successfully prevented, it is unlikely that the rates would have deviated very widely from those actually established. Arbitrage as between foreign exchange and commodities would have kept exchange rates in approximately the same relation to domestic prices as did in fact take place. Domestic prices were affected as directly as exchange rates by the flight from the mark and exchange speculation was no more active than speculation in commodities.
- 133Whenever gold payments are suspended the gold value of a currency may depreciate gravely as a result of the operations of commercial banks even if such banks have no note issuing powers. The range of depreciation is ordinarily widened if the government is forced to resort to short-term borrowing but, if its obligations ultimately find their way into the investment portfolios of the public, the road to recovery is still open. State borrowing may indeed be carried on in excess of the absorptive capacity of the public, and without irreparable damage, provided the banking organization takes up an adequate volume of the government’s floating obligations. Up to this point inflation can be confined to an expansion of bank credit on a relatively constant monetary base. Though such credit may be stretched far, the more or less stable proportion of money to credit instruments which is required by established business habits keeps credit expansion within at least measurable bounds. This is especially true where, as in Germany, the commercial banks are dependent for cash reserves on the note issues of the central institution. But, when a government can no longer in any manner place its securities, and is forced to cover deficits by persistent direct issues of notes, the constant growth in the monetary base greases the ways for the launching of unlimited currency depreciation. The post-war inflationary experience of Great Britain, where the original value of the monetary unit was eventually restored, may be taken as partially representative of the first type of inflation, that of France, where a large floating debt was a constant menace until the reforms of 1926 resulted in the stabilization of the currency unit at about 1/5 of its original value, as typical of the second, while Germany is the arch-exemplar of the third.
- 134Whenever gold payments are suspended the gold value of a currency may depreciate gravely as a result of the operations of commercial banks even if such banks have no note issuing powers. The range of depreciation is ordinarily widened if the government is forced to resort to short-term borrowing but, if its obligations ultimately find their way into the investment portfolios of the public, the road to recovery is still open. State borrowing may indeed be carried on in excess of the absorptive capacity of the public, and without irreparable damage, provided the banking organization takes up an adequate volume of the government’s floating obligations. Up to this point inflation can be confined to an expansion of bank credit on a relatively constant monetary base. Though such credit may be stretched far, the more or less stable proportion of money to credit instruments which is required by established business habits keeps credit expansion within at least measurable bounds. This is especially true where, as in Germany, the commercial banks are dependent for cash reserves on the note issues of the central institution. But, when a government can no longer in any manner place its securities, and is forced to cover deficits by persistent direct issues of notes, the constant growth in the monetary base greases the ways for the launching of unlimited currency depreciation. The post-war inflationary experience of Great Britain, where the original value of the monetary unit was eventually restored, may be taken as partially representative of the first type of inflation, that of France, where a large floating debt was a constant menace until the reforms of 1926 resulted in the stabilization of the currency unit at about 1/5 of its original value, as typical of the second, while Germany is the arch-exemplar of the third.
- 135To the extent that the Reichsbank could dispose of Treasury bills to the commercial banks or to the general public it could withdraw its own issues from circulation and to the extent that the Treasury could sell its bills directly to the same buyers no new issues of paper money were involved. If the Reichsbank had ever been able to effect a permanent reduction in its holdings of Treasury bills, or even to prevent their increase, the progress of inflation could have been stayed. But it will be remembered that, from the Armistice to the end of the period of inflation, the end-of-the-month figures of outstanding discounted Treasury bills show an absolutely uninterrupted increase although the holdings of such bills by the Reichsbank were, on several occasions, temporarily lowered. These reductions correspond roughly with improvements in the exchange value of the mark, though the cause and effect relationship is not indisputable. Whatever the causal sequence may have been, the correlation is significant of what might have been accomplished if the reduction in Reichsbank holdings could have been made other than ephemeral. But of this the persistent growth in the total of Treasury discounts did not permit. Statistics on the amount of Treasury bills held by the Reichsbank, the proportion which the latter bore to the total Treasury bills discounted, and the ratio of Reichsbank note issues to its holdings of these bills are given in Table VI.
- 136But Reichsbank note issues were not dependent on Treasury borrowing only. In pre-war days the non-cash cover of Reichsbank notes had consisted of commercial bills. Against the discount of such bills the bulk of the pre-war circulation had been issued. The provision permitting commercial bills as cover was retained in the war- and postwar period and the output of notes was thus conditioned by private as well as by government borrowing. The percentage of Reichsbank note issues to the total of discounted Treasury bills in the portfolio of the bank was therefore frequently above 100% though the ratio was reduced by the share of both private and government discounts which were left on deposit in the central institution rather than taken in the form of notes. Reference to Table VI will show that the volume of note issues began to exceed the Reichsbank holdings of Treasury bills at the beginning of 1920. The use of commercial bills had almost entirely ceased during the war and was not widely resumed till the middle of 1922 so that, to that time, the cover for Reichsbank notes, other than that provided by Treasury bills, was either coin, bullion, Reichskassenscheine or Darlehnskassenscheine. None of the latter types of cover were of great quantitative significance in comparison with the Treasury bill. Inflation, till mid-1922, was therefore dominated by Treasury deficits.
- 137The shrinkage of all types of bank deposits and the resulting scarcity of credit, which grew marked as inflation advanced, impelled the Reichsbank, in the summer of 1922, to urge the readoption of the commercial bill as a credit instrument. A low discount rate was applied and, under the existing condition of continuous currency depreciation, the rediscounting of commercial bills became an obvious recourse for the private banks. The Reichsbank’s portfolio of commercial bills consequently grew rapidly in spite of a gradual diminution in the bank’s enthusiasm in the matter and of subsequent large but always inadequate increases in the rate. The figures for discounted commercial bills, for total discounted bills (commercial plus Treasury), and for note issues are given in Table VII.
- 138REICHSBANK DISCOUNT OF COMMERCIAL BILLS, TOTAL BILLS DISCOUNTED, AND NOTE ISSUES; 1922 AND 1923{Billions of Marks)
- 139From a negligible amount in June 1922 the Reichsbank discount of commercial bills thus rose to one-third of its total discounts in April 1923, that is, the commercial bills amounted to one-half as much as the Treasury bills. From then on a relative decline in the volume of commercial bills discounted set in and this tendency continued till just prior to the currency reform in November. After November 15 there was no further discounting of Treasury bills, the former government discounts were taken up, and commercial bills occupied the whole stage. Though discounts for the Treasury continued to be preeminent up to the end of inflation the credits put at the disposal of the commercial banks thus played a rôle of considerable importance. The ratio of Reichsbank discount of commercial bills to total note issues is given in Table VIII. Though, even in 1923, the ratio did not rise much above the status in 1914 it must be remembered that in the pre-war period the Reichsbank did comparatively little discounting for the government. The fillip given to inflation by the premium put on private borrowing from the Reichsbank cannot therefore be denied. In this connection the relation between prices and exchange rates is worthy of notice. Up to 1923 domestic prices had risen much less than foreign exchange rates but in that year they no longer lagged behind. The conclusion is possibly warranted that the volume of notes issued as a result of Treasury operations only, huge as it was, had been short of the amount necessary to sustain the domestic price level on a basis of equality with the depreciation in the exchange value of the currency, but that, when Reichsbank credit was made easy to private banks and commercial borrowers, the total volume of means of payment was extended to any degree requisite to keep pace with the plunging value of the currency on the exchange markets.
- 140From a negligible amount in June 1922 the Reichsbank discount of commercial bills thus rose to one-third of its total discounts in April 1923, that is, the commercial bills amounted to one-half as much as the Treasury bills. From then on a relative decline in the volume of commercial bills discounted set in and this tendency continued till just prior to the currency reform in November. After November 15 there was no further discounting of Treasury bills, the former government discounts were taken up, and commercial bills occupied the whole stage. Though discounts for the Treasury continued to be preeminent up to the end of inflation the credits put at the disposal of the commercial banks thus played a rôle of considerable importance. The ratio of Reichsbank discount of commercial bills to total note issues is given in Table VIII. Though, even in 1923, the ratio did not rise much above the status in 1914 it must be remembered that in the pre-war period the Reichsbank did comparatively little discounting for the government. The fillip given to inflation by the premium put on private borrowing from the Reichsbank cannot therefore be denied. In this connection the relation between prices and exchange rates is worthy of notice. Up to 1923 domestic prices had risen much less than foreign exchange rates but in that year they no longer lagged behind. The conclusion is possibly warranted that the volume of notes issued as a result of Treasury operations only, huge as it was, had been short of the amount necessary to sustain the domestic price level on a basis of equality with the depreciation in the exchange value of the currency, but that, when Reichsbank credit was made easy to private banks and commercial borrowers, the total volume of means of payment was extended to any degree requisite to keep pace with the plunging value of the currency on the exchange markets.
- 141
- 142From a negligible amount in June 1922 the Reichsbank discount of commercial bills thus rose to one-third of its total discounts in April 1923, that is, the commercial bills amounted to one-half as much as the Treasury bills. From then on a relative decline in the volume of commercial bills discounted set in and this tendency continued till just prior to the currency reform in November. After November 15 there was no further discounting of Treasury bills, the former government discounts were taken up, and commercial bills occupied the whole stage. Though discounts for the Treasury continued to be preeminent up to the end of inflation the credits put at the disposal of the commercial banks thus played a rôle of considerable importance. The ratio of Reichsbank discount of commercial bills to total note issues is given in Table VIII. Though, even in 1923, the ratio did not rise much above the status in 1914 it must be remembered that in the pre-war period the Reichsbank did comparatively little discounting for the government. The fillip given to inflation by the premium put on private borrowing from the Reichsbank cannot therefore be denied. In this connection the relation between prices and exchange rates is worthy of notice. Up to 1923 domestic prices had risen much less than foreign exchange rates but in that year they no longer lagged behind. The conclusion is possibly warranted that the volume of notes issued as a result of Treasury operations only, huge as it was, had been short of the amount necessary to sustain the domestic price level on a basis of equality with the depreciation in the exchange value of the currency, but that, when Reichsbank credit was made easy to private banks and commercial borrowers, the total volume of means of payment was extended to any degree requisite to keep pace with the plunging value of the currency on the exchange markets.
- 143The intensity of the stimulus toward borrowing from the Reichsbank may be gauged from a comparison of the sluggish rise in the discount rate at the central bank with the ever-accelerated pace of currency depreciation. From the early days of the war till the end of June 1922 the Reichsbank rate remained unchanged at 5%; it was raised to 6% in July, to 7% in August, 8% in September and 10% in November 1922, to 12% in January 1923, 18% in April, 30% in August and 90% in September. But these increases were as nothing when measured alongside the progressive lightening in the burden of a loan during the time for which it ran. Though, after September 1923, a bank or private individual had to pay at the rate of 900% per annum for a loan from the Reichsbank, this was no deterrent to borrowing. It would have been profitable to pay a so-called interest, in reality an insurance, charge, of thousands or even millions of per cents per annum, since the money in which the loan would be repaid was depreciating at a speed which would have left even rates like these far in the rear. With a 900% interest rate in September 1923 the Reichsbank was practically giving money away and the same is true of the lower rates in the preceding months when the course of depreciation was not quite so headlong. The policy of the Reichsbank authorities in encouraging the discount of commercial bills that they might thus mitigate the scarcity of credit was but further evidence of the Alice-in-Wonderland determination of the directors of that institution to run ever faster in order to keep up with themselves. The scarcity of credit was due solely to currency depreciation and the cure prescribed was to increase the volume of means of payment ! The Reichsbank could not refuse to discount Treasury bills but the policy on commercial bills was a gratuitous mortification of an already fatal wound.
- 144Aside from accepting the opportunity to secure central bank credit which was thus thrust upon them, and of somewhat extending their own operations on the basis of this credit, the commercial banks played a subordinate part in the whole inflation process. Deposits in the commercial banks grew, of course, as paper money streamed forth from the Reichsbank, and the credits granted corresponded measurably with the upward surge of prices. But the commercial banks had no note issuing powers and their own contribution to inflation was therefore necessarily confined to an expansion of loans the proceeds of which were left on deposit. No figures are available which make it possible to separate with any precision commercial deposits resulting from loans from those actually brought in by customers. Table IX, however, shows total bank deposits in comparison with total money in circulation and the ratio between them. Except in 1922, when rediscounting of commercial bills at the Reichsbank was being encouraged, the ratio, during inflation, was lower than in the pre-war period. The figure at the end of 1923 is affected by the fact that the currency reform had just then been gotten under way. Time deposits which had wellnigh vanished under the spell of depreciation were not yet being restored and the banks were extremely cautious about extensions of commercial credit. The ratio of deposits had been further reduced by the incredibly rapid issue of bank notes in the last days of the old mark. The 1924 figure is given to show the gradual return to “normal” stable-standard conditions.
- 145
- 146Since the increase in the numbers of unemployed had already begun in October 1922, it is probable that some part of the depression in the early months of 1923 was directly due to the dislocation issuing out of the immense acceleration in the rate of currency depreciation (which began in the fall of 1922 and was almost uninterrupted thereafter), rather than to the Ruhr invasion. But, though this may possibly be true, the recovery in the summer of 1923 does not offer any corroboration of such a view. Not until the final three months of the paper mark regime can a deleterious effect on industry be clearly traced to the collapse of the currency. Something between a quarter and a third of the decline in output in 1923 (estimated at 37% lower than 1922) should therefore be assigned to monetary disturbances with the probability running toward the lower rather than the higher figure. The fall in 1923 production which was due to inflation may thus be fairly put at about 10% of a normal year’s output at that time.
- 147If the conclusion just reached as to the effect of inflation on production in the final year of life of the old mark is justified, it follows that, so far as the total of domestic production goes, the gains from the employment of inconvertible and depreciating currency more than outweighed the losses. Counting in both the two post-inflation crises, for which inflation can with some reason be held responsible, and the falling off in production in late 1923 attendant upon the dying throes of the old currency, the reduction in output can scarcely have exceeded the benefits which inflation seems to have brought in 1921 and 1922. The decline in production due to the stabilization crises in 1924 and 1926 has been set at 10% and 5%, respectively, of a normal year’s output at that time. The decline due to the phenomena of complete currency collapse in late 1923 has just been estimated at perhaps 10% of the output which might have been realized in that year had a stable monetary standard been in operation. A rough notion of the extent of all of these losses, measured in current gold values, may be obtained from the following computation :
- 148
- 149
- 150Total losses in domestic production traceable to inflation in the years when its influence was adverse, may thus be set, in round figures, at 11 billion gold marks. These losses are much more than offset by the presumable gains from inflation in the year 1921 alone. Estimating in the same manner as above, the industrial output of the German economy in that year was raised over that of 1920 by nearly 10 billion gold marks, whereas, if a gold standard had prevailed, a sharp drop, perhaps equal to the 25% fall in industrial production which occurred in the gold standard United States or the 31% of Great Britain, would have been almost certain. If a 25% fall had occurred, the net loss, as compared with the situation which in fact eventuated, would have amounted to about 19 billion gold marks. As for 1922, it has already been pointed out that it is most improbable that production in Germany, where industrial activity was at its maximum, would have been as great under stable monetary conditions as it actually proved to be under the stimulus of currency depreciation since this was a year of but slow recovery from the depression of 1921 in all countries where prices were kept on an even keel.
- 151So far as total deposits go it would seem that operations of commercial banks had no inflationary effect except in 1922 and 1923 (up to the reform) and then only at the instigation of the Reichsbank. This assertion is based on the facts that up to 1922 total deposits, as compared with 1913, had declined in importance relative to note issues and that the increase in the ratio in 1922, and till November 1923, was presumably due to the Reichsbank’s encouragement of the rediscount of commercial bills. The index of deposits relative to total money in circulation, when expressed as a percentage of the 1913 ratio, was, for the end of the years 1920, 1921, 1922, 1923, respectively 65%, 80%, 108%, 41%. But a sizable part of the total deposits were time deposits which tended to disappear as the risk of depreciation grew. If therefore, instead of total deposits, demand deposits of the type designated “Kreditoren,” the deposits most affected by loans, are solely considered, a better picture of the action of the commercial banks in extending or reducing the scope of inflation will be obtained. Taking as a base the 1913 ratio of “Kreditoren” deposits to total money in circulation, the percentage figures for later years were as follows : 1920, 148%; 1921, 164%; 1922, 341%; 1923, 276%. It would appear, therefore, that the commercial banks extended loans throughout the period of post-war inflation considerably in excess of a proportionate relationship with the increase in the monetary base and that the relative decline in total deposits was due to the shrinkage in the value, or the withdrawal from the banks, of time moneys at interest or to the general reluctance actually to depont cash even if subject to demand draft. The increase in deposits issuing from loans was especially marked in 1922 and till stabilization in 1923, owing to the fact that rediscounting of commercial bills at the Reichsbank gave the private banks an enlarged base for extensions of credit. This increase was enough to carry upward the ratio figure for total commercial deposits. The growth in commercial bank loans took place in spite of the fact that the Reichsbank’s rediscount of commercial bills was by no means confined to banks but was also done for approved business concerns and for individuals and at a rate far below what the commercial banks were charging. The explanation lies in the fact that only a certain group of business interests enjoyed the Reichsbank’s favor and others were forced to go to the private banks. Nevertheless the commercial bills held by the Reichsbank at the end of 1922 formed nearly half of all the commercial bills in circulation in Germany at that date. In view of the fact that the central banking institution was supposed to accept only bills of the first quality it may perhaps be assumed that the remaining moiety was ineligible.
- 152So far as total deposits go it would seem that operations of commercial banks had no inflationary effect except in 1922 and 1923 (up to the reform) and then only at the instigation of the Reichsbank. This assertion is based on the facts that up to 1922 total deposits, as compared with 1913, had declined in importance relative to note issues and that the increase in the ratio in 1922, and till November 1923, was presumably due to the Reichsbank’s encouragement of the rediscount of commercial bills. The index of deposits relative to total money in circulation, when expressed as a percentage of the 1913 ratio, was, for the end of the years 1920, 1921, 1922, 1923, respectively 65%, 80%, 108%, 41%. But a sizable part of the total deposits were time deposits which tended to disappear as the risk of depreciation grew. If therefore, instead of total deposits, demand deposits of the type designated “Kreditoren,” the deposits most affected by loans, are solely considered, a better picture of the action of the commercial banks in extending or reducing the scope of inflation will be obtained. Taking as a base the 1913 ratio of “Kreditoren” deposits to total money in circulation, the percentage figures for later years were as follows : 1920, 148%; 1921, 164%; 1922, 341%; 1923, 276%. It would appear, therefore, that the commercial banks extended loans throughout the period of post-war inflation considerably in excess of a proportionate relationship with the increase in the monetary base and that the relative decline in total deposits was due to the shrinkage in the value, or the withdrawal from the banks, of time moneys at interest or to the general reluctance actually to depont cash even if subject to demand draft. The increase in deposits issuing from loans was especially marked in 1922 and till stabilization in 1923, owing to the fact that rediscounting of commercial bills at the Reichsbank gave the private banks an enlarged base for extensions of credit. This increase was enough to carry upward the ratio figure for total commercial deposits. The growth in commercial bank loans took place in spite of the fact that the Reichsbank’s rediscount of commercial bills was by no means confined to banks but was also done for approved business concerns and for individuals and at a rate far below what the commercial banks were charging. The explanation lies in the fact that only a certain group of business interests enjoyed the Reichsbank’s favor and others were forced to go to the private banks. Nevertheless the commercial bills held by the Reichsbank at the end of 1922 formed nearly half of all the commercial bills in circulation in Germany at that date. In view of the fact that the central banking institution was supposed to accept only bills of the first quality it may perhaps be assumed that the remaining moiety was ineligible.

