
Exchange, Prices, and Production in Hyper-Inflation
VII. Price Relationships under the Influence of Inflation
CHAPTER VII
PRICE RELATIONSHIPS UNDER THE INFLUENCE OF INFLATION
§ TYPES OF PRICE SPREADS
T HE fluctuating but persistently great discrepancy between the external and internal value of the mark established entirely distinct price levels for different phases of German business. Commodities directly affected by foreign prices and by the vicissitudes of exchange rates (imported commodities and, to a lesser degree, exports) tended to sell at higher prices corresponding to the small external purchasing power of the mark while the prices of other commodities were on a far lower level. The spread between the various classes of prices was even greater than that between the external and internal value of the mark since the internal value of the mark was dependent on the prices of a composite of goods which included relatively high-priced imports and exports as well as commodities wholly produced and consumed at home. The general internal price level was therefore considerably higher than that of commodities not entering in either direction into international trade, commodities which, for want of a better term, will be called domestic.
But price differences were by no means confined to goods directly affected by movements in exchange rates in contrast to those not so affected. They appeared also within the range of purely domestic commodities. In many cases this was due to governmental intervention and its consequences. It has already been noted that such intervention was of greatest importance in the realm of house rents. The rent-restriction legislation, working out its effects in a level of wages considerably below that which would otherwise have prevailed, ramified through prices in rough proportion to the share of labor in the production of the various commodities. Interference with the free play of competition thus exaggerated the disruptive influence of inflation, an influence which was in itself sufficient to provoke great deviations from any sort of symmetrical movement in the prices of different types of goods. Some idea of the range of price variations may be obtained from the tables and charts which appear below. In all cases relationships only are shown; the absolute movement of prices was too great for exposition or even comprehension.
§ THE DISPERSION OF PRICES
In order to determine the force of inflation as a price-dispersing agent an index of price dispersion was computed from the link relatives of a series of index numbers (on a 1914 base) of commodities so widely diverse in character as to form a fair cross section of the whole commodity price structure.1 The results appear in Table XV.
A glance at the table will show that the degree of dispersion varied directly with instability in the general price level but that, in the later phases of an upward swing of prices, the scope of the dispersion tended to narrow. The index of dispersion begins with a period shortly following the first large upward price movement, which culminated in March 1920, and it shows a steady decline during the period of stability in the general level of prices which then ensued. The range of dispersion increases as the general level of prices starts a second upward march in July 1921 but toward the end of this rising movement the range of dispersion again diminishes. It falls farther as stability in general prices emerges once more in the months from November 1921 to February 1922. In the period March 1922 to February 1923, a time of steady rise in the general price level yet without a very rapid acceleration in the earlier months, the index of dispersion remains substantially constant till July-August 1922, rises with the acceleration in the upward movement of the general price index till December, and then declines. This decline is accentuated during the two and a half months of general price stability consequent upon the action of the Reichsbank in support of exchange in the spring of 1923. Finally, a new augmentation in the range of price dispersion initially accompanies the last upward sweep of general prices from May 1923 onward yet again it fails to maintain its pace and drops off in September and October when the general price level was soaring to unheard of heights.
It is clear that with the initiation of an upward movement in general prices a series of lags in individual prices developed, that these lags tended quickly to disappear when stability of general prices was reached
TABLE XV
INDEX OF THE DISPERSION OF PRICES IN GERMANY; 1920-19232
on a new level, or when general prices fell, but that they were nevertheless progressively eliminated even though the general price level continued to rise. In both cases the formerly lagging commodities, once they had started to rise in price, gathered momentum. If the upward movement of other prices ceased or was reversed, the laggards continued to rise. This is, of course, to be expected. But, even though the upward movement of the former leaders showed no fatigue, the formerly lagging prices eventually rose at a still more rapid pace and the distance between the various commodities thus tended to close. This coalescence of prices in the later stages of inflation in general, and even in the later stages of each of the several phases, will be noted at several other points in the sequel.
§ PRICE CLASSIFICATION
Perhaps more significant phenomena than those which apply to prices in general may, however, be developed through a contrast of prices by groups or classes. Table XVI and Chart XV give the ratio (per cent) of the indices of various classes of prices to the index of wholesale prices in general.
Reference to Chart XV will show that the relative position of the several indices in January 1920 (the order in which they are named in Table XVI and Chart XV) was fairly well preserved throughout. The highest indices are those in which the relatively low external value of the mark was effective in raising prices, either because the foreign price must be paid or because it could be obtained for all, or at least the bulk, of the commodities included in the index in question. Such prices applied to all the items in the imported goods index, to most of those in the index of raw materials and in that of exported goods,4 and to a considerable number of those in the index of finished goods. Even in the index of domestic goods some exportable articles appear.5 The cost of living was, in the main, determined by the prices of domestically produced and consumed commodities, and, until the very end of inflation, wages were not greatly affected by the external value of the mark.
The prices of stock exchange securities were affected by the failure on the part of the public fully to realize that stocks and bonds were poles apart in the matter of the incidence of inflation, by the prevailing insecurity in the business world, and by the fact that there was much watering of the shares through new issues to stockholders at extremely low prices. A share of stock throughout the four years here under review was by no means a homogeneous thing but was usually declining in real worth, as measured by the physical assets behind it, and the index of stock prices is therefore scarcely comparable with the other indices given. It is none the less true that the prices of stocks were very much below a fair capitalization of the yields that might be expected over a long period of time. The reasons for this are, perhaps, not far to seek. Though speculation was active the funds available for purchases of stock were relatively slim. The mounting commodity prices absorbed so large a proportion of the monetary supply that relatively little was left for the working of the financial markets, and the banks were not inclined to put credits at the disposal of stock speculators.6 Further than this a purchase of company shares was a long-time investment. Measured in real values the companies were paying very small dividends. Their profits were frequently great but it did not do to hold them for distribution since they would lose much of their purchasing power in the interval between the date of earning and that of receipt by the stockholder. They were therefore ploughed back into the business. But, in a period when the rate of time preference was high, few people were ready to pay much for the possibility of indefinite future returns. The current high real rate of interest resulted in low capitalized values and the real rate, moreover, was confused with the enormous nominal rates imposed as insurance against depreciation. All these factors operated to depress the price of company shares to a remarkably low level.
TABLE XVI
INDEX NUMBERS OR WHOLESALE PRICES OF IMPORTED GOODS, OF INDUSTRIAL RAW MATERIALS, OF EXPORTED GOODS, FINISHED GOODS, DOMESTIC GOODS; RETAIL PRICES; WAGES OF UNSKILLED WORKERS, OF SKILLED WORKERS; PRICES OF STOCK EXCHANGE SECURITIES; HOUSING RENTALS; ALL EXPRESSED AS PERCENTAGES OF THE INDEX NUMBER OF GENERAL WHOLESALE PRICES; 1920-1923
(1913 = 100 in all cases)
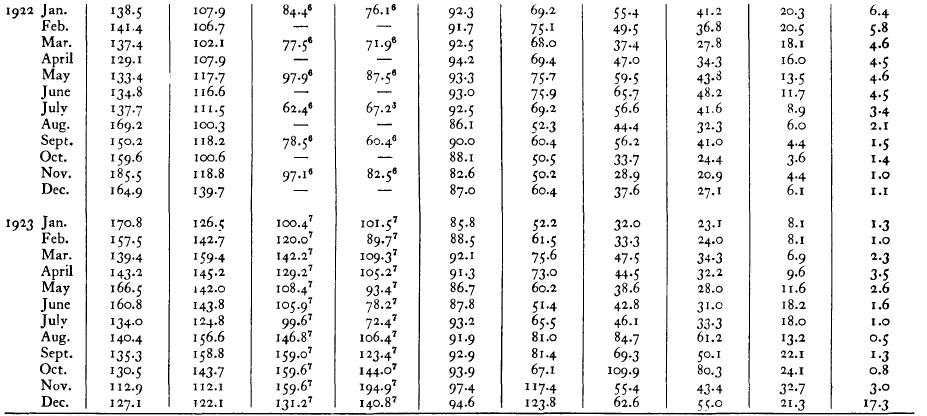
CHART XV
INDICES OF CLASSIFIED PRICES EXPRESSED AS PERCENTAGES OF THE INDEX OF GENERAL WHOLESALE PRICES; 1920-1923
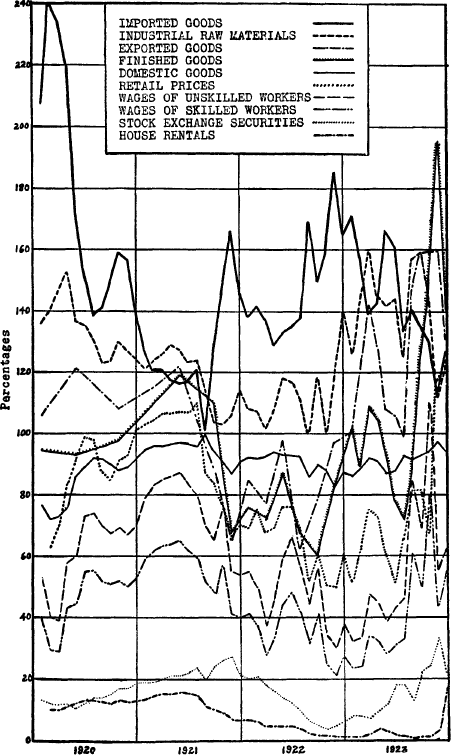
The cost of housing (rentals) has been included in Table XVI and Chart XV in order to show the effectiveness of the rent-restriction laws. In comparing the wage and retail price (cost-of-living) curves it should be noted that the latter does not include housing. The total cost of living was therefore much less in advance of wages than the retail price curve suggests. The matter will be more fully treated later in this chapter.
In the immediately succeeding pages the relation between certain of those classes of prices the curves of which have just been presented will be examined in detail. The base on which the ratios are computed has, however, been shifted from the index of wholesale prices to that of the external value of the mark, since, in an examination of correlations, it seemed best to have a base which was not itself affected by changes in any one of the indices for which it was being used as a measuring rod. General wholesale prices would be influenced, in some measure, by a change in any one of the groups of classified commodity prices and the percentage relationship between the price index of the group in question and that of wholesale prices in general would therefore not accurately reflect the real alteration in the aforesaid group index. The external value of the mark, on the other hand, would be unaffected, at least directly, by a change in any internal price index.
The relationship between the several classes of prices will be treated by grouping them according to a principle of presumed intimacy of movement as follows: (1) prices of import, of export, and of domestic commodities, (2) prices of imported commodities, of industrial raw materials, and of finished goods, (3) wholesale and retail prices, (4) wages and the cost of living.
1. PRICES OF IMPORT, EXPORT, AND DOMESTIC COMMODITIES
§ GENERAL RELATIONSHIP BETWEEN SUCH PRICES
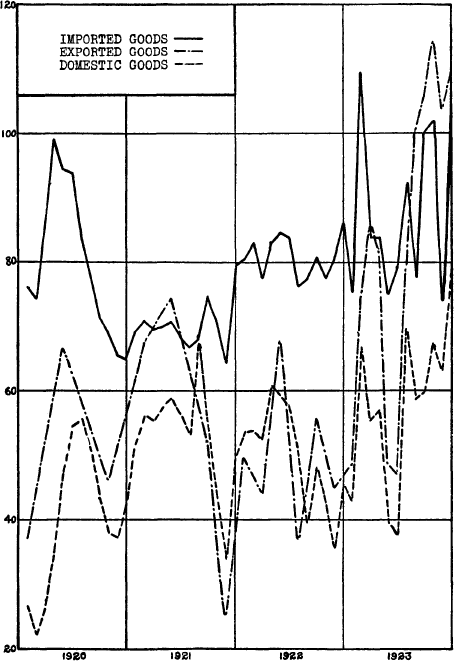
Table XVII and Chart XVI present for the period 1920 to 1923 the relations between the ratio indices of three groups of wholesale prices representative of import, export, and domestic commodities respectively.
The price index of each of the groups here shown is expressed as a percentage of the synchronous index of external mark prices. All indices are on a 1913 base. The curves thus show the number of paper marks which at any given date must have been paid for a given quantum of typical import, export, and domestic goods in percentage relationship to the number of paper marks which would have been required, at the date in question, to purchase a given quantum of foreign goods in general.10 Data are not available for the construction of a complete index of exported goods and the index of prices of machinery has therefore been taken as typical of German exports. The two other indices have rather narrow bases, the index of imported goods including but sixteen items and that of domestic goods, eighteen. The domestic goods index, moreover, is comprised, in part, of commodities occasionally or even steadily exported. Raw materials of industry and foodstuffs dominate both the indices of import and domestic commodities. The figures are therefore at most representative of the relations between the groups of prices affected; no claim that they are precise criteria can be made. But whatever their defects, they are, it is submitted, the best to be had, and even if they will not show refinements they are capable of giving a fair impression of the broad differences which prevailed between these several price groups.
TABLE XVII
INDEX NUMBERS OF WHOLESALE PRICES OF IMPORTED GOODS, EXPORTED GOODS (MACHINERY), AND DOMESTIC GOODS, EXPRESSED AS PERCENTAGES OF THE INDEX OF EXTERNAL PRICES; 1920—1923
(Monthly averages)
Source of data: Zahlen zur Geldentwertung in Deutschland 1914 bis 1923, passim.
§ IMPORT PRICES
It is at first blush surprising that the index of prices of imported goods does not more nearly approach 100% of the index of external prices in general. In the first half of 1920 it did come close to par but it then fell to a low of 65% in December of that year. Throughout most of 1921 it fluctuated between 65% and 75% of par; it then reached a norm of about 80% which was maintained pretty steadily throughout 1922 and, with occasional great upward flurries, in 1923. The question arises as to why the mark prices of imported goods should have been rather consistently below a true correspondence with the purchasing power of the German currency over foreign goods in general. Several explanations suggest themselves:
CHART XVI
INDICES OF IMPORT, EXPORT, AND DOMESTIC COMMODITY PRICES EXPRESSED AS PERCENTAGES OF THE INDEX OF EXTERNAL PRICES; 1920-1923
(1) The prices of goods which are included in the index were not as high in foreign markets relative to their 1913 level as were foreign goods in general. The bulk of Germany’s imports are foodstuffs and industrial raw materials. With the world-wide collapse of the post-war boom in 1920 the prices of these commodities quite generally fell farther than the prices of manufactured goods. This explains the sudden drop, in the summer of 1920, in the ratio of the prices of imported goods to the external value of the mark. Furthermore, Germany imports in part from countries which, in the period under consideration, were undergoing monetary experiences similar to her own. The exports of these countries (German imports) would perhaps tend to be low in price when measured in the gold currency of the United States here used as the base for computation.
(2) German import tariffs, measured in gold, tended to fall as a result of inflation. As early as 1919 customs duties were put on a gold basis by means of a surcharge roughly corresponding to the depreciation of the currency.11 But there was, nevertheless, a lag of the surcharge rates behind the actual depreciation of the currency and this kept the prices of imports in the internal markets somewhat below a proportionate relationship with the fall in the external value of the mark.
(3) The handling of the goods after their purchase abroad, but before their inclusion in the German wholesale price index, was done at a cheaper rate relative to their cost in the country of export than had been the case in the base year 1913. This was but one aspect of the low domestic price level.
(4) The quality of the goods imported had probably declined. The index is thus defective inasmuch as it does not compare strictly identical commodities.
(5) In 1920 and 1921 a sizable portion of the imports were invoiced in marks. A rise in foreign exchange between the date of order and of payment would then have no effect on the cost to the importer. This may account for the low status of the ratio from the middle of 1920 till the close of 1921.
§ GENERAL RELATIONSHIP BETWEEN IMPORT, EXPORT, AND DOMESTIC COMMODITY PRICES
Contrasting the relationship between the curves it will be noted that an intermediate position of the index of exports is, in general, maintained.12 This is in accord with theoretical expectation. When the value of a currency is relatively depressed on the exchange markets—presumptive evidence that the volume of imports is too high relative to that of exports—equilibrium tends to be attained through the establishment of the following price scheme. All domestic commodities, both those exported and those consumed at home, become low in price in comparison with the price of imports, but the prices of exportable goods become high relative to those of commodities which find their market solely within the country. The volume of exports is thus expanded both by the diminution in their home consumption and by the transfer of production from the relatively unprofitable non-exportable goods to lines capable of sale outside the country. The mechanism of this price adjustment under inconvertible paper conditions is entirely contained in the exchange rate movement itself. The price of imports is normally established in foreign markets and increases pari passu with a rise in the cost of foreign exchange.13 The prices of commodities produced and consumed at home are directly affected neither by the prices prevailing in foreign markets nor by the exchange rate. The prices of exports are affected, on the demand side, by foreign monetary conditions and by exchange rates while, on the supply side, the domestic situation is determinative. They therefore tend to assume an intermediate position below those of commodities produced abroad but above those of commodities produced and consumed at home. It should perhaps be repeated that the prices here given for exports represent only the inland prices of exportable goods. Actual prices to foreigners were arbitrarily fixed above the domestic, but below the foreign, level by the Boards of Foreign Trade Control.14 If the prices actually charged could be ascertained, they would no doubt lift the curve of export prices considerably above its present status although its intermediate position would almost certainly be maintained.
The ratio of exports to imports was, it seems, increased sufficiently to procure equilibrium in international debits and credits only through a huge price differential. The influence of cash reparations payments in leading to price movements essential to the relative expansion of exports in the measure required to cover the increased debits is, moreover, clearly evident. By the fore part of 1921 export prices had reached parity with those of imports. During the whole period of cash reparations payments (May 1921 to the end of 1922) they were far below. In 1923, when cash reparations had been suspended, the prices of exports again attained the level of imports and even went considerably beyond it.
Had not the Boards of Foreign Trade Control arbitrarily raised the prices charged to foreign buyers the relatively very low price of exportable goods in the domestic market in 1921 and 1922 would have required almost twice the quantum of exports to pay for a given volume of imports that was necessary before cash payments on reparations began. In other words, assuming a given volume of imports, exports would have had to have been doubled in volume before any foreign exchange whatever would have accrued to the Germans with which to meet their reparations obligations. Since a rapid doubling of exports is out of the question, the situation, if allowed to run uncontrolled, would have become persistently worse. At this stage a discrimination in the prices charged foreign buyers would seem to have been indispensable if the exhaustion of the country of all exportable goods, at prices which would have produced less foreign exchange than could be secured through a much smaller physical volume of export at controlled prices, was to be prevented. At other stages the control of foreign trade may have been nothing but a nuisance but at this time the evidence of its potential usefulness is clear.
While the prices of exportable goods were low to foreign buyers, their prices in domestic markets, to say nothing of the supplements obtained on actual exports, were high enough to put the producers of these goods in a peculiarly favorable position, especially when foreign exchange was rising. Costs were presumably no greater than those of producers of goods for domestic consumption and the price differential was, therefore, pure gain. The greatest gain accrued to exporters working up domestic materials. Both their labor and material costs were then paid at the low internal price level while their goods were sold at the high prices, in marks, which issued out of the relative depreciation of the German currency on the exchange markets. Exporters of goods made up of imported raw materials were not quite so well off but were nevertheless in a position to make large gains on the difference between their labor costs and their selling price. Importers, and the producers of domestically consumed commodities, shared about the same status of relative disadvantage. Importers obtained high prices for their commodities but had to pay correspondingly high prices to obtain them. Producers of domestically consumed commodities sold at relatively low prices but their costs were on the same level. The favored position was confined, in general, to exporters and was improved in proportion to the degree of independence of foreign raw materials in the manufacture of their products. The distribution of profits taken as a whole was therefore very uneven.
§ POINT-TO-POINT RELATIONSHIP OF IMPORT, EXPORT, AND DOMESTIC PRICES
The shape of each of the three price curves shown in Chart XVI is, in general, similar, though that of imported goods fluctuates much less widely than the others. The latter is to be expected. If adjustment of import prices to current replacement costs had been immediate and perfect, the curve of import prices would be a straight transverse parallel keeping a fixed relationship with the index of the external purchasing power of the mark, though, for reasons already stated, it might have been below the 100% line. The adjustment was, in fact, by no means immediate or perfect but there is nevertheless a tendency toward relative flatness in this curve. In the others the adjustment was less rapid and complete and the fluctuations are therefore wider. Since all German prices were rather consistently rising, and since foreign (gold) prices were substantially stable, the upward movements in the curves tend to occur when foreign (dollar) exchange rates fell, or when they rose less than general internal prices, while the downward movements normally come at times when foreign exchange rose in greater degree than such prices. The range of fluctuation in all the curves is affected by exchange movements in inverse proportion to the rapidity and closeness of correspondence of the several groups with the variations in exchange.
Though there was a lag of export and domestic commodity prices behind those of imports, in the sense that the prices of the former groups remained persistently lower than those of imports,15 and though the greater range of fluctuation in export and domestic prices indicates a less immediate response to the changing external purchasing power of the mark, a chronological lag is nevertheless not obvious in the month-to-month fluctuations. In their broad movements, import and export prices show a substantial simultaneity, and though, in 1920, domestic commodity prices appear to follow those of the other indices at an interval of a month or two, there is no evidence of any such hesitation after that date. In so far as the movements in the curves are due to such fluctuations in the base as are solely attributable to a shift in exchange rates there would be simultaneity of movement in the curves when all -commodity prices were inert. But when they are due, as is frequently the case, to an upward movement of prices in greater or less degree than a concurrent change in foreign exchange in the same direction, a lag in the export, and, a fortiori, in the domestic price curves, might be expected. Fundamentally the effect on domestic prices of changing import and export prices would seem to depend on a diminution in the supply of domestic goods arising from the shifting of industry to the production of goods for export. This would be a matter of months. Since any lag there may have been was certainly not as great as this, price adjustments must have been occasioned by a shift in demand rather than in supply. Demand appears to have been so quickly diverted to the relatively cheap goods that prices of all moved almost synchronously. The lesser range of fluctuation in the imported goods curve shows, however, that there was some lag in the others. Changes in the external purchasing power of the mark seem to have resulted in almost immediate, though not quite proportionate, changes in the prices of imported goods, while the movement of prices of other commodities was slightly less prompt.
The lag in the response of export and domestic commodity prices is evidenced by the relatively violent movement in the ratio curves of these prices. An extreme movement in one direction was generally followed by an equally extreme movement in the other. If the ratio indices of the prices of domestic or export commodities fell in any given month, owing to the fact that these prices had remained relatively unchanged while foreign exchange had risen, they ordinarily did not stay down for more than that single month. Either foreign exchange fell or domestic and export prices rose—the latter was usually the case—until practically the old relationship was restored. A flat curve means immediate adjustment to the external value of the mark, a curve of violent fluctuations and sharp peaks means a lag of less than a month, and a curve of violent fluctuations and rounded peaks a somewhat longer lag. The latter are conspicuous by their absence.
§ SEQUENCE OF MOVEMENT IN IMPORT, EXPORT, AND DOMESTIC PRICES
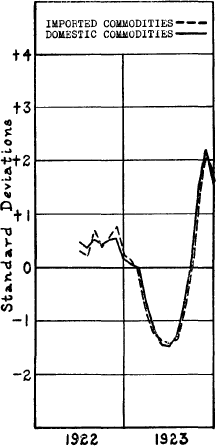
In order to test more thoroughly the sequence of movement in the prices of imported and domestic commodities16 trend lines were fitted to the wholesale price index numbers of these classes of commodities, covering the months June 1918 to December 1923, and cycles of deviation from these trends were charted.17 It was necessary to divide the series into two periods since the extreme rise in the indices in the final year and a half of inflation made it impracticable to fit any single curve to the whole series. The first period runs from June 1918 to June 1922 inclusive and the second from June 1922 to December 1923 inclusive. A compound-interest trend gives a fairly good fit for the former period while a compound-interest trend fitted to the logarithms of the original data was chosen for the second. Cycles were measured as percentage deviations from the trends; for the period June 1918 to June 1922 percentage deviations of the original items, and for the period June 1922 to December 1923 percentage deviations of the logarithms of the original items. These percentage deviations for each series were then expressed in terms of the respective standard deviations. The resulting Charts XVII and XVIII present the cycles for each series.
In order to calculate correlation coefficients the figures for the cycles18 were multiplied together month by month, the products added, and the sum divided by the number of products.19 The following coefficients of correlation were obtained :
CORRELATION OF CYCLES IN THE WHOLESALE PRICES OF DOMESTIC AND OF IMPORTED GOODS
| Period June 1918—June 1922 | Coefficient of Correlation |
Probable error of r |
| With simultaneous items . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . | r = + .776 ± .038 | |
| With one month lag of prices of domestic good20 . . . | r = + .786 ± .037 | |
| With two months lag of prices of domestic goods . . . | r = + .723 ± .047 | |
| With one month lag of prices of imported goods . . . | r = + .681 ± .052 | |
CHART XVII
CYCLES IN THE MOVEMENTS OF PRICES OF IMPORTED AND OF DOMESTIC COMMODITIES; JUNE 1918-JUNE 1922
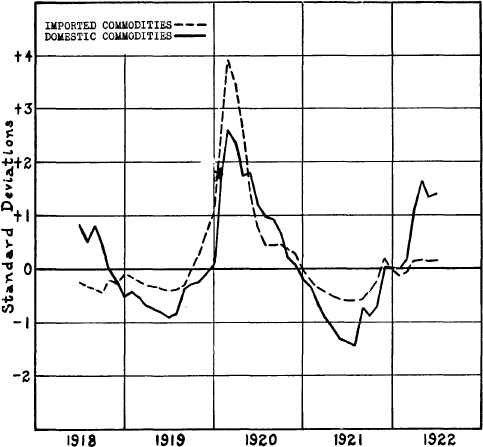
CHART XVIII
CYCLES IN THE MOVEMENTS OF PRICES OF IMPORTED AND OF DOMESTIC COMMODITIES; JUNE 1922-DECEMBER 1923
| Period June 1922—December 1923 | Coefficient of Correlation |
Probable error of r |
| With simultaneous items . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . | r = + .994 ± .002 | |
| With one month lag of prices of domestic good. . . | r = + .831 ± .049 | |
| With two months lag of prices of domestic goods . . . | r = + .850 ± .044 | |
For the period June 1918 to June 1922 the results are not very conclusive but they perhaps suggest a slight lag in domestic prices. It is even possible that they indicate an alternation of cause and effect. If exchange rates persistently dominated internal prices the movements in the prices of imported goods might be expected to precede those of domestic commodities. If, on the other hand, internal prices persistently dominated exchange rates the movements in the prices of domestic commodities might be expected to precede those of imported goods. If either of the two were persistently dominant a perfect lagging correlation would thus be possible. If there was alternation, with exchange rates generally dominant in sub-periods of disturbance and prices dominant in sub-periods of quiescence, then, on the erroneous assumption that either was dominant throughout, there would be a possibility, during any given sub-period, of a perfect lagging correlation, and, in the succeeding sub-period, a possibility of some correlation provided the general movement of the cycles was parallel. Over the whole period a considerable measure of correlation might consequently develop. The trendy however, was chiefly determined by a cause acting on both curves, viz. the extent of general inflation. The evidence of alternation is therefore meager and it is not much greater in support of the assumption that import prices were normally dominant. The most that can be said is that there is still less reason to suppose that prices of domestic commodities took the lead.
In the period June 1922 to December 1923 it is clear that any lag in either direction which may have been present up to mid-1922 was greatly cut down or even completely eliminated. This is but another phase of the tendency for all the phenomena of inflation to move simultaneously in the closing months of currency depreciation.
§ RESULTS OF THE SEQUENCE OF PRICE MOVEMENTS IN IMPORT, EXPORT, AND DOMESTIC COMMODITIES
Any tendency for the prices of domestic products to lag in time as well as in degree must have placed the producers of those products in a still less favorable position than was theirs by reason of the relatively low status of domestic prices. Owing to rapid price adjustment the paper profits of sellers of imported goods were no doubt large enough to yield a real gain after their stock had been replaced, even though costs moved upward somewhat in advance of selling prices. It seems even more probable that prices on exports moved fast enough to give to the producers of exportable commodities, whose costs did not rise so rapidly, still larger profits than were inherent in the generally high relative prices of the commodities they were selling.21 But producers of domestic commodities were not only forced to sell at relatively low prices but those prices changed but shortly in advance of costs. If the general movement of exchange rates and prices had been neither up nor down, if fluctuations had been about a level norm, producers of domestic commodities would have been in a relatively favorable position on downward fluctuations. In fact, however, they had but few compensations of this sort. The upward surge of prices was sometimes checked but, in no large measure, reversed. It is not, indeed, to be supposed that the producers of domestic commodities bore the brunt of inflation, which did not fall on the entrepreneurial class at all, but merely that they did not have the same opportunity for gain as did their confreres in other industrial or mercantile pursuits.
2. PRICES OF IMPORTED COMMODITIES, INDUSTRIAL RAW MATERIALS, AND FINISHED GOODS
§ GENERAL RELATIONSHIP BETWEEN SUCH PRICES
Table XVIII and Chart XIX show the relationship between the prices of imported goods, industrial raw materials, and finished goods, all expressed as percentages of external prices in marks. It will be seen that, until the final month of inflation, the prices of industrial raw materials ran consistently above those of finished goods. Reference to Chart XV will also show that prices of raw materials were generally higher even than those of typical exportable goods (machinery). The standardized quality of raw materials, and the nature of their market, make large price differentials, as between one country and another,22 unlikely to occur under any currency system whatever. There is no sales resistance in custom, and little inertia of any kind, to be overcome. Raw materials have a world market and a world price in a sense which does not at all apply to finished goods. Nothing but rigid control of exports or imports can long keep their prices in any given market widely divergent from their value abroad.23 In spite of the restricted export of raw materials which prevailed in Germany the activity of the Boards of Foreign Trade Control in fixing raw material prices to foreign buyers at something approaching the world level was sufficient to lift raw material prices in the domestic market considerably above those obtaining for most other goods. The sale of these other goods was entirely dependent entirely dependent on domestic demand or was conditioned by the fact that the quality of the goods, and therefore the advantage to a foreign buyer at the prices quoted, was by no means obvious. The prices of raw materials thus kept considerably closer to those of imported articles than did the prices of finished wares.
TABLE XVIII
INDEX NUMBERS OF WHOLESALE PRICES OF IMPORTED GOODS, INDUSTRIAL RAW MATERIALS, AND FINISHED GOODS, EXPRESSED AS PERCENTAGES OF THE INDEX OF EXTERNAL PRICES; 1920-1923
(Monthly averages)
Source of data: Zahlen zur Geldentwertung in Deutschland 1914 bis 1923, passim.
CHART XIX
INDICES OF PRICES OF IMPORTED GOODS, INDUSTRIAL RAW MATERIALS, AND FINISHED GOODS EXPRESSED AS PERCENTAGES OF THE INDEX OF EXTERNAL PRICES; 1920-1923
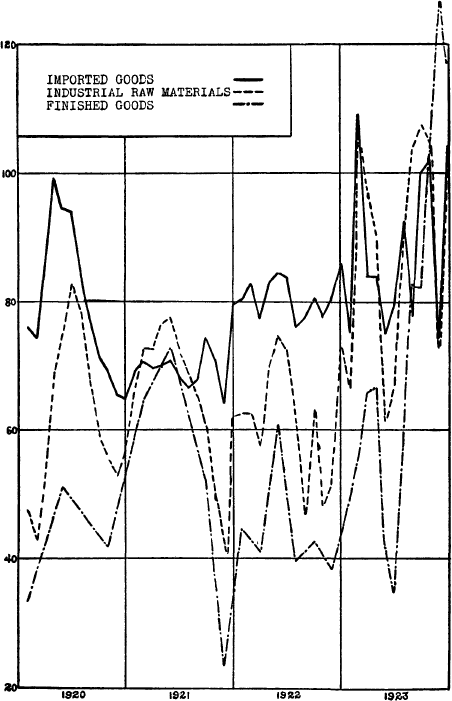
It should be noted, however, that the index of raw materials contains several imported commodities and that this accounts, in part, for the high position of this index relative to that of finished goods. The export of raw materials from post-war Germany was confined to a rather narrow range of commodities. The domestic producer of such materials may have secured a clear advantage over the producer of finished goods but the double gain of securing a high domestic price and a still larger price on export was realized in only a limited degree. Furthermore, the domestic prices of some important raw materials produced in Germany, such as coal and iron, were not substantially higher than those of finished goods, and coal was subject to a heavy tax. The relative gains obtained by the producers of raw materials were therefore not universal.
The general relationship between the prices of raw materials and finished goods on the one hand, and those of imports on the other, is much the same as that of export and domestic commodity prices relative to those of imports. The hunger for imports in 1920, the consequent low exchange value of the mark and high prices of imports, was succeeded by substantial equilibrium in early 1921. All the price indices then tended to coalesce. The equilibrium was disturbed by the break in exchange rates after May 1921 and was not again approached till the final stages of inflation. The raw materials index, so far as it was in-fluenced by domestic commodities, was depressed in mid-1921 by the general relative lowering of domestic prices, and the finished goods index suffered a still greater relative decline. When the pressure of foreign obligations was removed in 1923 the tendency was again toward parity in all three curves. There is, however, a difference in the method by which parity was attained in the first half of 1921 and in the latter half of 1923. In the earlier period it was due to an absolute decline in the mark prices of imports (consequent upon a fall in foreign exchange) while other prices remained substantially stable. In the latter half of 1923 it occurred because the prices of imported goods, while rising at a tremendous rate, could not match the precipitous climb of the other indices. The relative immobility of certain prices in 1921 had completely disappeared in the later period. Price changes in 1923 might or might not conform to changes in external purchasing power but this was not due to any sluggishness in price movements.
Since the index of raw materials contains imported commodities, and the index of finished goods contains exported articles, the probability of being able to draw any significant inferences from such lags in the movements of the several curves as might develop from a correlation of cycles of deviation would seem to be too small to warrant the labor involved. Any tendency for the movements of prices of domestic commodities to lag behind those of imports and exports would conflict with a possible tendency for the movements of prices of finished goods to lag behind those of raw materials. Cycles of deviation for the indices of prices of raw materials and finished commodities have therefore not been worked out.
3. WHOLESALE AND RETAIL PRICES
§ GENERAL RELATIONSHIP BETWEEN WHOLESALE AND RETAIL PRICES
The relationship between wholesale and retail prices (each index expressed as a percentage of the index of external prices in marks) is shown in Table XIX and Chart XX.
The index of wholesale prices is the “all commodity” index while the cost of living (exclusive of housing) has been taken as the most appropriate index of retail prices. The most striking aspect of the curves is the tendency for the retail index to be above that of wholesale prices in the first half of 1921 and below it before and after that date.24 This is in accordance with the well known relative inertia of retail prices. The absolute trend of wholesale prices was upward till January 1921; for the next six months it was, on the whole, slightly downward; from then on it was rapidly upward once more.25 Retail prices lagged behind wholesale on all of these movements and so appear above those of wholesale in the fore part of 1921 when wholesale prices were falling. During 1922 and most of 1923 there is a rather close parallelism in the curves. They moved in similar fashion but at a distance from one another. This would seem to have been due to the fact that the principal element in the spread between retail and wholesale prices is the wage bill. The index of wages was consistently on a lower scale than commodity prices either at wholesale or retail.26 The low rate of wages was consequent upon lower general productivity than in the base year, 1913, and upon housing legislation, as well as upon the normal lagging tendency of wages when prices are in flux. The prices of all domestically produced commodities were affected by low wages but those in which the labor element was relatively important were affected most. These were retail prices. The comparatively low position of retail prices in 1922 and 1923 was probably therefore not primarily due to a lag which would ultimately have tended to disappear had prices steadied, but to a difference in costs which would tend to be permanent so long as conditions affecting either the wholesale or retail index, or both indices in unequal degree, such as wages, remained unlike those prevailing in the base year. This conclusion is confirmed by the fact that in late 1923, when the ratio index of retail prices once more advanced beyond that of wholesale, wages had already shown a corresponding rise.
198 HYPER-INFLATION: GERMANY, 1920-1923
TABLE XIX
INDEX NUMBERS OF GENERAL WHOLESALE AND RETAIL PRICES EXPRESSED AS PERCENTAGES OF THE INDEX OF EXTERNAL PRICES; 1920-1923
(Monthly averages)
Source of data: Zahlen zur Geldentwertung in Deutschland 1914 bis 1923, passim.
CHART XX
INDICES OF WHOLESALE AND RETAIL PRICES EXPRESSED AS PERCENTAGES OF THE INDEX OF EXTERNAL PRICES; 1920-1923
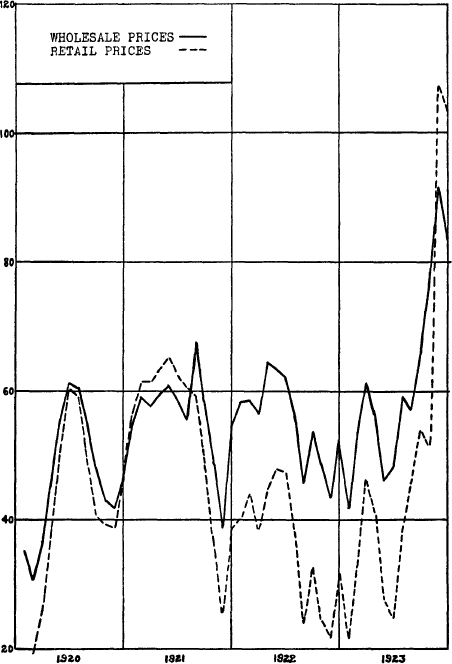
There is nothing in the charts to indicate that the movement of retail prices, in the later years at any rate, was more sluggish than that of wholesale. In order properly to trace various types of correlation it would seem to be necessary, in general, to distinguish three separate types of lag. There is the lag in amplitude and there are two sorts of lags in timing, a lag for the whole duration of a trend in any one direction and a point-to-point lag. If wages should move more slowly than prices in general, and if wages play a more important part in retail than in wholesale prices, retail prices might be expected to show a trend lag, with respect to wholesale, as prices in general moved in any one direction. But the point-to-point movements within a trend might show no such lag in timing and they might even reverse it. If, for instance, increased monetary purchasing power is first directed toward consumers’ goods, retail prices might, not improbably, show a point-to-point movement in advance of those at wholesale, though, as a result of other causes such as the lag in wages, their variations would appear on a chart from which trends had not been eliminated, persistently to the right of the wholesale price curve.
§ SEQUENCE OF MOVEMENTS IN WHOLESALE AND RETAIL PRICES
In Chart XXI the cycles of deviation of general wholesale and retail prices from their respective trends are given. The index of retail prices (cost of living exclusive of housing) is not quoted till February 1920. Yet, in order satisfactorily to measure trends, it was necessary to break up into three periods the four years covered by this index. The periods are: February 1920 through May 1921, May 1921 through June 1922, and June 1922 through December 1923. The series for wholesale prices was similarly divided. For the first period a compound-interest trend gave a fairly good fit for the wholesale price index while a straight line proved better for the retail. In the second period a compound-interest trend was again satisfactory for the wholesale index while a parabolic curve27 gave the best results for the retail. In the third period a compound-interest trend was fitted to the logarithms of the original items of both indices. The calculation of the cyclical fluctuations and of the correlation coefficients was carried out in the manner already described in connection with the comparison of the prices of imported and domestic goods.
It is doubtful whether significant results can be obtained from periods so short as were necessary for the fitting of trend lines in these cases and the movement of the curves in the middle period, May 1921 through June 1922, is peculiar, a fact upon which more detailed comment will presently be made.
CHART XXI
CYCLES IN THE MOVEMENTS OF WHOLESALE AND RETAIL PRICES; 1920-1923
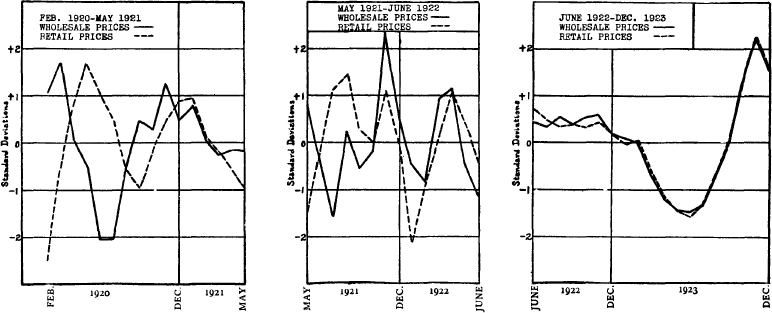
For the period February 1920 through May 1921 a lag of retail prices of about two months seems clear. The coefficients of correlation, with varying lags, are as follows:
CORRELATION OF CYCLES IN WHOLESALE AND RETAIL PRICES
Period February 1920—May 1921
| Coefficient of Correlation |
Probable error of r |
|
| With simultaneous items . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . | r = + .369 ± .146 | |
| With one month lag of retail prices . . . . . . . . . . . . . . . . | r = + .201 ± .167 | |
| With two months lag of retail prices . . . . . . . . . . . . . . . . | r = + .621 ± .111 | |
| With three months lag of retail prices . . . . . . . . . . . . . . . . | r = + .496 ± .141 | |
| With four months lag of retail prices . . . . . . . . . . . . . . . . | r = + .065 ± .194 | |
Period May 1921—June 1922
| Coefficient of Correlation |
Probable error of r |
|
| With simultaneous items . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . | r = + .227 ± .171 | |
| With one month lag of retail prices . . . . . . . . . . . . . . . . | r = + .175 ± .181 | |
| With two months lag of retail prices . . . . . . . . . . . . . . . . | r = + .615 ± .121 | |
| With three months lag of retail prices . . . . . . . . . . . . . . . . | r = + .156 ± .198 | |
| With four months lag of retail prices . . . . . . . . . . . . . . . . | r = + .079 ± .212 | |
There is no evidence here of any direct correlation at all in the movements of the two groups of prices in the second period. It seems improbable that, if there was a lag in the movement of retail prices up to May 1921, the tendency would be completely eliminated in the period May 1921 to June 1922 when the general simultaneity in the movements of all prices had not yet set in. For some reason wholesale and retail prices in this period simply did not move in any discernible relationship with one another. This is, however, not very surprising in view of the fact that the period covered, with monthly data only, is little more than a single year.
Period June 1922—December 1923
| Coefficient of Correlation |
Probable error of r |
|
| With simultaneous items . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . | r = + .990 ± .003 | |
| With one month lag of retail prices . . . . . . . . . . . . . . . . | r = + .842 ± .046 | |
| With two months lag of retail prices . . . . . . . . . . . . . . . . | r = + .833 ± .050 | |
Here, as in other cases at this stage of inflation, any lag that up to this time may have been present in retail prices tended to disappear or, at any rate, to be reduced to less than a single month’s duration.
4. WAGES AND THE COST OF LIVING
§ GENERAL RELATIONSHIP BETWEEN WAGES AND COST OF LIVING
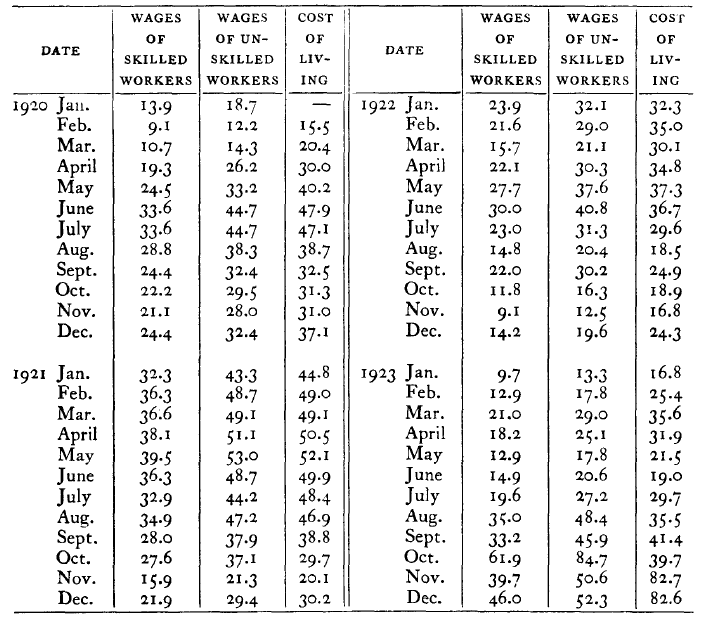
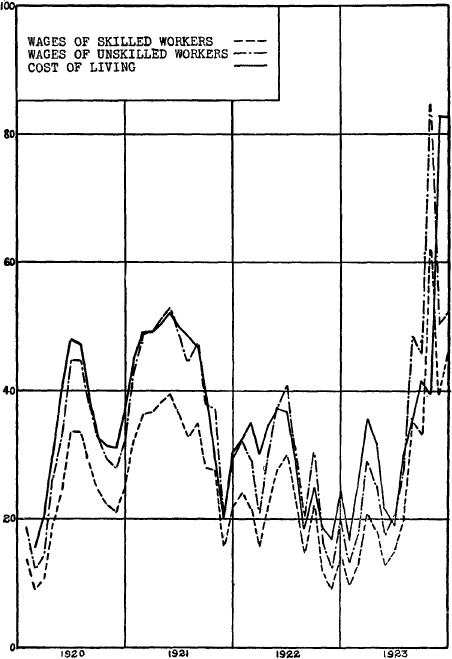
Finally, it seemed worth while to examine in detail the relationship between wages and the cost of living. Table XX and Chart XXII show the ratio of wages of skilled and unskilled workers and of cost of living (including housing) to external prices in marks.
TABLE XX
INDEX NUMBERS OF WAGES OF SKILLED AND UNSKILLED WORKERS, AND OF COST OF LIVING, EXPRESSED AS PERCENTAGES OF THE INDEX OF EXTERNAL PRICES; 1920-1923
(Monthly averagess)
Source of data: Zahlen zur Geldentwertung in Deutschland 1914 bis 1923, passim.
The similarity in the shape of the curves suggests that the response of the three indices to changes in the external purchasing power of the mark was about equal, and the curves also indicate that, in the first two years and a half of the period depicted, the response was rather slow.28 Exchange rate movements, in themselves, do not appear, during these two and a half years, greatly to have affected wages or the worker’s cost of living. It should be noted that the composition of the cost-of-living index was changed in 1920, and thereafter includes a group of commodities which, in that year, could be obtained relatively cheaply. Wages were thus not as high relative to the 1913 list of commodities in the then cost-of-living index as Table XX and Chart XXII seem to indicate. There is, however, in the relationship between the curves of wages of unskilled labor and that of the revised cost of living, an interesting analogue to the operation of the old iron law of wages. Unskilled workers’ wages in 1920 appear to have been down close to the minimum of subsistence and the amplitude lag between such wages and the reduced cost-of-living index was never thereafter great, however rapid the rate of currency depreciation might be. The adjustment of unskilled wages to the rising monetary cost of living from 1920 onward was necessarily quick and close. In the case of skilled workers, on the other hand, where there had been a margin of safety, a large reduction in real wages was persistently maintained; the margin of safety was wellnigh eliminated and the absolute level of real wages of skilled workers fell to a point not much above that of the unskilled group.
CHART XXII
INDICES OF WAGES OF SKILLED AND UNSKILLED WORKERS, AND OF COST OF LIVING, EXPRESSED AS PERCENTAGES OF THE INDEX OF EXTERNAL PRICES; 1920-1923
§ SEQUENCE OF MOVEMENTS IN WAGES AND THE COST OF LIVING
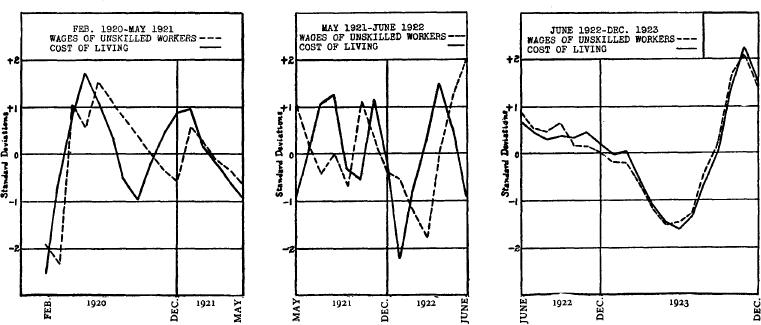
To test the response of wages to cost of living, or vice versa as the case might be, cyclical fluctuations in the deviations of the curves of wages of unskilled workers and of cost of living (including housing) from their respective trends were calculated. The data used were the simple index numbers of unskilled workers’ wages and of cost of living and they were divided into the same three periods as those of wholesale and retail prices. Straight-line trends were fitted to the data of the first period, a compound-interest trend for wages and a parabolic trend for cost of living in the second, while compound-interest trends were fitted to logarithms of the original data in the third. Cyclical fluctuations and correlation coefficients were computed in the same manner as for the previous comparisons. The cycles of deviation are shown in Chart XXIII.
There is fairly clear evidence of a lag in the movements of wages of approximately one month in the period February 1920 to May 1921. The correlation coefficients are:
CHART XXIII
CYCLES IN THE MOVEMENTS OF THE WAGES OF UNSKILLED WORKERS AND OF COST OF LIVING; 1920-1923
CORRELATION OF CYCLES IN WAGES AND THE COST OF LIVING
| Period February 1920—May 1921 | Coefficient of Correlation |
Probable error of r |
| With simultaneous items . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . | r = + .627 ± .102 | |
| With one month lag of wages . . . . . . . . . . . . . . . . | r = + .700 ± .089 | |
| With two months lag of wages . . . . . . . . . . . . . . . . | r = + .144 ± .177 | |
| With one months lag of cost of living . . . . . . . . . . . . . . . . | r = + .031 ± .174 | |
| With two months lag of cost of living . . . . . . . . . . . . . . . . | r = + .471 ± .140 | |
In the second period, May 1921 to June 1922, the curves of cycles of deviation are of roughly similar shape but examination of the charts suggests that wage movements preceded those of the cost of living in the second half of 1921 while in 1922 they appear to have succeeded them. Correlation coefficients for the whole period, however, are as follows :
| Period May 1921—June 1922 | Coefficient of Correlation |
Probable error of r |
| With simultaneous items . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . | r = + .066 ± .179 | |
| With one month lag of wages . . . . . . . . . . . . . . . . | r = + .359 ± .163 | |
| With two months lag of wages . . . . . . . . . . . . . . . . | r = + .658 ± .110 | |
| With three months lag of wages . . . . . . . . . . . . . . . . | r = + .035 ± .203 | |
| With one months lag of cost of living . . . . . . . . . . . . . . . . | r = + .090 ± .186 | |
| With two months lag of cost of living . . . . . . . . . . . . . . . . | r = + .205 ± .187 | |
It is of course possible that, with increasing flexibility in all price phenomena, interaction between the movements of wages and those in the cost of living may have occurred, wages tending to affect the cost of living and the cost of living to affect wages. The causal sequence which consistently holds in the early stages of inflation is not necessarily, or even normally, maintained as currency depreciation becomes forseeable, and resistance in any of the phases of the price structure weakens. But, if there was this type of interaction between two forces, it would seem to make for approximate simultaneity in the month-to-month movements of the indices, such as developed in all the series from the middle of 1922 onward, rather than in an alternation of the dominant and recessive roles. It seems unlikely, too, that wages should lag more in the second than in the first period, though the correlation coefficients carry this suggestion. The cycles of deviation of the indices of wages and cost of living in this second period must therefore be regarded as having been peculiar and not subject to any discernible law.
In the period June 1922 to December 1923, the high degree of simultaneous correlation, typical of all price phenomena in this final stage of currency collapse, appears. Correlation coefficients are:
| Period June 1922—December 1923 | Coefficient of Correlation |
Probable error of r |
| With simultaneous items . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . | r = + .985 ± .005 | |
| With one month lag of wages . . . . . . . . . . . . . . . . | r = + .777 ± .063 | |
§ SOCIAL SIGNIFICANCE OF PRICE VARIATIONS
Certain classes of the population consistently secured a relatively large, and others a relatively small, share of the national income, not only because the prices in which they were concerned as producers were maintained at relatively high or relatively low levels compared with the prices in which they were concerned as consumers, but also because these prices were sensitive in varying degrees to a change in the general situation. The more sensitive the price the stronger was the general tendency toward the acquisition of undue gains, since the general movement of all prices was upward at an increasing rate of acceleration. The more ready the price response of any one group of goods or services, the greater, therefore, was the advantage to the sellers of commodities or services in that group. In some cases the persistent spread between different classes of prices was attended by a compensating spread in costs. This was true of sellers of imported wares. The relatively high selling prices of commodities at wholesale, as compared with retail prices, would also seem to have been related in some measure to corresponding differences in costs. In other cases the persistent spread in prices meant high profits. This was the case with producers of goods for export and with producers of commodities the prices of which were quick to respond to world prices. Unskilled workers steadily benefited at the expense of skilled and white-collar workers, while all workers were helped by the virtual confiscation, for the time being, of the property of urban landlords. On the other hand, workers, as a whole, were probably underpaid relatively to their pre-inflation position as modified by the change in general productivity and, if so, the employers obtained the benefit. The evidence for this lies in the fact that the index of wages (skilled and unskilled together) was steadily below that of a cost-of-living index composed of the cheapest means of subsistence.
The gains and losses from persistent spreads in prices were usually enlarged by such point-to-point lags as tended to occur, since the “normal” spread was more often increased than reduced by these lags. The progress of inflation, by increasing the flexibility of all prices, reduced the disadvantage of the sellers of those commodities which, in less disturbed conditions, tend to rise in price somewhat tardily. In the final months of inflation previously existing lags were, it appears in some cases, not only reduced but reversed, and the disadvantage under which the sellers of the lagging commodities or services had till then labored was turned into a temporary boon.
_______________
29 The price data for these commodities were derived from unpublished official figures. Average figures for the period covered are available every fourth month in 1920, quarterly in 1921, bimonthly in 1922, and monthly in 1923. In some months price data for some of the commodities were missing but the number on which quotations are available was never less than 88. The maximum number was 100. The data apply to prices of the various commodities as they were ordinarily sold for final consumption.
30 The index is derived from a fractional part, .6745, of the standard deviation (measured by logarithms) of the link relatives of the separate price indices and represents the approximate percentage limits, measured from the geometric mean, within which 50% of the price relatives would fall if the distribution of logarithms of the price relatives were normal. For the method of calculation and a detailed discussion of this index the reader is referred to The Behavior of Prices, Frederick C. Mills, National Bureau of Economic Research, Inc., New York, 1927, pp. 256 ff.
31 Statistisches Reichsamt index number of general wholesale prices.
32 The index taken to represent exported goods is that of machinery. A few types of machinery, however, would not be exported.
33 The official index of domestic goods includes a group of commodities produced within the country but not necessarily wholly consumed there.
34 End of month. The mean of two successive monthly averages of the index number of general wholesale prices (the index used as a base for the calculation of all ratios in this table) has been used as an estimate of the end-of-the-month figure.
35 Middle of month. The dates of the quotations of the general wholesale price index differ in some cases from those of the quotations of the index numbers of the prices of machinery and finished goods. In such instances interpolation has been made in the general wholesale price index to give an estimate for the corresponding date.
36 if the disposition to purchase stocks had been very strong, funds would no doubt have been diverted in large volume from the commodity to the stock markets. The Germans were under the impression that they were being so diverted, but the facts, as they appear in the relative price of stocks, would seem to put this impression in the category of illusions.
37 The quantum taken, in all cases, was the amount purchasable in 1913 with one gold mark.
38 1923 values for all the index numbers refer to the middle of each month.
39 1922 values for machinery are end-of-month figures.
Source of data: Zahlen zur Geldentwertung in Deutschland 1914 bis 1923, assim.
40 Payment, however, was still made in paper marks. There is a real difference between putting an assessment on a gold basis and in making it payable in gold, or its value equivalent, on the day when payment is actually made. It was not until the days immediately prior to the stabilization of the currency that tax payments in general were required in the latter form.
41 Some months in 1920 and 1921 form exceptions.
42 With the possible exception of imports of which the sole or principal market is in the importing country.
43 At least they were never consciously set above the foreign level on any goods the export of which was even partially free.
44 An exception is to be made for exports in the final months of inflation.
45 The data on export commodities (machinery) are too meager to provide an adequate basis for a similar procedure for this group of prices.
46 The use of the words “trends” and “cycles” may be questioned in view of the shortness of the periods involved. It seemed best, however, to avoid the awkward circumlocution which accurately descriptive expressions would necessitate.
47 Percentage deviation (from the trend) expressed in terms of the standard deviation.
48 This corresponds with the Pearsonian coefficient of correlation. These, and all the coefficients shown in this chapter, especially in the very short periods to which some of them apply, are of questionable value. The charts are probably better indicators of the movements since they give a picture of the general situation. One or two peculiar movements in the curves, on the other hand, may greatly alter the correlation coefficient.
49 In this, and all succeeding comparisons of this sort, the curve indicated has been pushed one or more months to the left of that with which it is compared.
50 Such evidence as is available goes to show that there was a shorter, as well as a smaller, lag in export than in domestic commodity prices.
51 Differentials, that is, apart from those due to costs of transport, tariffs, and similar causes.
52 1923 values for all the index numbers refer to the middle of the month.
53 1922 values for the finished goods index are end-of-month figures.
Source of data: Zahlen zur Geldentwertung in Deutschland 1914 bis 1923, passim.
54 “Their value” is to be construed as their value to the exporter. Special import duties of the exchange-dumping variety, duties which would tend to be borne by the foreign exporter, might keep their value in the levying country low so far as the foreign exporter was concerned.
55 In the final month of inflation, November 1923, the retail index rises above the wholesale. But stabilization had been effected on the 15th of this month.
56 See supra, Table III.
57 See supra, Table XVI and Chart XV.
58 Index number of cost of living excluding housing.
59 A third-degree parabola.
60 The “waves” are rounded rather than choppy.
- 1CLIFFE-LESLIE once remarked that in social matters the greatest scientific progress is made when economic disorders raise vexing questions as to their causes. In the study of social phenomena, disorder is, it is true, the sole substitute for the controlled experiments of the natural sciences. But it sometimes happens that, in the midst of disorder, events move so rapidly that we are not able properly to observe them; disorder may be excessive even to the most detached of scientists. The course of inflation in Germany in the first post-war quinquennium had so much of this character that it has seemed to many to be incapable of throwing any light upon monetary problems. This most striking of monetary experiences has, in consequence, evoked a minimum of scientific curiosity. In spite of the fact that statistics—those notes of process on which the social scientist must so heavily rely—were for some phenomena abandoned in Germany in this period and for others are open to grave objection on the score of accuracy, it has seemed to me that such an attitude implies an unwarranted surrender in the face of difficulties which might with perseverance be surmounted. This book is an attempt, therefore, to discover what actually happened in Germany and either to bring the observed phenomena within the fold of accepted theory or else so to modify that theory as to give it a more catholic character. The actual course of events during inflation has not merely an historical and scientific interest but is of considerable practical importance. Germany’s present position as a nation with heavy international obligations has led to apprehension, both within and without the Reich, as to the future in international finance. The fears of such German competition as may issue out of the debtor status may be dismissed as but thinly-veiled mercantilism but the question as to the possibility of ultimate transfer of the large sums involved in reparations and interest payments must, perhaps, be treated with more respect. The ability of the German economy to provide, within Germany, the funds required, is, on the other hand, no longer seriously doubted. It is hoped that the sequel will throw some light on the disappearance of the latter doubt as also on the prospect of future transfers undisturbed by any serious economic friction.
- 2in Germany. It is based very largely on official German statistics as published by the Statistische Reichsamt and the Institut für Konjunkturforschung. These statistics, for the period studied, are, no doubt, far from perfect, but nothing is gained by attempting to go behind them and there is no reason to suppose that such alternative sources as are available are at all superior. The hope is cherished, perhaps not without justification, that such errors as are involved do not vitiate the conclusions reached. The immense nominal magnitudes attained by all -monetary phenomena in Germany in the inflation-time tend to dwarf the influence of even very considerable imperfections in the statistics. I am far from supposing, nevertheless, that the results obtained are to be taken as clearly proven and I trust that the reader will be no more credulous. They are merely hypotheses
- 4The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 5The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 6The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 9The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 10The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 111
- 12The occupation, by French and Belgian troops, took place in the early days of January 1923. The British government of the day adopted an attitude of passive disapproval and Italy, while assenting to the measures taken, refused to participate actively in the occupation.
- 13The exchange value of French currency, for instance, was brought very low when it became apparent that the French fise could not count on any large receipts from Germany.
- 14When the administration proposed a capital levy to meet the burdens imposed, the industrialists countered with the offer of a loan of one billion gold marks. But, as negotiations proceeded, the industrialists demanded a remission of future taxes and the turning over to them of the state railroads. The government properly refused and resorted to a forced loan which, however, yielded only 50 million gold marks.
- 15The provisions for redemption in “rentenbank certificates” and the mortgage cover provided had, as all students of monetary phenomena will recognize, but a psychological value. The success of the rentenmark was due entirely to the rigid limitations on issue.
- 16The reform was carried out without foreign assistance of any sort. Rather was there covert opposition from certain powerful foreign groups who would have welcomed the threatened political, as well as financial, dissolution of the Reich.
- 17Dr. Schacht has written an excellent account of the reform in his Stabilization of the Mark, George Allen and Unwin Ltd., London, 1927.
- 18
- 19Though practically all of the various administrations in Germany up to the invasion of the Ruhr made sincere efforts to satisfy the claims of the victors, a measure of persecution may have been necessary to break down the overt or covert resistance of financially powerful Germans in private life. The defiance offered the Allies by men like Hugo Stinnes greatly increased the suspicion and hostility toward the Germans, as a people, and was a fateful error. But though persecution may have been necessary to the securing of such reparations as the Germans could pay, if they would, the stupid malice of certain Allied politicians was heartrending. Much of it was due to the still ardent passions of war, either in the breasts of the politicians themselves or in those of their constituents, but a great deal must be attributed to sheer ineptitude. For a time it seemed as if reparation demands were being used merely as a weapon to bring about the disintegration of the Reich. But, if this purpose was ever held, the double-edged character of the sword soon became apparent. For years thereafter the policy was simply one of vacillation. The Bourbons were of the same mind as ever but they had somewhat lost in influence. Liberals grew stronger as time went on but for long the issue hung in the balance. Either party might attain a superiority and temporarily dominate the situation but the final adoption of a policy of moderation was not attained till the “spirited” group had had their fling in the Ruhr.
- 20The history of reparations till the adoption of the Dawes Plan in 1924 is an almost incredible tale of stupid persecution. The confusion of counsels and the vacillation in action which prevailed among the creditor Powers until the adoption of the Dawes Plan, the bickering and endless negotiation, the frustration of all attempts at compromise, were fatal to an orderly process of payments on the part of Germany even if payments in the amount demanded had, at the time, been practicable. The Allies began by demanding the impossible and they capriciously imposed sanctions when the impossible was not performed. Pending final determination of claims, the Versailles Treaty, effective January 10, 1920, required the Germans to deliver bonds as an instalment on their total debt to the value of 100 billion gold marks. Of this amount 20 billion were to mature on May l, 1921. Prior to that date the Reparations Commission was to fix the total of Germany’s obligations and, on the total so fixed, interest was to run at 5%. The Commission did not hand down its decision till April 27, 1921, when the debt was set at 132 billion gold marks. Meanwhile Germany had been making large payments in kind, the value of which was estimated by the Commission at 2.6 billion gold marks and by the Germans at several times that amount, but these were declared to have been inadequate to meet the costs of the armies of occupation. Though, in addition to the enormous levy on existing wealth under the Armistice and Treaty, the Germans had now for nearly two years been making large deliveries out of current production, they were held not only to have failed to pay any reparations at all, but to be steadily incurring still greater capital obligations through the accumulation of unpaid interest charges.
- 21Shortly after the inauguration of the reform Stresemann was followed by Marx as Chancellor, but Stresemann remained in the Cabinet.
- 22In exchange for the 100 billion originally delivered.
- 23The justification alleged for this action was that the Germans had voluntarily defaulted in making the full timber deliveries required of them.
- 24The reparations demands might, however, have caused a fall in the exchange value of the mark regardless of its value in the domestic markets.
- 25See An Economist’s Protest, Edwin Cannan, P. S. King & Son, Ltd., London, 1927, P. 393.
- 26In order to prevent Communistic disorder relief had to be given to the unemployed and subsidies provided for the import of such foodstuffs as could, at whatever price, be obtained. A large part of the gold reserve of the Reichsbank was devoted to the procuring of food imports.
- 27Except in a limited measure the taxing power had been reserved to the constituent States.
- 28Before the war the federal government had had but the rudiments of a fiscal administration. All taxes were handled by the fiscal organization in the several States. Direct taxes were, in principle, confined to the States while indirect taxes were left to the central government. In the later years of the war, however, an excess profits tax had been levied by the federal government in addition to new and increased indirect taxes. Such a tax might come under the German concept of indirect taxes.
- 29cf. Foreign Banking Systems, H. P. Willis and B. H. Beckhart, editors, Chap, VIII, “The Banking System of Germany,” Paul Quittner, Henry Holt and Company, New York, 1929, p. 632, where it is declared that it would be useless to try to connect the development of the German currency system from 1919 to 1923 with any theories of money.
- 30In the matter of mark exchange rates, for instance, sizable differences developed, in the later stages of inflation, between the Berlin and other markets. These were due to the obstruction of arbitrage transactions. At the time that this occurred, however, the Berlin rate was alone of much significance. The Berlin rates have therefore been used throughout. In the matter of prices the alternative sources are the indices of the Berliner Tageblatt, the Frankfurter Zeitung, and the Industrie- und Handelszeitung.
- 31The latter compilation was published in English, as well as in German, for use by the Committees of Experts of the Reparations Commission.
- 32Treasury notes, a fiduciary currency. These were, however, issued rather sparingly. The maximum issue was 356 million marks. Reichskassenscheine had been legal as cash cover in pre-war days but their issue had been closely restricted and few had been available. These Treasury notes are to be carefully distinguished from Treasury bills, a short-term security not used as money.
- 33A form of currency issued by officially established Loan Bureaus against the pledge of securities (or commodities) by borrowers other than the government and the larger banks and business concerns. During the war these notes formed an important share of the circulating medium but thereafter remained comparatively stable in absolute figures (7 to 14 billion marks) and were of constantly declining relative importance. They played but a slight ròle from 1921 onward.
- 34Germany’s Economic and Financial Situation, Statistisches Reichsamt, Zentralverlag G.m.b.H., Berlin, 1923, p. 28.
- 35Zahlen zur Geldentwertung in Deutschland 1914 bis 1923, Statistisches Reichsamt, Verlag von Reimar Hobbing, Berlin, 1925, p. 46.
- 36Committee on Currency and Foreign Exchanges After the War (Cunliffe Committee) First Interim Report, H. M. Stationery Office, London, 1924, p. 5.
- 37Total bank deposits, exclusive of those of small private banks, were £716 million on June 30, 1914, and £1361 million on June 30, 1919. European Currency and Finance, United States Senate Commission of Gold and Silver Inquiry, Serial 9, Vol. I, Government Printing Office, Washington, 1925, pp. 277, 278.
- 38The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 39The cessation of war found Germany in a financial position not markedly inferior to that of most of the other countries involved in the struggle. The far-reaching alterations in the Reichsbankgesetz in 1914 had permitted the suspension of specie payments, had removed the tax on excess Reichsbank note issues, had permitted the Reichsbank to use discounted Treasury bills in lieu of commercial bills as the non-cash cover for Reichsbank notes, and had made Reichskassenscheine and Darlehns-kassenscheine available to meet the “cash” reserve requirements. (The distinction between cash and non-cash cover was abolished in 1921.) This war legislation paved the way for all the coming currency difficulties but it did not differ very greatly from that adopted at the same time in practically all the countries then engaged in hostilities, nor did inflation in Germany, up to the time of the Armistice, much surpass that of some of the principal Entente Allies. The total circulation (including coin other than Reichsbank reserves) in the middle of 1914 is estimated to have been approximately six billions of marks; at the end of 1918 it was something more than five times as much, 32,936,700,000 marks. The total monetary circulation in Great Britain was about £180,000,000 when war broke out while four and a half years later the total of outstanding notes was more than double that sum and stood at approximately £394,000,000. Bank deposits, which in England are a more important index of inflation, had grown in about the same proportion. The total circulation in France (excluding reserves of the Bank of France) in mid-1914 was something over 8,000,000,000 francs (6.5 billion francs in gold and silver, less 4 billion Bank of France reserves, plus 5.8 billion in notes of the Bank of France) while at the end of 1918 the note circulation of the Bank of France amouted to over 30,000,000,000 francs or not quite four times the total pre-war volume of currency. By this date all the gold formerly in circulation had of course disappeared.
- 40Of this amount approximately 97 billion marks had been obtained through long-term loans.
- 41The climax in the reparations conflict came with the invasion of the Ruhr, an action which had no support from some of the creditor Powers. Much as the invasion is to be regretted or condemned, however foolish it may have been as a method of collecting payment, and however evil its immediate results, it was the thunderclap that cleared the air. It showed the obdurate creditors how little could be obtained by a policy of force and, on the other hand, it brought such distress to Germany as to convince even the stoutest opponent of the policy of fulfilment (and they were many and powerful) that it was better to accept a moderated burden of payments which, in spite of strong convictions to the contrary, it might be possible for the country to carry, than to continue in an attitude of stubborn intransigence.
- 42When force had led to disaster, the repercussions of which affected the creditors as well as the debtors, the way was at last open to men of conciliatory spirit, and a solution of the problem, or at any rate a working compromise, could be reached. The invasion was a tragic but triumphant vindication of the policy of moderation, and it led to sympathetic, even if selfish, efforts on the part of the creditor Powers to rehabilitate the economy and finances of the Reich. Once order had been restored progress was possible.
- 43Inflation was therefore combated but half-heartedly at best. Though several of the administrations of the years 1920 to 1923 made valiant attempts to arrest its progress they could not summon the sustained powers necessary to success. All of their efforts came to naught, largely through the apathy or active opposition of powerful business groups who were disposed neither to aid their government in imposing regular taxation nor to cooperate with it in carrying out its obligations under the Treaty of Versailles. Whatever might have been possible to a government backed by a people determined to have no further traffic with inflation, the will to establish a stable standard was lacking until the drama had run its course. It may well be doubted whether a stable standard could in any case have been set up while immense reparations debts were plaguing the situation. But this must remain an open question. So long as wealth and income were being merely transferred by the decline in the value of the monetary unit and not, as a sum, diminished, so long as scapegoats could be found to assume the burdens and yield of their substance to those who knew how to profit from the situation, projects of reform were treated cavalierly. It was only when enterprisers, instead of surely profiting from inflation as they long did, were suddenly plunged into a sea of uncertainties, only when business activity passed from the stage of exhilaration to panic, only when resistance to a further assumption of losses on the part of the public at large became general, that influential opinion veered to a conviction of the necessity of restoring a stable standard. The pass to which matters had then come is shown in Table III.
- 44The successful introduction of the rentenmark in November 1923, a currency without gold backing and, indeed, nothing more than a new tenor of inconvertible paper, with the monetary stabilization thus effected, has been hailed as a miracle. It was certainly a remarkable achievement and bears strong witness to the steadfastness of the German character. The time was ripe but extremely unpropitious. The people had lost all confidence in their currency and in the possibility of its reform. Foreign troops were in possession of their chief industrial districts and the coercive measures adopted by the occupying powers had paralyzed the industrial life of the country. The masses of the urban population were living from hand to mouth, nay, had nothing in their hands but worthless bits of paper which the farmers would no longer accept in exchange for grain. Food riots were general. Political dissolution was in imminent prospect and armed revolt had already raised its head. Affairs were indeed so black that it is clear, in retrospect, that they actually facilitated the reform by imbuing the people with the resolution of despair. The conduct of currency matters was given to Dr. Hjalmar Schacht who possessed the temperament necessary to the situation. His powers were presently enlarged by his election to the Presidency of the Reichsbank. The former President Havenstein had died on the very day that conversion of the old currency into the new was under-taken, a demise which cannot be thought of as other than opportune.
- 45The successful introduction of the rentenmark in November 1923, a currency without gold backing and, indeed, nothing more than a new tenor of inconvertible paper, with the monetary stabilization thus effected, has been hailed as a miracle. It was certainly a remarkable achievement and bears strong witness to the steadfastness of the German character. The time was ripe but extremely unpropitious. The people had lost all confidence in their currency and in the possibility of its reform. Foreign troops were in possession of their chief industrial districts and the coercive measures adopted by the occupying powers had paralyzed the industrial life of the country. The masses of the urban population were living from hand to mouth, nay, had nothing in their hands but worthless bits of paper which the farmers would no longer accept in exchange for grain. Food riots were general. Political dissolution was in imminent prospect and armed revolt had already raised its head. Affairs were indeed so black that it is clear, in retrospect, that they actually facilitated the reform by imbuing the people with the resolution of despair. The conduct of currency matters was given to Dr. Hjalmar Schacht who possessed the temperament necessary to the situation. His powers were presently enlarged by his election to the Presidency of the Reichsbank. The former President Havenstein had died on the very day that conversion of the old currency into the new was under-taken, a demise which cannot be thought of as other than opportune.
- 46The successful introduction of the rentenmark in November 1923, a currency without gold backing and, indeed, nothing more than a new tenor of inconvertible paper, with the monetary stabilization thus effected, has been hailed as a miracle. It was certainly a remarkable achievement and bears strong witness to the steadfastness of the German character. The time was ripe but extremely unpropitious. The people had lost all confidence in their currency and in the possibility of its reform. Foreign troops were in possession of their chief industrial districts and the coercive measures adopted by the occupying powers had paralyzed the industrial life of the country. The masses of the urban population were living from hand to mouth, nay, had nothing in their hands but worthless bits of paper which the farmers would no longer accept in exchange for grain. Food riots were general. Political dissolution was in imminent prospect and armed revolt had already raised its head. Affairs were indeed so black that it is clear, in retrospect, that they actually facilitated the reform by imbuing the people with the resolution of despair. The conduct of currency matters was given to Dr. Hjalmar Schacht who possessed the temperament necessary to the situation. His powers were presently enlarged by his election to the Presidency of the Reichsbank. The former President Havenstein had died on the very day that conversion of the old currency into the new was under-taken, a demise which cannot be thought of as other than opportune.
- 47The history of reparations till the adoption of the Dawes Plan in 1924 is an almost incredible tale of stupid persecution. The confusion of counsels and the vacillation in action which prevailed among the creditor Powers until the adoption of the Dawes Plan, the bickering and endless negotiation, the frustration of all attempts at compromise, were fatal to an orderly process of payments on the part of Germany even if payments in the amount demanded had, at the time, been practicable. The Allies began by demanding the impossible and they capriciously imposed sanctions when the impossible was not performed. Pending final determination of claims, the Versailles Treaty, effective January 10, 1920, required the Germans to deliver bonds as an instalment on their total debt to the value of 100 billion gold marks. Of this amount 20 billion were to mature on May l, 1921. Prior to that date the Reparations Commission was to fix the total of Germany’s obligations and, on the total so fixed, interest was to run at 5%. The Commission did not hand down its decision till April 27, 1921, when the debt was set at 132 billion gold marks. Meanwhile Germany had been making large payments in kind, the value of which was estimated by the Commission at 2.6 billion gold marks and by the Germans at several times that amount, but these were declared to have been inadequate to meet the costs of the armies of occupation. Though, in addition to the enormous levy on existing wealth under the Armistice and Treaty, the Germans had now for nearly two years been making large deliveries out of current production, they were held not only to have failed to pay any reparations at all, but to be steadily incurring still greater capital obligations through the accumulation of unpaid interest charges.
- 48The history of reparations till the adoption of the Dawes Plan in 1924 is an almost incredible tale of stupid persecution. The confusion of counsels and the vacillation in action which prevailed among the creditor Powers until the adoption of the Dawes Plan, the bickering and endless negotiation, the frustration of all attempts at compromise, were fatal to an orderly process of payments on the part of Germany even if payments in the amount demanded had, at the time, been practicable. The Allies began by demanding the impossible and they capriciously imposed sanctions when the impossible was not performed. Pending final determination of claims, the Versailles Treaty, effective January 10, 1920, required the Germans to deliver bonds as an instalment on their total debt to the value of 100 billion gold marks. Of this amount 20 billion were to mature on May l, 1921. Prior to that date the Reparations Commission was to fix the total of Germany’s obligations and, on the total so fixed, interest was to run at 5%. The Commission did not hand down its decision till April 27, 1921, when the debt was set at 132 billion gold marks. Meanwhile Germany had been making large payments in kind, the value of which was estimated by the Commission at 2.6 billion gold marks and by the Germans at several times that amount, but these were declared to have been inadequate to meet the costs of the armies of occupation. Though, in addition to the enormous levy on existing wealth under the Armistice and Treaty, the Germans had now for nearly two years been making large deliveries out of current production, they were held not only to have failed to pay any reparations at all, but to be steadily incurring still greater capital obligations through the accumulation of unpaid interest charges.
- 49This sum is almost half the estimated total wealth of Germany in 1913. The maximum payments under the Dawes Plan were about one-third of the interest on this sum and even these have now been recognized by the creditors to have been excessive.
- 50Under Dr. Schacht’s firm grip it was but a short time before financial order was restored. The permanent success of Schacht’s measures was assured through the work of Chancellor Stresemann and Finance Minister Luther. The government balanced its budget, reparations were presently put upon a practicable basis with the adoption of the Dawes Plan in 1924, and German finances were once again given a solid footing.
- 51All this time cash reparations had been in abyance. Several conferences had been held, to some of which German representatives had been summoned and to others not, but, aside from the determination of the distribution of the payments when received, and demands for a series of annuities graduated steeply to 6 billion gold marks yearly, nothing decisive was done until the London Conference of March 1921. The Germans proposed at this meeting that they should assume a capital liability of 50 billion gold marks. Their offer was scornfully rejected, the Allies proceeded to occupy Düsseldorf, Duisburg and Ruhrort, to set up a customs barrier between the occupied and unoccupied parts of Germany, to sequestrate customs receipts on the Western frontier, and to enact Reparation Recovery Acts under which a large part of the value of their imports from Germany were retained for reparations purposes. The Reparations Commission followed this up with new demands which the Germans felt it impossible to meet. They again offered, however, to undertake an obligation of a capital sum of 50 billion gold marks and to pay annuities upon it up to a total of 200 billion. Though this is a much larger sum than will ever be paid under the arrangement now in operation, and was probably more than the Allies even then ever expected to receive, it was contumaciously spurned, on the ground, apparently, that Germans bearing gifts were to be suspected beyond measure. On May 5, 1921, a schedule of payments, drawn up at London by the Supreme Council of the Allies, required the delivery of bonds to the value of the gold mark total of the debt as set by the Reparations Commission, ordered annual payments of two billion gold marks plus 26% of German exports, and demanded the immediate delivery of one billion gold marks in cash.
- 52Just at this point the German government had brought its tax revenues into some semblance of equivalence with outlays, foreign exchange rates had shown no rising trend for more than a year, domestic prices had been steady, and the circulation of Reichsbank notes, while increasing, had not risen consistently or at a very rapid rate. Under threat of further sanctions the Germans paid in May (1921) 150 million gold marks in cash (foreign exchange). Drafts on the Treasury maturing within three months and guaranteed by the German banks were tendered, and accepted, for the remaining 850 millions immediately payable. The purchase of foreign bills with which to cover these drafts drove the exchange value of the mark steadily downward. At the end of August 400 million gold marks were still unpaid but a six-weeks covering credit was arranged in Holland and England. The repayment of this loan extended the pressure on mark exchange into October. The index of the monthly average of dollar exchange rates (number of paper marks to the dollar equivalent of one gold mark) rose from 14.8 in May to 62.6 in November, the index of wholesale prices (1913 = 1) from 13.1 to 34.1, and the ratio of the monthly increase in the floating debt to all other state revenue from 50% to 155%.
- 53Just at this point the German government had brought its tax revenues into some semblance of equivalence with outlays, foreign exchange rates had shown no rising trend for more than a year, domestic prices had been steady, and the circulation of Reichsbank notes, while increasing, had not risen consistently or at a very rapid rate. Under threat of further sanctions the Germans paid in May (1921) 150 million gold marks in cash (foreign exchange). Drafts on the Treasury maturing within three months and guaranteed by the German banks were tendered, and accepted, for the remaining 850 millions immediately payable. The purchase of foreign bills with which to cover these drafts drove the exchange value of the mark steadily downward. At the end of August 400 million gold marks were still unpaid but a six-weeks covering credit was arranged in Holland and England. The repayment of this loan extended the pressure on mark exchange into October. The index of the monthly average of dollar exchange rates (number of paper marks to the dollar equivalent of one gold mark) rose from 14.8 in May to 62.6 in November, the index of wholesale prices (1913 = 1) from 13.1 to 34.1, and the ratio of the monthly increase in the floating debt to all other state revenue from 50% to 155%.
- 54Cash reparations actually paid no longer played a dominating rôle in inflation though the then hopeless prospect of a relaxation of the Allied demands, and the general expectation of the imposition of further sanctions, were potent influences. On July 12, 1922, Germany applied for a complete lifting of all further obligations for that year and stated that the desperate position of the fise would make it impossible to meet the Allied demands for a further period of two years or more. After weeks of bickering among the creditors, during which Germany was held to the schedule earlier laid down, matters reached an impasse at the end of August. The deadlock was finally broken when the Belgians, who were to receive the balance of the 1922 payments, agreed to accept six months’ Treasury bills (payable in gold and guaranteed by the Reichsbank) in lieu of immediate cash. The respite thus gained by the Germans was of no avail. The toboggan of currency depreciation was then travelling much too rapidly to be checked by any such puny means and, before the notes fell due, the occupation of the Ruhr pushed it over the precipice. Except to take up the bills given to Belgium in the preceding summer, no cash reparations were paid in 1923 and though, on the invasion of the Ruhr, reparations in kind were suspended toward the occupying Powers only, that action was generalized in August. After the collapse of the attempt to support mark exchange in the first four months of the invasion, and of a second similar, but much feebler, essay in July, the era of astronomic monetary magnitudes began. Prices, exchange rates, and the volume of circulating medium vied with one another in daily and hourly upward leaps. The Reichsbank was finally reduced to making apologies for its inability to provide for a weekly output of more than several billion (or trillion) of marks of the required denomination and to an expression of its hope that this situation would be quickly remedied by an improvement in the speed of the printing presses! The printing presses did their bit. By the end of inflation the daily output of currency was over 400,000,000,000,000,000 marks. But, strange as it may seem, this did not effect the expected cure!
- 55Though the war, and the peace, dealt heavy blows to the German economy and though poverty was for some years inevitable, the losses in domestic income like those in territory, natural resources, and property, furnish no adequate explanation of the collapse of the internal value of the currency. Not even state bankruptcy is, in itself, a sufficient cause. “The existence of ‘budgetary equilibrium’ is not necessary [to stability of the currency]. ... An absolutely bankrupt State can have a perfectly good currency without a trace of inflation.” But this possibility can be realized only by the outright repudiation of state obligations. The consequences of such repudiation must always be weighed against the dangers involved in meeting the situation by the issue of fiat money. In the case of Germany, repudiation of recurring reparations obligations would have meant an early application of military sanctions by the victor Powers and complete loss of German sovereignty. Few would deny that to keep things going even temporarily, by inflation of the currency, was the lesser of the evil courses open to the German government and people.
- 56Though the war, and the peace, dealt heavy blows to the German economy and though poverty was for some years inevitable, the losses in domestic income like those in territory, natural resources, and property, furnish no adequate explanation of the collapse of the internal value of the currency. Not even state bankruptcy is, in itself, a sufficient cause. “The existence of ‘budgetary equilibrium’ is not necessary [to stability of the currency]. ... An absolutely bankrupt State can have a perfectly good currency without a trace of inflation.” But this possibility can be realized only by the outright repudiation of state obligations. The consequences of such repudiation must always be weighed against the dangers involved in meeting the situation by the issue of fiat money. In the case of Germany, repudiation of recurring reparations obligations would have meant an early application of military sanctions by the victor Powers and complete loss of German sovereignty. Few would deny that to keep things going even temporarily, by inflation of the currency, was the lesser of the evil courses open to the German government and people.
- 57State bankruptcy lay on the knees of the gods. To repair the ravages of war and to restore order in public finance it was urgently necessary that all remaining economic resources should be carefully husbanded and that the fise should be replenished with revenues derived entirely from taxation. But, along with peace, revolution was ushered into Germany and the energies of the people were wasted in internal conflict. The struggle for control of the new republic not only prevented remedial measures in public finance but enormously increased the existing difficulties. The continuation of the war blockade till after the signing of the Peace of Versailles, June 28, 1919, further augmented the troubles of the government, for though circuses were denied, the people had to be supplied with bread.
- 58This increase was equivalent to about $2,000,000,000 according to the average of wholesale prices for the year.
- 59The administration was far from dilatory and the reform of the finances was attacked with vigor at the earliest practicable moment. The old central government had always been without direct taxing powers and the new did not for some time acquire any greater authority. The constitution, adopted at Weimar August 11, 1919, gave to the Reich the right of legislation over the revenues to be devoted, in whole or in part, to its own purposes but it was not until December 13, 1919, that a federal tax administration could be provided for. Meanwhile, customs duties had been put on a gold basis, an extraordinary single levy had been imposed on corporations, and a heavy tax laid on war profits. Before the year was out legislation establishing a turnover tax had been passed and a special capital levy, the Reichsnotopfer, or National Emergency Contribution, had been ordered. Under the leadership of Finance Minister Erzberger the whole taxing system was revised in March 1920, control of taxation was largely transferred from the States to the federal government, and new impositions were laid on corporations and on the yield of capital. Few sources of revenue remained unexplored and the rates imposed were heavy. But the government was running a losing race with inflation. Its efforts to balance its budget were unsuccessful, the deficiency was made up by short-term loans necessitating constant new issues of currency, and the resulting depreciation depressed revenues still further. Classes of property easy to tax and capable in normal times of providing large revenues were falling rapidly in real value. This was true of all securities yielding a fixed monetary return and also of rentals. The latter were practically confiscated by inflation and by housing legislation felt to be socially indispensable. The depreciation of the currency led to a proper resistance to the taxation of such paper mark incomes as were wholly illusory but the resentment against injustice was perverted to secure unwarranted exemptions. The resulting complexity of the tax structure, the administration of which was necessarily inefficient, still further reduced the revenues. The greatest source of loss, however, lay in the fact that, between the period for which a tax was levied and the dates of assessment and collection, a decline in the value of the currency might wipe out all but a small portion of the purchasing power of the sum received.
- 60The administration was far from dilatory and the reform of the finances was attacked with vigor at the earliest practicable moment. The old central government had always been without direct taxing powers and the new did not for some time acquire any greater authority. The constitution, adopted at Weimar August 11, 1919, gave to the Reich the right of legislation over the revenues to be devoted, in whole or in part, to its own purposes but it was not until December 13, 1919, that a federal tax administration could be provided for. Meanwhile, customs duties had been put on a gold basis, an extraordinary single levy had been imposed on corporations, and a heavy tax laid on war profits. Before the year was out legislation establishing a turnover tax had been passed and a special capital levy, the Reichsnotopfer, or National Emergency Contribution, had been ordered. Under the leadership of Finance Minister Erzberger the whole taxing system was revised in March 1920, control of taxation was largely transferred from the States to the federal government, and new impositions were laid on corporations and on the yield of capital. Few sources of revenue remained unexplored and the rates imposed were heavy. But the government was running a losing race with inflation. Its efforts to balance its budget were unsuccessful, the deficiency was made up by short-term loans necessitating constant new issues of currency, and the resulting depreciation depressed revenues still further. Classes of property easy to tax and capable in normal times of providing large revenues were falling rapidly in real value. This was true of all securities yielding a fixed monetary return and also of rentals. The latter were practically confiscated by inflation and by housing legislation felt to be socially indispensable. The depreciation of the currency led to a proper resistance to the taxation of such paper mark incomes as were wholly illusory but the resentment against injustice was perverted to secure unwarranted exemptions. The resulting complexity of the tax structure, the administration of which was necessarily inefficient, still further reduced the revenues. The greatest source of loss, however, lay in the fact that, between the period for which a tax was levied and the dates of assessment and collection, a decline in the value of the currency might wipe out all but a small portion of the purchasing power of the sum received.

