
The Positive Theory of Capital
Chapter I. The Rate in Isolated Exchange
CHAPTER I
THE RATE IN ISOLATED EXCHANGE
THE exchange of present goods for future, in which interest has its origin, is only a special case of the exchange of goods in general. It goes, then, without saying that the formation of price in this case is subject to the same laws as govern the formation of price in economical exchange generally. The question whether present goods in general obtain an agio, and also the further question of the height of that agio, are both to be answered according to the rules laid down in Book IV. as regards prices of goods in general. What remains for us here is only to amplify and vivify the colourless scheme which demonstrated that the current price of goods is the resultant of subjective valuations coming together in a market, by pointing out those concrete circumstances which in this case—the exchange of present against future commodities—influence the mutual valuation of both.
As before, it is advisable to distinguish between isolated exchange and competitive exchange.
In the exchange which takes place between an owner of a present commodity and a suitor for it, the price, according: to the formula laid down on p. 199, will be fixed some-where between the value of the present good to its owner as under limit, and its value to the suitor as upper limit. If, for instance, £100 present money are worth to their owner exactly as much as £100 of next year’s money,1 while to the suitor they are worth, on subjective grounds (say, on account of temporarily pressing circumstances), as much as £200 of next year’s money, the price of £100 present money will be fixed somewhere between £100 and £200 of next year’s money, and the agio at something between nothing and 100%. The precise figure that is fixed, in the individual case, within these wide limits, depends on the skill and “staying power “displayed by both parties in conducting the negotiations. As a rule, the owner of present goods will be in a position of advantage, because he can do without the exchange and yet suffer no loss, while the suitor is often driven to pay any price for present goods. Hence the familiar cases where, in the absence of competition, usuriously high rates of 50%, 100%, even 200% and 300%, are extorted.
When we go farther, and inquire as to the deeper reasons which affect the subjective valuation of the suitors,2 and thus affect the economic upper limit of the agio, we find them a little different in the case of the consumption loan from what they are in the production loan, to which latter the buying of labour is closely allied.
In the case of the consumption loan the determinants are;—the urgency of want at the time, the probable provision at the time when the loan is to be paid back, and, finally, the degree of the suitor’s underestimate of the future. The more urgently he requires the loan, the more easily he expects to be able to replace it;3 and the less he takes thought for the morrow, the higher the agio to which he will, in the worst case, consent and vice versa.
In the production loan we find different concrete determinants. Here the important thing is the difference in productiveness between the methods open to him who gets the loan, and those open to him who has to do without it. To recur to our old illustration. If the fisher, who has no capital, and can catch only 3 fish a day by hand, gets a loan of 90 fish, and is thus put in a position to make a boat and net in the course of a month, and with these to catch 30 fish a day for the remaining eleven months, the balance stands as follows:—without the loan he catches in a year 3 x 365 = 1095 fish; with the loan he catches nothing in the first month, but 30 per day for the other eleven months, that is, 335 x 30 = 10,050, or a surplus of 8955 fish. So long, then, as he has to give anything less than 8955 (next year’s) fish for the borrowed 90 (present) fish, he gains by the transaction.
In this illustration the difference in possible return between the two productive methods, and, with it, the upper limit of the economically possible agio, is absurdly high—8955 next year’s units for 90 present units is something like 10,000%. But there will always be a very important difference when the choice lies between capitalist production and hand-to-mouth production, as the latter is, of course, always extremely un-remunerative. The difference, again, will tend to grow less when the choice lies between two different capitalist methods; and will become more rapidly less in proportion to the length of the process already secured without the loan. This fact is of very great importance as regards the, rate of interest, not only in isolated, but also in competitive exchange. If we put it in the clearest possible way now, it will give a good basis for what comes later.
In an earlier chapter I called attention to the well-attested fact that the lengthening of the capitalist process always leads to extra returns, but that, beyond a certain point, these extra returns are of decreasing amount. Take again the case of fishing. If what we might call the one month’s production process of making of a boat and net leads to the return of the day’s labour being increased from 3 to 30,—i.e. by 27 fish,—it is scarcely likely that the lengthening of the process to two or three months will double or treble the return.’ Certainly the lengthening it to 100 months will not increase the surplus by a hundredfold. The surplus return—for there will always be a surplus return—will increase by a slower progression than the production period. We may, therefore, with approximate correctness represent the increasing productivity of extending production periods by the following typical scheme.
Production Period. |
Return per annum. |
Surplus. |
Without Capital |
£15 |
— |
1 year |
35 |
£20 |
2 years |
45 |
10 |
3 „ |
53 |
8 |
4 „ |
58 |
5 |
5 „ |
62 |
4 |
6 „ |
65 |
3 |
7 „ |
67 |
2 |
8 „ |
68:10s. |
1:10s. |
9 „ |
69:10s. |
1 |
10 „ |
70 |
0:10s. |
It must be understood that I do not attach any importance to these particular figures. Everybody knows that, in every branch of production and at every stage of technical knowledge, the figures will differ. In one branch the fall of surplus return may be slower, in another it may be more rapid. All I lay stress on is the fact that the figures express the general tendency of surplus returns to fall.—Assume, to complete the hypothesis, that a worker needs £30 a year to maintain him in suitable circumstances, and let us try to find out on this basis the limit of the economically possible agio which a suitor for productive credit may, in the worst case, offer for a loan of £30 a year.
If the suitor has no capital whatever, he can get a return of only £15 without the loan: with the loan, in a one year’s production period he can get a return of £35. In the most extreme case he may therefore, without altering his position for the worse by the transaction, offer an agio of £20; that is 66⅔%. If, on the other hand, the suitor already has a capital of £30 (whence he gets it—whether it is his own or advanced from other quarters—does not affect the case), he can, without borrowing, engage in a one year’s process and obtain a product of £35, and all that depends on his getting the loan is the extension of the process from one year to two, and the raising of the return from £35 to £45; i.e. a yearly surplus of £10.4 Here, then, the suitor can economically offer, at the most, an agio of £10 on £30; i.e. an interest rate of 33⅓%. Similarly, if the suitor, by whatever means, is already equipped for a two years’ process, the loan of £30 is now the cause of a surplus return of £8 (£53—£45) = 26⅔%. Thus the more ample the suitor’s equipment is already—the more capital he has—the lower fall the surplus returns and the ratio of agio dependent on the loan. That is to say, the surplus falls to £5, £4, £3, £2, 30s., 20s., 10s., and the rate to 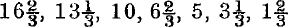 per cent. This fall is bound to emerge unless the returns obtainable in 1, 2, 3, 4, x production periods should run, not, as we have assumed, in the progression of 35, 45, 53, 58, 62, etc., but steadily in the much sharper progression of 35, 45, 55, 65, 75—105—1005, etc. In this latter case, on every one-year extension of the production period made possible by the £30, there would depend a constant surplus return of £10, and the upper limit of the economically possible agio would remain uniform at 33⅓%. But a ratio of increase like this cannot in any case go beyond a few stages in some few productions;5 it cannot go on permanently and without limit in any production.
We come, then, to the important proposition that to in-tending producers, generally speaking, a present loan has less value in proportion to the length of the production periods already provided for from other sources. The proposition directly applies to the rate of interest in isolated exchange, inasmuch as the valuation of the borrower for productive purposes directly gives the upper limit of the economically possible rate. It also allows us, however, to judge in what direction this proposition must influence the rate of interest in competitive exchange, where the price is the resultant of the subjective valuations of individuals, of whom many are intending producers.
As has been said above, the case of productive credit is closely related to the case of the purchase of labour, the employment of productive labourers by the capitalists themselves. Here, however, there enter certain complications which may be as easily and briefly stated under competitive exchange. I shall not, therefore, discuss them separately, but shall go on at once to explain the rate of interest in developed competitive exchange.
6 An assumption which, for the reasons shown on p. 315, holds very widely;—that is to say, among all persons who own more wealth than they can or will spend in their own productive equipment.
7 As regards the sellers of present goods, for simplicity’s sake, we shall adhere throughout the argument to the assumption that their personal circumstances are such that they value present and future commodities alike.
8 We may take the case, e.g., of a youth standing on the brink of manhood, kept very short of cash at the moment by his tutor, but with the prospect of a great fortune coming into his absolute disposal in a few months.
9 The total surplus return, due to the loan, figures out at £20, since, in sach of the two years of the extended production period, the surplus return to labour is £10. But this surplus return is all the same divided over two years, so that only the amount of £10 is to be reckoned to one year. In more skilful disposition, however, the borrower need not take up, at the beginning of the production period, the whole amount of the loan from which he defrays his subsistence during that period: he may raise the loan by successive instalments, and this has for result that the loan is outstanding and requires to pay interest only for half the production period. If such a disposition is arranged the yearly surplus return may in the most extreme case be offered as a half-year’s interest on the subsistence loan, and in this case the most extreme interest rate economically possible is double the figures given in the text. The raising of such subsistence loans by instalments thus exerts exactly the same influence on the relation between subsistence fund and surplus return, and, at the same time, on the height of the interest rate, as does a suitable “Staffelung” of production (see above, p. 325), with which phenomenon, as may be easily seen, it is closely and intimately connected.
10 Up to a certain point the surplus return may now and then increase even in a greater ratio than the duration of the production period. It may, e.g., happen that the transition from rod-fishing to net-fishing shows a greater advance than the transition from primitive modes of fishing to rod-fishing. But beyond a certain point this cannot be maintained, and the surplus returns show a decreasing ratio.
- 1See Monger’s Grundsätze der Volkswirthschaftslehre, p. 93.
- 2See my Capital and Interest, 1890, p. 111.
- 3The English word “Cattle,” as Knies (p. 7) has rightly remarked, has nothing in common derivatively with our conception.
- 4P. 219 (German edition, p. 266). See also my Hechte und Verhältnisse, p. 51. Innsbruck, 1881.
- 5See Mill’s Principles, i. 1. 2.
- 6If we try to represent the classification of our wants by a typical scheme we must, on the principles just laid down, give it something like the following shape:—
- 7When we are told that capital assists in the production of wealth, and then again that it assists in the obtaining of wealth for its owner, we are apt to jump to the conclusion that the two phenomena are intimately and essentially connected, and that the one is the immediate result of the other—that capital can bring wealth to its owner because capital assists in the production of wealth. As a fact, Political Economy has taken up this idea only too readily and too completely. Captivated by the deceptive symmetry that exists between the three great factors of production—Nature, Labour, Capital—and the three great branches of income—Rent, Wage, and Interest—the science, from Say’s day till the present, has taught that these three branches of income are nothing else than the payment for the three factors of production, and that Interest in particular is nothing else than the compensation which capital receives for its productive services when the product is divided out among society. Propounded by various interest theories in various forms this idea has found its most concise and, at the same time, its most naive expression, in the well-known “Productivity theories”—those theories which explain interest directly as the natural fruit of a productive power peculiar to and resident in capital.
- 8Originally the word Capital (Capitale from Caput) was used to signify the Principal of a money loan (Capitalis pars debiti) in opposition to the Interest. This usage; already foreshadowed in the Greek formation κεϕάλαιον, became firmly established in mediæval Latin, and appears to have remained the prevailing one for a very long time, even pretty far down in the new era. Here, therefore, Capital meant the same thing as “an interest-bearing sum of money.”
- 9The theory of the use of goods I have already gone into at length in Capital and Interest. I there showed that material goods are nothing else than such distinct forms of matter as admit of the natural powers residing in them being directed to human advantage. I showed how the “use” they afford is realised through concrete activities of these natural powers, and, therefore, by real forth putting of power. I showed how a use (Gebrauch or Nutzung) cannot be made of them otherwise than by taking the peculiar forms of the energy of the good at the proper moment, supplying the conditions necessary to render them available where they previously existed in an unavailable form, and then bringing these forms of energy into proper connection with that object in which the useful effect is to take place. On these considerations I based the conception of the “Material Services” (Nutzleistungen) which I believe to be the only one that corresponds with facts, and rejected certain shadowy ideas which connected the old theory of interest with the word “Uses” of goods. What remains for us here is, on the same lines, to lay down certain fundamental ideas as to the origin of material goods.
- 10If we look more closely at the way in which man assists natural processes, we find that his sole but ample contribution consists in the moving of things. “Putting objects in motion” is the idea which gives the key to all human production and its results;—to all man’s mastery over nature and its powers. And this is so simply because the powers reside in the objects. Now when man by his physical powers—the power of moving things—is able to dictate where the object shall be, he obtains a control over the place at which a natural power may become effective; and this means broadly a control over the way and over the time in which it may become effective.

