

The Keynesian paradigm suffered in the stagflation of the 1970s. Price inflation and unemployment surged simultaneously, which resulted in broad skepticism of the old Keynesian models while loyal Keynesians scrambled to offer explanations. Moreover, it became apparent that the Keynesian consumption function didn’t hold up to empirical scrutiny—disposable income wasn’t as good of a predictor of aggregate consumption as early Keynesian models assumed.
This watershed moment in the history of economic thought produced new tributaries and strengthened some existing ones. Old Keynesianism had already been formalized and neoclassicized by Samuelson, Hicks, Solow, and others, giving us the IS-LM model and the Phillips curve, among other devices. Milton Friedman popularized and developed the monetarist framework, arguing that the stagflation of the 70s was the result of expansionary monetary policy. Friedman’s work paved the way for later economists (like Lucas and Barro) to incorporate rational expectations and certain microeconomic equilibrium assumptions into macro models, which showed that Keynesian stabilization policy wouldn’t work as intended. We got Real Business Cycle theory, New Keynesianism, a New Neoclassical Synthesis, Post-Keynesian reactions, dynamic stochastic general equilibrium (DSGE) models, the Taylor Rule, and, unfortunately, Paul Krugman.
The mainstream consensus that has emerged out of this hodgepodge is that Keynes was right about a lot, but his framework needs “microfoundations.” Aggregates are fine, but we need to remember that they are determined by activity at the firm- and household-level. The answer: stick some neoclassical models of consumer and firm behavior into DSGE models and make sure that these agents are forward-looking.
The 2026 Nobel Memorial Prize
This year’s co-winners of the Nobel memorial prize in economics helped put that answer together. Robert Hall, whose paper I linked earlier, developed a new consumption function based on optimizing, forward-looking consumers. Michael Woodford used a version of Hall’s consumption equation and added equations for firms and interest rates.
Those equations look like this:
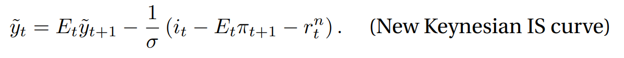

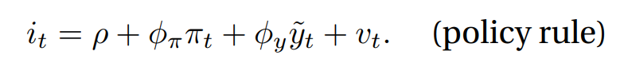
[Reproduced from here.]
In English, the first equation says that people spend more today when they expect the economy to perform better soon and when interest rates are below their “natural” level.
The second equation says that inflation will be higher when firms expect higher inflation in the future and when the economy is producing above its natural level, putting upward pressure on production costs.
The third equation says that interest rates will be set based on inflation (more inflation, higher interest rates) and whether the economy is “overheated” (positive output gap, higher interest rates) or underperforming (negative output gap, lower interest rates). The third equation also includes vt, which captures interest rate surprises—sometimes monetary policymakers don’t follow the rule strictly based on inflation and output gaps.
Thus, Hall and Woodford’s work laid the foundation for the way mainstream economists think about the macroeconomy and the way central bankers view their role in stabilizing macroeconomy. People spend and save based on their expectations of the future. Firms have sticky prices they can only set once in a while or at a cost. Interest rates ought to be set to keep inflation close to target and to maintain full employment (i.e., close output gaps). This is the modern New Keynesian paradigm.
Notice anything missing?
There’s no money, no capital structure, and no entrepreneurship. It lacks a market process through which entrepreneurial appraisals and consumer preferences generate market prices. The “microfoundations” are representative agents that mechanically spend, set prices, or set interest rates based on a seemingly ad hoc collection of inputs.
The Austrian Alternative
Indeed, readers of Mises.org know that another tributary in the history of economic thought formed in the Marginal Revolution watershed 100 years before the 1970s stagflation. This watershed produced three main tributaries, two of which, following William Stanley Jevons and Leon Walras, eventually led to the same New Keynesian lake, and another, following Carl Menger, led to the Austrian tradition, including Böhm-Bawerk, Mises, Hayek, and Rothbard.
In the Austrian tradition, there was never a micro/macro split that needed reconciliation. The two bridges were always there: monetary and capital theory. Menger explained how money originated and why it is valued. He explained that the value of the factors of production depend on the anticipated value of the consumer goods they help produce. Böhm-Bawerk developed capital theory and introduced the structure of production, which is conditioned by entrepreneurship and interest. By 1912, Mises “performed the mighty feat of integrating monetary with micro theory, of building monetary theory upon the individualistic foundations of general economic analysis” (from Rothbard’s Foreword to The Theory of Money and Credit).
Mises also refined the theory of interest, showing that it is based on individuals’ time preference. Mises and Hayek developed a theory of business cycles based on the way credit expansion distorts the structure of production. (After Mises died, Hayek won a Nobel memorial prize for this business cycle theory). Rothbard formalized and extended Böhm-Bawerk and Mises’s analysis, creating a cohesive body of economic theory fully capable of explaining micro- and macro-level phenomena based on the actions and interactions of individual market participants with subjective preferences, time preference, and anticipations of future market conditions.
What else is wrong with those equations?
On a fundamental level, Austrians disagree that the actions of market participants may be expressed by equations and that the macroeconomy can be thought of as an aggregation of representative agents. There are no constant relations in human action, and people are different from one another. Humans are not homogeneous robots in laboratory settings that respond to a handful of quantitative inputs. New Keynesians took the complex interactions of millions of individuals and reduced them to a handful of stable quantitative relationships.
The first equation treats aggregate consumption and output as quantities governed by expected future economic conditions and interest rates. But this obscures what consumption actually consists of: individual exchanges of money for particular goods and services. Consumers purchase goods when they prefer those goods to the money they surrender. Aggregate spending is simply the monetary sum of these individual exchanges, not an independent force determining economic activity.
To be sure, consumers can consider future market conditions when they make their buying choices. They might think about future raises, promotions, the possibility of losing their jobs, or the future course of interest rates. But they might not. Some may consider such things more often or more intensely than others. Some may consider such things when making some buying decisions like a house but not when they’re putting a package of bacon in the grocery cart. There is no reason to believe that the same handful of variables will determine every consumer’s decisions, much less that they will determine the decisions of all consumers in stable, quantitatively predictable ways. (Also, one of the variables in the first equation, the neutral rate of interest, is completely unknowable, even to wise central bankers and macroeconomic forecasters).
The second equation is circular as an explanation of prices: prices depend on prices. It says that firms set prices on the basis of what they expect their competitors to charge and what they expect production costs to be. But what determines those future prices? What determines the prices of the factors of production?
This is where Menger’s theory of imputation, Böhm-Bawerk’s capital theory, and Mises’s theory of the entrepreneur offer a much better explanation. Today’s consumer goods prices are determined by consumer demand over the total stock of the produced goods. As entrepreneurs bid against each other for factors of production, they consider future consumer demand for their products. The prices they are willing to pay for those factors depend on their anticipations of the future revenues that the factors will help generate. Since those revenues occur in the future, entrepreneurs discount them by the interest rate, determined by time preference, when appraising the presently available factors of production. The result is that factor prices are ultimately derived from anticipated consumer valuations, rather than the old fallacy that consumer goods prices are determined by production costs. This fallacy is resurrected in the second equation.
Of course, New Keynesians might respond that their model isn’t meant to explain individual prices, but rather aggregate price inflation. But this misses the point. For Austrians, the movements of particular prices relative to one another are essential to understanding how resources are economized via economic calculation. Factor prices reflect anticipated consumer demand and the scarcity of productive resources. Changes in relative prices affect entrepreneurial calculations, and the use of scarce resources in the various stages of production. Monetary expansion does not raise all prices simultaneously or proportionally; it enters the economy at particular points, altering relative prices and redistributing resources toward the source. By reducing these complex processes to an aggregate inflation rate and an output gap, New Keynesian models neglect the market processes that are essential to understanding Cantillon effects and business cycles.
The third equation completes the picture by putting central bankers in charge of setting interest rates to stabilize the economy. But why should the economy have these goals in the first place (i.e., stable prices and maximum employment)? The economy is not a person with its own goals. It is made up of millions of individuals pursuing their own ends through the division of labor and voluntary exchange. No one seeks to maximize employment for its own sake. Employment is a means to an end. If maximizing employment were the goal, we wouldn’t have weekends, vacations, or retirement. Likewise, prices are exchange ratios that must be free to fluctuate because preferences, expectations, and supplies change. Even the Fed’s interpretation of “price stability” is peculiar: it targets 2 percent annual price inflation. Why 2 percent?
Furthermore, manipulating interest rates results in terrible outcomes. Without interference, interest rates would reflect time preference: people’s willingness to abstain from consumption and dedicate present resources to production. Market interest rates, therefore, reflect the availability of resources for longer-term production projects. When central banks artificially lower interest rates through credit expansion without a corresponding increase in genuine saving, they encourage entrepreneurs to start projects that cannot be completed. This is the essence of the Austrian theory of the business cycle.
It gets worse: How are central bankers supposed to know the “correct” interest rate in the first place? Even within the New Keynesian framework, central bankers cannot directly observe the variables they’re supposed to target. The so-called natural or neutral rate of interest isn’t observable, and neither is potential GDP, which is necessary for calculating the output gap. Instead, economists construct elaborate statistical models to estimate these things, producing different answers depending on their assumptions and methods. Even the observable data going into these models are questionable. Which price index should we use to measure inflation? Headline CPI? Core PCE? Super Core? Trimmed mean? Which measure of aggregate production should we use? How do we account for revisions to the data? Surely political motivations would never enter through this information gap.
We can also judge a tree by its fruit: did the New Keynesian paradigm usher in macroeconomic stability as planned? No. We’ve had financial crises, booms and busts, above-target inflation, and dramatic swings in unemployment. The federal debt surpassed $40 trillion this year, and government spending shows no signs of slowing. It seems that government officials and central bankers equipped with the “micro-founded” New Keynesian framework have generated more chaos.
Austrians prescribe sound money and a “hands off” approach from the government. Don’t try to boost or inhibit spending. Don’t target a particular inflation rate. Don’t manipulate interest rates. It wouldn’t result in stability as defined by New Keynesians, but it would result in a good kind of stability. Entrepreneurs wouldn’t be misled by false interest rates. Consumers could confidently spend and save without guessing how much of their purchasing power would be sapped by inflation. Investors would look at expected profitability and business fundamentals rather than betting on whether the central bank will raise or lower interest rates at the next FOMC meeting.
Zigs and Zags
It’s easy for Austrian economists to take potshots at the mainstream, so let me soften my critique of New Keynesianism with this: Robert Hall and Michael Woodford certainly deserve the Nobel memorial prize. Their work has had a substantial impact on the way governments and central banks view their role in stabilizing the macroeconomy. The two of them have a combined total of over 150,000 citations by other economists, indicating a massive mark on the field.
Hall and Woodford deserve the prize because it is “awarded to the person(s) who have performed work of the highest significance in the economic sciences.”
But “significance in the economic sciences” does not always equal sound economics. As Rothbard noted, “rather than everyone contributing to an ever-progressing edifice, economics can and has proceeded in contentious, even zig-zag fashion, with later systemic fallacy sometimes elbowing aside earlier but sounder paradigms, thereby redirecting economic thought down a total erroneous or even tragic path.”

