
Prosperity and Depression
8. Some Recent Discussions Relating to the Theory of the Trade Cycle
——————
§ 1. INTRODUCTION
General nature of the literature reviewed.
The greater part of the literature to be discussed in this chapter emanates from, and centres around, Mr. KEYNES’ General Theory of Employment, Interest and Money. It is not all business-cycle theory in a strict sense, but rather general economic theory dealing with analytical tools which may be used for trade-cycle analysis as well as for other purposes. To a large extent, the theories to be discussed are not even of a dynamic nature, but are static-equilibrium theories. (This point will come up for detailed discussion in § 6 of this chapter.)
For a number of reasons, it is very difficult to review these theories. First, they are comparatively young and have not yet found anything like a definitive formulation. They are still in the process of development and clarification; there exist, and continue to appear, versions1 which are by no means identical in all respects. The points at issue are frequently very subtle, and the argument necessarily becomes complicated and involved.
Differences in terminology versus differences in substance.
Secondly, these theories suffer from the fact that their authors have not been able to make clear in all cases whether apparent differences between their views and those of other writers rest on different empirical assumptions or only on a different usage of terms; in other words, whether differences are of a material kind or of a purely terminological nature. There can be no doubt that, in recent years, the discussions on saving and investment and the possibility of their being unequal, on hoarding, liquidity-preference and the rate of interest, and similar topics, have made it increasingly evident that purely verbal misunderstandings and slight differences in the definition of terms have played a very great rôle.2 The exaggerated impression of importance which prevailed with respect to the real (as against purely terminological) differences between different schools of thought, especially between what some writers3 like to call the “classical” and the “modern” view, has already been modified. But it is safe to assume that this process of terminological clarification is not yet completed, and it is hoped that the present chapter will do a little to hasten it.
Even in those instances where the new theories amount to nothing more than a terminological innovation and cannot be said to be in material contradiction to the traditional views, they have sometimes served a useful purpose, by bringing to light hidden implications in the older theoretical schemes and forcing the propounders of “rival” theories to make all their assumptions clear and explicit.
All this will be illustrated in the following sections.
§ 2. SAVING AND INVESTMENT4
Everyday meaning of S and I ambiguous.
In preceding chapters, we have repeatedly had occasion to speak of saving and investment, and differences between them, without giving a precise definition of these terms. The reason is that the writers whose theories have been reviewed have refrained from giving careful definitions of the terms, consistent with the use to which those terms are put. They evidently thought they could safely rely on the everyday meaning of these terms.
The discussions in recent years have clearly shown that this is not the case. Not only is the everyday meaning of these terms not unambiguous—different writers interpret it in different ways—but also it has been demonstrated that one particular definition, which it is fair to call a good prima-facie formulation of the everyday meaning of those terms, makes it impossible to speak of differences between saving and investment, because, on that definition, S and I are not only equal by definition, but are in reality the same thing.
Neo-Wicksellian usage of S and I.
In the Neo-Wicksellian literature and related writings reviewed above (Chapter 3) under the title of “The Over-investment Theories”, it is usual to speak of differences between S and I. Phrases such as the following occur again and again: “Investment may be financed, not only out of (voluntary) saving, but by inflation”, “out of newly created money”, “out of hoards”. Conversely: “Not all the current savings need be invested”, “a part of them may go into hoards”, “may disappear in the banking system”, “may be used for repaying bank loans” and thus “run to waste”
Equality of S and I has been used as a criterion of equilibrium.5 Any divergence between S and I means a disruption of equilibrium. If I exceeds S, we get inflation; an excess of S over I means deflation. Prosperity periods are caused, or at least characterised, by an excess of I over S; depression periods, by an excess of S over I. This language is irresistibly convenient and seems to express very realistically what actually happens during the upswing and the downswing of the cycle respectively.
Mr. Keynes’ equality of S and I.
It has, however, been questioned by Mr. KEYNES Mr. Keynes’ and his followers.6 Why is it considered fallacious? equality of That is very simple to explain. We have only to S and I. reflect for a moment on what we really mean by S and I. Mr. KEYNES’ definitions are these: For the economy as a whole—just as for any individual—saving is that part of total income which is not spent on consumption: S = Y—C. Investment is that part of total output (in value terms) which is not consumed: I = Output—C. On the other hand, income of society as a whole is defined as the value of output. Therefore I =Y—C. Hence, S = I.7
If we accept these definitions, which appear prima facie to correspond quite well to the everyday meaning of the terms, S and I are necessarily equal over any period of time, because they are identically defined: both of them as Y—C. It then becomes nonsensical to speak of, or to imply, differences between them.
Controversial issues.
Now a number of questions arise which will be taken up one after the other. First, some readers, who are accustomed to speak of differences between I and S would probably like to see how, in typical cases, the equality of I and S works out in detail. Such an analysis will reveal that the definitions given above are, after all, not always in harmony with the everyday usage of the terms.
Secondly, the question arises as to how S and I can be re-defined so as to make sense of the whole body of doctrine which speaks of differences between them. We shall see that this can be and has been done in several ways, and that it would be superficial to dismiss as meaningless all theories which imply a difference between S and I, even if some of the theorists in question may have carelessly defined them in such a way that they are necessarily equal.
Thirdly, it might be asked whether, if we adopt Mr. KEYNES’ definitions, S and I are not, in reality, identical rather than necessarily equal. Do S and I not really denote, are they not only different symbols for, the same thing—unconsumed output? If that is so, why retain two terms? Why not drop the one or use them interchangeably?
How S and I are equated in the case of inflation.
Let us first do some exercises in the application of our definitions by discussing a few typical cases. Assume that new investments are made either by the Government or by private producers and that they are financed by the creation of new money; for example, a factory or a railroad is being constructed. Suppose that there are unemployed workers and idle resources, so that total production can easily be expanded. The money is created by the banks and handed over to the entrepreneur (or the Government) either as a short-term loan or by purchasing long-dated securities, new ones or old ones which have so far been in the possession of the constructor of the railroad.
There is then a certain amount of (new) investment, but, if we adopt Mr. KEYNES’ definitions of I and S, we are precluded from saying that these new investments have been financed by “inflation”, instead of by “voluntary” saving.8 According to Mr. KEYNES’ and his followers’ account of the matter, there must be somewhere savings corresponding to the amount of new investment. Where are they? The answer has been given most clearly by Mr. HARROD. “For a few days, the whole of the new net investment may be financed by those who receive the money; before they begin to spend that money, they save what they receive.”9 That is to say, the workers who are engaged in constructing the railroad are said to save the money which they receive, say, on Saturday until they spend it during the following week. If they keep all the money over night, they are said to have saved it. When they then gradually spend it on consumers’ goods and consume these latter, they are said to dissave. The expressions “receiving” and “spending” are replaced by “saving” and “dissaving”. But when people thus dissave, “the stocks of consumption goods will be depleted; this involves disinvestment.”10 So the new investment is first matched by saving and then cancelled by disinvestment; S is always equal to I. If, on the other hand, the production of consumption goods increases pari passu with the rising demand (by chance, or because producers have correctly foreseen the coming rise in demand), there is no disinvestment to cancel the original new investment; but, since the new money must always be somewhere, those people who hold it and have not yet passed it on are said to perform the necessary saving.
This account of the matter may seem strange; it is not usual to say that the savings which finance the construction of new capital are provided by the workers who are engaged in that construction job and not by those who provide the money which is used to hire those workers. It is furthermore not in accord with the everyday usage of the terms to say that a man saves if he keeps his income in the form of money for a short time, owing to the simple fact that income is paid out discontinuously and spent more continuously. Only if it is kept unspent for longer than the usual income period, would one ordinarily say that it has been saved.
It must, however, be admitted that this unusual way of putting the matter follows from the literal application of the definition: S—Y—C. On Saturday evening, the income of the worker has increased; his consumption has not yet gone up; hence he has saved.11 We have here an example where this prima facie plausible definition of S diverges clearly from the everyday meaning of the term.12
How S and I are equated in the case of deflation.
Let us now consider the converse case, where money is withdrawn from circulation. Let us assume that some people do not spend the whole of their income, or more generally of their money receipts,13 and accumulate cash or idle deposits. This has been conveniently expressed by saying that saving exceeds investment, because part of the savings are hoarded14 instead of being invested.
According to Mr. KEYNES’ definition of saving and investment, this way of describing the matter is no longer permissible. There can be no divergence between S and I. How are they then equated in this case? The answer is very simple. If some people save part of their income and keep it in liquid form, one of two things, or a combination of them, must happen: either goods which otherwise would have been sold accumulate and that constitutes investment which corresponds to the saving, or else sales are maintained at the former level by cutting prices, and the retailers suffer losses; these losses reduce their income—and hence their saving—by an amount equal to the original decrease in spending.15 Hence, the original saving is cancelled by an equal decrease in saving (which, if we start from a position of zero saving, becomes negative—dissaving) by somebody else.
It seems to be pretty clear that there is no real problem at issue between those who speak of a difference between S and I and those who maintain that S and I must be equal. Both schools speak about the same phenomenon in different terminologies. No statements about facts are disputed, for what may happen if some people reduce their rate of spending is assumed and can be described in a neutral terminology which avoids the word “saving” and uses instead the terms “receipt” and “expenditure” of money.
Alternative definitions.
There remains, however, the question of how saving and investment should be defined to enable us to be consistent in speaking about differences between them.
Three sets of definitions under which S need not be equal to I will be discussed t first, Mr. KEYNES’ definitions of S and I as given in his Treatise on Money; secondly, Professor ROBERTSON’S “period analysis”; and, thirdly, the Swedish distinction between ex ante and ex post saving and investment, which is also made by Mr. HAWTREY.
The terminology of Mr. Keynes’ Treatise on Money.
It was Mr. KEYNES’ Treatise on Money which made the catchwords “excess of saving over investment” and “excess of investment over saving” popular in English literature.16 Since, however, this piece of verbal machinery of the Treatise has been abandoned by its author, we may be very brief. Mr. KEYNES defined income as exclusive- of losses and profits. I was defined as the value of unconsumed output; and S as income minus consumption.17 Hence, an excess of saving over investment was so denned as to mean losses; and an excess of investment over saving, so as to mean profits. In turn, profits and losses were defined as that amount by which actual entrepreneurial income exceeds, or falls short of, that level which would leave the entrepreneur under no inducement to change the rate of output and employment.18 In consequence, entrepreneurs, by definition, had an incentive to expand output whenever investment exceeded savings, so that an excess of investment over savings was robbed of all the causal significance which was imputed to it.
We now come to Professor ROBERTSON’S definition of saving, which seems to give the best and most precise expression to what is in the mind of those who spoke and speak unsophisticatedly of differences between S and I.19
Professor ROBERTSON’s definition of saving.
Professor Robertson explicitly introduces from the beginning the discontinuity of the income streams by adopting a “period analysis”. He assumes that money income20 received in the current period—“to-day”—becomes available for expenditure only during the next period—“to-morrow”. Such a “day” may be longer than a day: it may be as long as, say, a week. The exact length depends on the habits and techniques of payments. For any day, Professor ROBERTSON distinguishes, accordingly, between disposable income and earned income. The disposable income of to-day is the earned income yesterday, and the earned income of to-day becomes disposable income to-morrow.
Saving for any day is defined as disposable income of the same day (= earned income of the day before) minus consumption expenditure of the same day. Investment, on the other hand, is defined as actual expenditure on new investment goods during the day. Hence, investment can be greater than saving, because money may be spent out of other sources than from (disposable) income. Expenditure may be made from newly created bank money or from hoards. This money becomes, of course, earned income on the same day and disposable income on the following day. Thus an excess of I over S implies an increase of to-day’s (earned) income over yesterday’s (earned) income. Similarly, an excess of S over I implies a decrease of to-day’s income as compared with yesterday’s income. This evidently expresses precisely what is meant, when, in an unsophisticated way, it is said that, if I runs ahead of S inflation ensues, and that an excess of S over I implies deflation.
It should now be pretty clear how statements in the language of those who (explicitly, like Professor ROBERTSON, or implicitly, like many others) distinguish between disposable and earned income can be translated into statements in the language of Mr. KEYNES, which does not make this distinction. This has been clearly realised by Mr. KEYNES himself21 and by Professor HANSEN.22
Money income versus money value of output.
There is another point of ambiguity which may give rise to misunderstanding. Professor ROBERTSON and others use “income” in the sense of actual money income involving monetary transactions (a transfer of money). This need not be quite the same thing as income in the sense of the money value of the output as a whole.23 A corresponding distinction should be made about saving, whilst investment is almost invariably used in the sense of money value of unconsumed output. Mr. KEYNES uses the terms “income” and “saving” in the value sense, and Professor OHLIN says explicitly that income, in his sense, “has nothing to do with the actual receipt of cash”.24
The two magnitudes need not coincide, because income in the sense of money value of output comprises items which do not give rise to monetary transactions—e.g., “imputed” income (example: the services of a house to its owner), or “bartered” income, or the accumulation of stocks. But even if all transactions of goods took the shape of purchases for, and sales against, money, there would be certain discrepancies between the two types of income, because money income is received at discreet intervals, while real income flows more continuously. Furthermore, if new money is created and handed to somebody not in exchange for a service performed by the recipient (e.g., an unemployed), this might be called that person’s money income to which, before the money is spent, there corresponds no increase in the value of output.
In the case of non-wage and non-salary income, the concept of actual money income is beset with further difficulties, which make it impossible to define it by looking at the monetary transactions alone without any reference to the sphere of real goods. Not all money receipts and expenditures of a firm are income receipts and expenditures. Which part of the total flow of money has to be regarded as income and which as “intermediate transaction” can be defined only with reference to the “real” sphere. But even if this has been accomplished satisfactorily, it is in many cases not possible, without more or less arbitrary conventions, to identify individual transactions (either the “real” or the corresponding “monetary” transactions) as income or non-income transactions. It is, for example, not admissible to regard all purchases of consumers’ goods by the final consumer as income transactions; for consumption can exceed income, the difference being dissaving. Nor is it always possible to identify an individual purchase of a capital good as constituting new investment or replacement—that is, as belonging to the income sphere or not. Income and new investment can be determined only in the aggregate, as residuals. By deducting from total output what is considered necessary for maintaining the capital stock intact, we determine income; and by deducting consumption from income, we obtain the volume of new investment.
The Swedish ex ante and ex post analysis.
We now come to another set of definitions which gives meaning to the concept of a difference between S and I. This scheme has been worked out by a group of Swedish writers such as Mr. Erik LUNDBERG,25 Professor Erik LINDAHL,26 Professor Gunnar MYRDAL27 and Professor Bertil OHLIN.28 A very similar scheme has been proposed by Mr. HAWTREY.29 The Swedish writers distinguish for all the magnitudes concerned—income, saving, investment and others—between an ex ante and an ex post sense.30 Looking back at any period of time that has elapsed, one- can measure—at least in principle—what Y, C, S, I, etc., actually were. This is the ex post, or registration or accounting, sense of these magnitudes. Like Mr. KEYNES, Professor MYRDAL and Professor OHLIN 31 define S and I ex post in such a way that they are always equal—i.e., both as Y—C.
From the ex post sense of these concepts, the ex ante sense must be carefully distinguished, and what is true of the ex post phenomena of a certain kind need not be true of the corresponding ex ante phenomena. The ex ante manifestations of income, saving, investment, etc., are the expectations entertained by all the individuals and firms in respect of those magnitudes at any point of time for some period ahead of that point. Any member of an economic society at any moment of time expects a certain income, and plans or intends to spend a certain part of it on consumption and to save another part. The “plan to save” must be associated with the “plan to increase the quantity of cash” or with the “plan to lend”. (These are the only two alternatives “if the use of one’s own savings for new investment is treated as giving credit to oneself”.)32
The entrepreneurs expect certain prices to rule, a certain demand situation, certain interest rates and production costs to exist, etc., and, on the basis of these expectations, they plan a certain amount of investment.
Summing up the expected income, planned consumption, saving and investment of all individuals, we arrive at the ex ante magnitudes of these phenomena for the economy as a whole.
How equality of S and I is brought’ about ex post.
“There is no reason”, according to this school of thought, “for assuming that planned saving and planned investment should be equal. But when the period is finished, [realised] investment is equal to [realised] saving. How does this equality come about? The answer is that the inequality of ex ante saving and ex ante investment sets in motion a process which makes realised income differ from expected income, realised saving from planned saving and realised new investment differ from the corresponding plan.33 This difference we can call unexpected income, unexpected new investment, and unintentional savings. . . . The business-man who, after the closing of his accounts, finds that he has had a larger net income than he expected and that, therefore, the surplus over and above his consumption is greater than his planned savings, has provided ‘unintentional savings’ which is equal to this unexpected surplus. Un expected new investment, which, like unintentional saving, may, of course, be negative, can mean simply that stocks at the end of the period are different from what the entrepreneur expected. . . .”34
“Assume that people decide to reduce their savings and increase their consumption during the next period by 10 millions, as compared with realised savings and consumption during the period which has just finished. . . Assume further that the planned investment is equal to the realised investment during the last period.” (Since realised savings and realised investment are equal, these assumptions imply that ex ante saving falls short by 10 millions of ex ante investment.) “What will be the result? Retail sales of consumption goods will rise 10 millions and the stocks of retailers will, at the end of the period, be down—e.g., 7 millions, the remaining 3 millions being extra income of the retailers. This latter sum is ‘unintentional’ savings. Thus realised saving is down only 7 millions, or the same amount as realised investment.”35 Realised investment is down because the depletion of stocks by 7 millions is counted as unintentional disinvestment.36
Similarly, other cases of differences between ex ante saving and ex ante investment can be analysed. “When the State finances public works with the printing of new notes, the increased investment is matched [ex post] by increased ‘real’ savings”, although ex ante investments were in excess of savings, since it is assumed that no planned savings corresponded to the planned Government investment. “At the end of the period, some people hold more cash than at its beginning. This is evidence that they had an income which they have not consumed—i.e., that they have saved. Ex post, there is ex definitione equality between savings and investment.”37
The ex ante concepts as schedules.
In a later article,38 Professor OHLIN39 has given important elucidations of his theories. He explains there that his ex ante concepts of savings, investment as well as the other closely related pair of concepts—viz., demand and supply of credit—are intended to mean the same thing as demand and supply schedules. “Ex ante saving” means the schedule showing how much people are willing to save at different hypothetical rates of interest. And “ex ante investment” is the schedule showing how much people are planning to invest at different interest rates.
Demand and supply of credit determine the rate of interest.
However, the rate of interest is not determined by the interaction of the curves relating to saving and investment; it cannot be explained by demand and supply of saving. “There is no such market for savings and no price of savings”(page 424). But there is a market for credit,40 and “the price of credit [i.e., the interest rate] is determined by the supply and demand curves for credit or, which amounts to the same, for ‘claims’” (pages 423 and 424).
The two pairs of curves, relating to saving and investment on the one hand and to credit or claims on the other, are interrelated, but they are not identical. How are they interrelated? The supply of credit (= demand for claims—e.g., for bonds) is not equal to planned savings (the supply of saving), because “it is possible to plan to save and to increase the quantity of cash instead of lending. Also, one can plan to extend new credits in excess of planned savings if one is willing to reduce one’s own quantity of cash.”41
Similarly, the demand schedule for credit is not identical with the curve for planned investment, because there may be a “desire to vary the cash held, to cover expected losses or to finance consumption”.42
Obviously, a similar proviso as for “increases” or “decreases of cash” held (in other words, for hoarding and dishoarding) must be made for changes in the quantity of money made by the banking system or the Government. An increase in the quantity of money has the same effect as a reduction in cash holdings of some individuals: it increases the supply of credit beyond ex ante saving. The case of a decrease in the quantity of money is similar.
Diagrammatic exposition.
Taking everything into account, it would seem that Professor OHLIN’S theory can be precisely stated in the words of Mr. A. P. LERNER:
“The rate of interest is the price that equates the supply of ‘credit’, or saving plus the net increase in the amount of money in a period, to the demand for ‘credit’, or investment plus net ‘hoarding’ in the period. . . . This is illustrated by [the following] Figure 7.
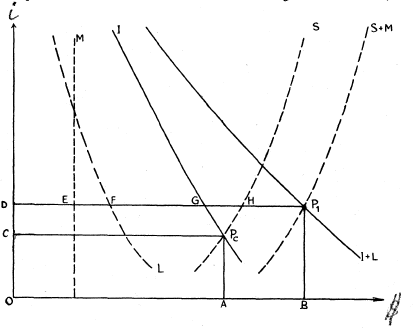
“S is the supply schedule of saving, showing how much would be saved (measured horizontally) at each rate of interest (measured vertically). I is the schedule of investment showing how much would be invested (measured horizontally) at each rate of interest. These two schedules intersect at Pc, the ‘classical’ point of equilibrium, which shows the rate of interest being determined at that level (APc) at which saving equals investment, both being equal to OA. L is the schedule showing the amount of net ‘hoarding’ that would take place at each rate of interest. In the figure, this is shown as a positive amount (i.e., at all the rates of interest considered, there would be a net balance of ‘hoarding’ and not a net balance of ‘dishoarding’) which is greater for lower rates of interest. There is no reason for expecting ‘hoarding’ always to outbalance ‘dishoarding’ in the economy, and this is taken to be so in the figure merely for the purpose of simplifying the diagram. ‘Hoarding’ could be taken as a negative quantity at some or at all rates of interest (and shown by the L curve falling to the left of the vertical axis’) without affecting the argument in any way.
“The M curve shows the increase in the amount of money in the period and is here shown as a positive amount and independent of the rate of interest. Both of these conditions are postulated merely for the purpose of simplifying the diagram. A decrease in the amount of money could be shown by drawing the M curve to the left of the vertical axis, signifying a negative increase in the amount of money. It might be the policy of the monetary authorities to take the rate of interest into account when deciding by how much to increase (or decrease) the amount of money. Thus if they increase the amount of money more (or diminish it by less), the higher is the rate of interest, then the M curve will slope upward to the right. But all such differences in assumptions would merely complicate the diagram without affecting our argument in any way.
“The M curve is now added horizontally to the S curve, giving the total net supply schedule of loans (or ‘credit’) marked S + M. The L curve is added to the I curve, giving the total net demand schedule for loans (or ‘credit’) marked I + L. The two new curves intersect at P„ giving an equilibrium into which the complications due to ‘hoarding’ and to changes in the amount of money appear to have been incorporated.”43
Let us draw a few corollaries from Professor OHLIN’S interpretation of ex ante saving and investment as schedules and their relation to the demand and supply curves of credit which determine the rate of interest. Obviously, it is not strictly permissible to speak in the singular of the difference between ex ante S and I. There is a whole schedule of such differences, showing what that difference would be at different hypothetical interest rates. If Professor OHLIN speaks of the difference, he probably refers to the equilibrium44 point, P1 in our diagram.
This point P1 in a sense denotes an ex post position; for it determines “the quantity of credit actually given”. At the rate of interest corresponding to that point, ex ante saving and ex ante investment need not be equal. In our figure, ex ante S exceeds ex ante I by GH. This difference is equal to the amount of money hoarded (DF) minus the increase in the amount of money (DE), GH being equal to EF.45
It should be observed that the diagram does not show savings and investment ex post; nor does it depict “the process”,46 set in motion by the ex ante difference between saving and investment, which brings about the equality ex post between saving and investment.
Relation between the ex ante and the period analysis.
Let us investigate a little more the foundation of Professor OHLIN’S theory and draw some further conclusions from it, not all of which have been stated by the author himself, probably for lack of space. We shall see that Dr. LUTZ’S contention is right,47 that the Swedish ex ante analysis, if thought through to its logical end, comes very near to Professor ROBERTSON’S period analysis. As Dr. LUTZ points out, in order to make use of the apparatus of demand and supply curves relating to credit, saving and investment, the period of time taken into consideration must be very short, at least so short that there do not occur any revisions of the various plans during the period.48 After the period has elapsed, people revise their plans in the light of the experience gained during the period; in other words, the curves relating to saving, investment, credit, etc., shift to new positions.
The choice of the length of the unit period which suits Professor OHLTN’S theory is not to be made on the basis of the same principles as the choice of the length of Professor ROBERTSON’S unit period.49 The latter, Professor ROBERTSON’S “day”, is chosen so as to make it impossible, in view of the existing habits of payment, that money received during the day should be spent during the same day; Professor OHLIN’S unit period rests on the postulate that plans should remain unchanged during the period.
Let us now concentrate on what happens during any unit period. Professor OHLIN draws for the credit market an analogy with a village market for eggs where people appear with “alternative purchases and sales plans” as represented in their demand and supply curves.50 It is not quite clear how far the author wishes to carry this analogy, but if he carries it sufficiently far by taking a very short period, his theory really coincides with that of Professor Robertson, for ex ante saving then becomes saving out of the income received on the day before. Perhaps he would not want to go so far, because ex ante saving would then no longer be savings out of a future, expected and uncertain income, but out of an income which has already been received. On the other hand, the alternative construction presents very serious difficulties. Clearly, if planned savings were to mean savings out of a future income, which might not materialise at all, it would not be possible to say that “the price of 3% bonds—and thus the long-term rate of interest—is fixed on the bond market by the demand and supply curves in the same way as the price of eggs or strawberries on a village market”51 and to explain that planned savings constitue a part of the demand for bonds.52 How can future savings constitute supply of credit and affect the bond market before they are actually made?53
We conclude that the most reasonable interpretation of Professor OHLIN’S concept of ex ante saving is “saving from disposable income”. This conclusion is fortified by the fact (stressed by Dr. LUTZ) that an excess of investment over saving has the same consequences in Professor These considerations illustrate a basic difficulty OHLIN’S scheme as in Professor ROBERTSON’S: in both cases, it has a stimulating effect and is a characteristic of an expansion of business (prosperity phase of the cycle).
If the foregoing interpretation of Professor OHLIN’S theory is correct—that is to say, if it does not exceed what can be deduced from his theory, although it contains more than he explicitly says—there remain certain inconsistencies and difficulties which call for further modifications of the theory.54
How can alternative purchase and sale plans be disappointed?
In so far and inasmuch as the actions of the individuals are determined by, and foreshadowed in, the various schedules, everything happens according to a plan—viz., to that one of the “alternative plans” of the various individuals which corresponds to the interest rate emerging as the actual market rate. Since Professor OHLIN identified the ex ante magnitudes with the alternative plans embodied in, or represented by, these schedules, it is difficult to see how he can speak of people’s being disappointed by events going contrary to their plans. It is said, for instance, that retailers may find themselves with greater stocks than they expected (unintentional investment); or with lower receipts than they anticipated (unintentional dissaving). Are their actions leading to these results—viz., either leaving the sale price unchanged (which entails the accumulation of stocks) or reducing the price (which entails losses and a reduction in saving)—not predetermined in their supply schedule? Everything happens according to the various schedules, and if all the possible plans of which Professor OHLIN speaks are embodied in these schedules, there can be no upsetting of the plans and no disappointment.
There are various ways out of this dilemma. The best, which rescues a maximum of Professor OHLIN’S theoretical edifice appears to be the abandonment of the identification of the ex ante concepts with the schedules mentioned. In other words, the plans which may be upset and the expectation which may be disappointed should be distinguished from what Professor OHLIN calls the “alternative purchase and sales plans” embodied in the various demand and supply schedules. The former stretch into the future, whilst the latter relate to a point or short period of time.
At any moment of time, a man may have (more or less consciously) alternative plans of action with respect to sales, purchases, savings, investment, borrowing, lending, etc., under different hypothetical prices, interest rates, etc., represented by various schedules. Nevertheless, he has probably been expecting for some time, more or less confidently, that one of these various possible situations would actually arise, or that the occurrence of some was more probable than of others. Moreover, he is likely to have acted in the past on the expectation that some things are more likely to happen than others: he has laid in stock or placed orders for the delivery of goods in the expectation that demand for, and the price of, his product will stand at a certain level; he has started certain constructions (investment) in the expectation that the situation in the loan market would enable him to borrow at a certain interest rate, etc. Hence the realisation of some of the situations foreshadowed in the instantaneous schedules of alternative actions will be in accordance with the long (or longer) range plans; the realisation of others will upset them. But events are still running according to schedule—that is, according to the instantaneous or short-run schedules.55
Mr. Hawtrey’s designed and undesigned investment.
Mr. HAWTREY’S distinction between “designed” or “active” and “undesigned” or “passive” investment is very similar to Professor OHLIN’S ex ante and ex post investment. Mr. HAWTREY refrains, however, from interpreting designed investment as schedules and thus avoids obscurities from which Professor OHLIN’S treatment suffers. The sum of designed and undesigned investment is total investment, which is defined as the “increment of unconsumed wealth” and is also called “saving”. (There is no distinction between “active” and “passive” saving in Mr. HAWTREY’S scheme.) Designed investment is defined as the voluntary acquisition of items of unconsumed wealth in the expectation that they will be remunerative; this is what Professor OHLLN calls “ex ante investment” Undesigned investment is defined as an “increment of unconsumed wealth, which is not acquired voluntarily in the expectation of its being remunerative; this will be an involuntary accumulation of unsold goods”—Professor OHLIN’S unexpected investment.56 “Passive investment” may be a negative quantity; that is to say, active investment may exceed saving, and the excess will be represented by an undesigned disinvestment or decrement of stocks of unsold goods. Thus active investment and saving (= net total investment) may be unequal. If they are, the resulting undesigned increment or decrement of unsold goods will be a source of disequilibrium, leading to a decrease or an increase in productive activity and possibly also in the price level.57
Saving and investment in Mr. Keynes’ system.
It remains to enquire why Mr. KEYNES finds it necessary to distinguish between saving and investment. We have seen that the formal definitions which he gives on page 63 of his General Theory are such that, for society as a whole, S and I are not only equal, but identical; viz., the value of un-consumed output. If that definition were strictly adhered to, S and I would be synonymous symbols, they could be used interchangeably and there would be no necessity—in fact it would be rather misleading—to retain both expressions.
Now this is not Mr. KEYNES’ practice. He uses both terms, deliberately and not for purely stylistic reasons. Moreover, he points out that the acts of saving and of investment are usually performed independently by different people.58 He insists that a process is required to make S and I equal, and sees the “initial novelty” of his theory in his “maintaining that it is not the rate of interest, but the level of incomes, which ensures equality between saving and investment”.59
He expressly rejects Mr. HAWTREY’S comment that S and I “are two different names for the same thing” and “that, in any sentence in which the word ‘investment’ occurs, the word ‘saving’ could be substituted for it without any change in the meaning”.60
The explanation given of the paradox that the two things, although identically defined, are not quite the same is this: S and I are different aspects of the same thing. They “are necessarily equal in the same way in which the aggregate purchases of anything on the market are equal to the aggregate sales. But this does not mean that ‘buying’ and ‘selling’ are identical terms, and that the laws of supply and demand are meaningless.”61
The total purchases of a commodity must be identical with the total sales of that commodity, but an individual’s purchases need not—and indeed are unlikely to—be equal to his sales of the same commodity. In the same way, total savings are identical with total investment, if we employ Mr. KEYNES’ definitions; but an individual’s savings need not be equal to his investment. It may be useful to retain the two separate terms “saving” and “investment”, since, even with Mr. KEYNES’ definitions; they are not necessarily equal when reference is made to an individual.
There is a second reason for the retention of the two terms. Although the total purchases of a commodity are equal to the total sales of that commodity, the motives of purchasers differ from those of sellers. In the same way, the motives for investment differ from those for saving; and the word “investment” may be used for the value of unconsumed income when the context refers to the motives of investors, while the word “savings” may be used for the same quantity when it is desired to emphasise the motives of savers.62
§ 3. HOARDING, LIQUIDITY PREFERENCE AND THE RATE OF INTEREST
The theory of interest has for a long time been a weak spot in the science of economics, and the explanation and determination of the interest, rate still gives rise to more disagreement among economists than any other branch of general economic theory.
The “pure” theory of interest.
For a long time, the theory of interest has had two distinct branches or stages. There is (a) the “pure” theory of interest in essentially non-monetary terms explaining the rate of interest as the price of capital, determined by the marginal productivity of capital in a technological sense and by certain psychological factors (time-preference) influencing the relative urgency of present and future needs; Professor MARGET63 calls these doctrines “real capital theories”. (That some writers, chiefly the followers of Böhm-Bawerk, go on to interpret marginal productivity of capital in terms of a lengthening or shortening of the period of production, whilst other writers object to that interpretation, has been mentioned on an earlier occasion.)64
The “loanable-fund” theory of interest.
We have (b) a monetary theory of the rate of interest which runs in terms of demand for and supply loanable funds or credit or claims. Elaborate attempts have been made at reconciling and integrating these two branches. In the Wicksellian and neo-Wicksellian literature—e.g., as reviewed above in Chapter 3—a detailed analysis is given of the mechanism by which, and the routes through which, pecuniary surface forces realise or falsify the fundamental relationship postulated by the “pure” theory of interest. One may very well hold that this integration has not been satisfactorily achieved, but one cannot say in justice that the problem has not been recognised.
The monetary theory of interest in terms of supply of and demand for loanable funds has to be regarded as a first approximation to a more elaborate treatment of the matter. It has been presented in the first edition of this book; it is the theory expounded by Professor OHLIN, as reviewed above in § 2 of this chapter (page 183). It is, as Professor ROBERTSON puts it, “a common-sense account of events” which attempts to give “precision to the ordinary view enshrined in such well-known studies of the capital and credit market as those of LAVINGTON65 and HAWTREY, as well as in a thousand newspaper articles”.66
This “common-sense” explanation of the rate of interest, and the more elaborate theory behind it, has been criticised by Mr. KEYNES and other writers. He has replaced it by a purely monetary theory, in which the rate of interest is completely divorced from the demand and supply of saving and explained instead by means of the “liquidity preference schedule” and the quantity of money.67
Mr. Keynes’ criticism of the “classical” theory of interest.
Before we analyse more closely Mr. KEYNES’ theory, we may clear the ground by reviewing the reasons, given by Mr. KEYNES and his followers, for rejecting the traditional theory of the rate of interest.
The greater part of Mr. KEYNES’ criticism in the chapter on “The Classical Theory of Interest”68 is directed against what we have termed above the “pure theory of interest” and, more particularly, against that version which explains the rate of interest by the interaction of demand and supply of saving or capital. Mr. KEYNES points out that there is no “material difference” between “the demand curve [for capital] contemplated by some of the classical waiters” and his “schedule of the marginal efficiency of capital or investment demand-schedule”.69 Against this demand curve, some classical writers set a supply curve of capital—that is, a curve showing how much saving (or capital) would be supplied at different hypothetical interest rates. The intersection of the two curves then determines simultaneously the rate of interest and the amount saved and invested.
Criticising this scheme, Mr. KEYNES rightly points out that the amount saved depends, not only on the rate of interest, but also on the level of income. In fact, most writers agree concerning the manner in which the rate of saving depends on the level of income: the higher the income level of an individual, the higher tends to be the amount saved.70 It is not so clear, on the other hand, how a rise in interest rates will affect the rate of saving.71
The propensity to consume in the short-run.
For short-run fluctuations, however, important qualifications must be made, even in respect of the first-mentioned relationship—viz., that between the amount of saving and the level of income. If we say that there is widespread agreement among economists to the effect that the amount of saving is positively correlated to the level of income, that refers to individuals—not necessarily to society as a whole, because of possible changes in the distribution of income—and under settled conditions. Especially in the case of rapid changes, the rate of change of income and recent fluctuations of the income level undoubtedly play an important rôle. If, for example, the income of a person rises unexpectedly, at first consumption may not rise at all; later on, the level of consumption will be gradually raised. Furthermore, expectations entertained by the individual about the level of income in future periods play a leading rôle and these expectations will be profoundly influenced by the history of recent fluctuations.72
Interdependence of demand for and supply of saving.
To return to the dependence of the rate of saving upon the level of income: for each income level, a separate curve showing how much would be saved at different interest rates ought to be drawn.73, 74 This being agreed upon, the next step in Mr. KEYNES’ criticism follows conclusively: the demand and supply curves of saving are not independent of one another. If, for instance, there appears a new stimulus to investment, if, that is to say, the investment demand curve shifts upward, income will, in general, rise and the supply curve of saving will shift too. Likewise, a shift in the latter will make the demand curve shift.
To sum up: the main defect of the “classical” theory of interest, according to Mr. KEYNES, is that it treats income as a given magnitude, as a determinant of the system and not as a variable.
If this criticism is valid as regards the static or equilibrium theory of interest,75 it would not appear to apply to the short-run or monetary theory of the rate of interest as developed by the followers of WICKSELL. In this theory, the variability of income depending upon the shifts in the investment-demand and saving-supply curve is not neglected; for a continuous and sustained change in income is an essential feature of the Wicksellian cumulative process. A rise in income is characteristic of an expansion process; a fall of income, of a contraction process. Moreover, this theory allows for the purely monetary influences on the rate of interest; indeed, these influences operating on the actual market rate of interest are, as we have seen in Chapter 3, the very essence of the theory.76
What, then, are Mr. KEYNES’ objections against the theory which conceives of the rate of interest as determined by demand for and supply of credit?
Criticism of the monetary theory of interest.
We are not here concerned with the concept of the “natural” or “equilibrium” rate of interest (as discussed in Chapter 3), but with the underlying explanation of the market rate by means of demand and supply curves of credit, as developed in Chapter 3, and more fully in § 2 of this chapter in elaboration of Professor OHLIN’S theory. We recall that demand for and supply of credit is not the same thing as demand for and supply of (ex ante) saving, but that the curves relating to the latter form a part of the curves relating to credit.
Objections are raised against that theory on the ground of its implying (a) that “saving is not necessarily equal to investment”, (b) that “the amount of money hoarded is not necessarily equal to the increase in the amount of money”. 77
The first of these two difficulties has already been discussed in § 2 of this chapter; it would appear to arise from the various possible meanings which may be attached to the terms “saving” and “investment”. If these terms are defined in the manner proposed by Professor ROBERTSON, the difficulty would seem to disappear, and Profesor OHLIN’S analysis, if carried to its logical conclusion, gives the same result.
The concept of “boarding”.
The second difficulty, concerning the term “hoarding”, requires careful consideration, because it has been an important source of confusion and misunderstanding in recent years.
The term “hoarding” is alien to Mr. KEYNES’ terminological system. It is used only when reference is made to theories of other writers. In such cases, however, it would seem that the term is used in two distinct senses, and the sense which, in most cases, is applied and attributed to other writers would seem to differ from the meaning attributed to it explicitly or implicitly by those writers themselves.
According to this definition, “net new hoarding” (in the sense of the amount hoarded; that is, of the result of this activity, “hoarding”, during a certain period) is the same thing as the increase in the quantity of money during that period. For, if an individual’s net hoarding in any period of time is defined as the addition which he makes to his holding of money during that period, the net hoarding of the whole community must be equal to the net increase in the amount of money in existence. “Dishoarding” (in the sense of the amount dishoarded) is the same thing as a decrease in the quantity of money. The total amount hoarded at any time “must be equal to the quantity of money”.78 “Holding money” and “hoarding money”are thus synonymous terms, and since all the money in existence at any moment of time is held by somebody—if it were not “held” by somebody (if, for example, it had been lost), it would not be counted as being in existence—all the money is always hoarded.
In a few cases, however, another definition is given of hoarding—viz.: “the quantity of money minus what is required to satisfy the transaction-motive” 79—in other words, idle or inactive money, including notes, coins and deposits or whatever is regarded as money. Net hoarding or dishoarding during a given period means, then, an increase or decrease of idle balances. This definition would seem to be roughly equivalent to the general meaning of the term.80 On some occasions, however, the two concepts are used interchangeably although what holds true of one of these concepts need not and will not be true of the other. In particular, the theory81 that any attempt of the public to hoard can only push up the interest rate, but cannot increase the aggregate amount hoarded unless the banking system increases the amount of money, is correct only if hoarding is defined in the wider (unusual) sense. If it is defined as an accumulation of idle balances, the public can hoard without any help from the banks. Even if the quantity of money is kept constant, the amount of idle balances can be increased by the public at the expense of active balances.
It is desirable, therefore, to define more precisely the meaning of the term and to state some of its implications and corollaries.
The concept of “idle balances”.
The concept of “idle balances” presupposes the assumption of some sort of an average or normal rate of turnover or velocity of circulation. For, in order to make the concept precise, it must be specified how long a balance is to remain idle, so that it should be regarded as falling under the category of “idle balances”. Overnight, all balances are idle, and over a sufficiently long period, all may have been active, in the sense of having been turned over.
People sometimes separate the balances which they keep “idle” from those which they “use”, by putting the former on savings or time accounts while keeping the latter on checking accounts. But such is not always the case and, if it is not, one cannot ascertain whether an individual or society as a whole has hoarded or not by comparing the amount of money held (by the individual or by all individuals) at different points of time. We may express this by saying that hoarding has a time dimension.
Hoarding and the velocity of circulation of money.
Hoarding and dishoarding thus means or implies a decrease or increase in the velocity of circulation of money V, or an increase or decrease in the reciprocal of V—that is to say, in the Marshallian82 k. Should we then say that “hoarding” (“dishoarding”) and “decrease (increase) of V” are synonymous terms? This is a terminological question which it is difficult to answer definitely on the basis of the general usage of the terms involved. Let us briefly and roughly consider the main forces responsible for changes in V (interpreting it, for the moment, as “transaction velocity”). V will change (a) if the habits of payment (e.g., the income period) change, (b) if, with stable habits of payment, some money is “withheld from circulation”, or (c) if money flows into spheres (say agriculture) or regions83 where its velocity of circulation is smaller than in those spheres or countries whence it came.
Some writers may prefer to reserve the term “hoarding” for such changes in V as are due to the factor (b), (or, perhaps, to (a) and (b)); they would then have to say that V is also subject to changes for reasons other than hoarding. To confine the term “hoarding” to phenomenon (b) would seem to correspond best to the definition of hoarding as the accumulation of idle deposits (unless the term “idle deposit” is given a rather wide meaning.) Suppose, for instance, that habits of payment so change that certain incomes which have been, so far, paid out in weekly instalments are, from now on, distributed in monthly payments. Assuming that before and after the change in the length of the income period has occurred, all money received is spent gradually during the respective income period, then the velocity of money is decreased, the money rests, on the average, longer in the pocket (or on the account) of the income receiver. Nevertheless, such deposits would presumably still be regarded as active, and not as idle, deposits.
The whole matter is, however, one of convenience and custom: one might just as well say that the deposits in question have become less active (that is, they are spent less frequently) and hence speak of an “act of hoarding”. But we need not here come to a definite decision or, rather, make a definite terminological proposal. Suffice it to call attention to the various possibilities.
From the point of view of the feasibility of statistical measurement, the definition of hoarding as equivalent to a change in V seems to be more convenient, because an actual separation of the influence on V of the three factors mentioned above will, in most cases, prove to be impossible.
Definition of hoarding by an individual.
One more word on the definition and measurement of hoarding by an individual (person, household, firm) may be in order. We shall say that an individual has hoarded (dishoarded) if the fraction 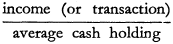 decreases (increases). It will be observed that this expression is the reciprocal of the Marshallian k.84 Hence, if an individual’s volume of transactions or income rises (falls) and his average cash holding rises (falls) in proportion, the individual neither hoards nor dishoards. If, for instance, somebody’s monthly income used to be $200, was received on the first of each month and spent evenly during the month, and if the income now rises to $400, which is again received on the first of each month and spent evenly during the month, the average cash holding per day has become twice as high as before; but no hoarding has occurred. The same is true if income and average cash holding fall pari passu. It is, of course, possible for a decrease in income to induce a person to dishoard—that is, to reduce his expenditure by less than his income and to deplete available cash resources. But looking at the average cash balance alone, we cannot tell whether hoarding or dishoarding has occurred or not. This point is frequently overlooked.85
Finally, it should be observed that the total amount which an individual or a firm is able to hoard during a given period is by no means always limited by the income received during this period or by net new saving. It would perhaps be better to refrain from saying that a part of income or of saving is hoarded and, instead, to speak only of the hoarding of money. But whether this terminological rule is observed or not, it should be clear that an individual (firm) may hoard, besides money income, all the money received from regular sales. We then speak of the hoarding of amortisation quotas and of working capital. In addition an indi. vidual may sell any asset in his possession and hoard the proceeds-Or he may borrow (sell claims) and hoard the proceeds of the loan.86
We can pass now to Mr. KEYNES’ theory of the rate of interest and investigate whether or not it is compatible with the traditional views.
The definition of the rate of interest.
Mr. KEYNES holds that the rate of interest, contrary to the traditional view, according to which it is “the reward of not spending” (on consumption), is “the reward of not hoarding”,87 “the reward for parting with liquidity for a specified period”.88 It “is a measure of the unwillingness of those who possess money to part with their liquid control over it. The rate of interest is not the ‘price’ which brings into equilibrium the demand for resources to invest with the readiness to abstain from present consumption. It is the ‘price’ which equilibrates the desire to hold wealth in the form of cash with the available quantity of cash.”89
However, as Professor ROBERTSON 90 and others have pointed out, one alternative would not seem to exclude the other: the rate of interest may well be regarded as a reward both for not-consuming and for not-hoarding. In order to earn interest, one must normally refrain not only from keeping money idle (from hoarding it), but also from spending it for consumption. But the first (Mr. KEYNES’) condition is, perhaps, less essential than the second. As everybody knows, banks sometimes pay interest on demand deposits. If, then, hoarding takes the form of keeping idle deposits (rather than notes or coins), it does not preclude their earning interest on the amount hoarded, and the rate of interest cannot be said to be the reward for hoarding. It is true that the rate of interest on demand deposits is usually lower than the rate on time deposits or the bond rate. But this is not necessarily so; we can easily conceive of a situation where we have the same rate for all kinds of assets, and there have been instances when short-term rates of interest have been higher than long-term rates. Hence, the deposit rate (reward for hoarding) may be higher than, for instance, the bond rate (reward for parting with liquidity).
About the definition of the rate of interest, there is no real difference of opinion. Everybody means the same by “rate of interest” (at least, by the “explicit” rate of interest)—viz., “the price of debt”91 or of a loan which is evidently the same as a debt.92 Disagreement arises only when it comes to explaining the factors which determine the level of and fluctuations in the rate of interest.
Liquidity preference demand for money.
How does Mr. KEYNES’ theory in this respect differ from the traditional views? According to Mr. KEYNES, the rate of interest is the resultant of two factors: liquidity preference and the quantity of money. “Quantity of money” we can translate by “supply of money” The money is taken as fixed by the monetary authorities, or the banking system, according to some principles of monetary policy. It may conceivably be a function of the rate of interest—that is, the banks may, for example, pursue the policy of expanding the supply when the rate of interest rises. But, usually, this is not the case. It should be noted that by “supply of money”, Mr. KEYNES means the total supply for all purposes and not the supply of loanable funds alone. In this latter sense, the term “supply of money” is frequently used in the financial literature on the “money” market.
It is not so easy to interpret the term “liquidity preference”.93 “The subject is substantially the same as that which has been sometimes discussed under the heading ‘Demand for Money’.”94 Hence we may formulate: the rate of interest is determined by demand for, and supply of, money rather than by demand for, and supply of, saving or credit (loans).
At first sight, this theory seems indeed revolutionary and to run counter to many well-established doctrines. This impression is strengthened by Mr. KEYNES’ apparent denials that an increase in the rate of saving, ceteris paribus, tends to lower the rate of interest; that a rise in the marginal efficiency of capital (demand for loanable funds) resulting, say, from a new invention or from a turn of the general sentiment towards optimism tends, ceteris paribus, to raise the rate of interest.95 He seems to imply, furthermore, that any increase in the quantity of money, ceteris paribus, tends to depress the interest rate (at least in the first instance, notwithstanding indirect and psychological repercussions).
A more careful analysis of what is meant by “liquidity preference” or “demand of money” will show, however, that the real difference between Mr. KEYNES’ theory and the theory which explains the rate of interest and its daily fluctuations by the interaction of demand for and supply of credit or loans (not saving) is not so great as may at first sight appear. A fundamental disagreement seems to arise, mainly because hidden assumptions are overlooked, especially those which are covered by the ceteris-paribus clause. The “other things” which are assumed to remain unchanged are not the same for all writers. Hence their disagreement is frequently due to their failure to realise the fact that they start from different assumptions, rather than to the fact that they arrive at different conclusions under the same set of assumptions.
Three motives for holding money.
Mr. KEYNES distinguishes three motives for holding money: (i) the transactions-motive, (ii) the precautionary-motive and (iii) the speculative-motive. The transactions-motive is defined as “the need of cash for the current transactions of personal and business exchanges”96 and is split up into the “income-motive and business-motive”.97 “One reason for holding money is to bridge the interval between the receipt of income and its disbursement . . . and, similarly, the interval between the time of incurring business costs and that of the receipt of sales proceeds.”98 In other words, a certain amount of money is required to “handle” a certain income and a certain volume of transactions. How much money is needed depends on the velocity of circulation of money and is determined by the habits of payment and other factors which have been touched upon in an earlier chapter, where references to the relevant literature are to be found.99
The precautionary-motive is described as the desire to hold cash “to provide for contingencies requiring sudden expenditures and for unforeseen opportunities of advantageous purchases”.100 Mr. KEYNES assumes that the amount of money needed for this purpose, as well as the amount needed for transaction purposes, depends on, and varies with, changes in the actual level of activity (more precisely, volume of transactions).
By the speculative-motive, Mr. KEYNES means the inducement to hold money for the purpose “of securing profit from knowing better than the market what the future will bring forth”.101 If, for instance, one expects the price of debt (e.g., of bonds) to go down—that is, the rate of interest to rise—one will try to change from debt to money, to sell bonds and hold money. Mr. KEYNES believes that “general experience indicates that the aggregate demand for money to satisfy the speculative-motive usually shows a continuous response to gradual changes in the rate of interest—i.e., there is a continuous curve relating to changes in the demand for money to satisfy the speculative-motive and changes in the rate of interest as given by changes in the price of bonds and debts of various maturities”.102
Hoarding and the rate of interest.
Mr. KEYNES believes, furthermore, that it is roughly true that the total amount of money, M, can be divided into two parts, M1 and M2, of which the first part, M1, is held to satisfy the transactions and precautionary-motives and the second part, M2, to satisfy the speculative-motive.103 M1 may thus be called active or circulating money, whilst M2 is hoarded or idle or inactive money. M1 varies with the level of income or, rather, with the volume of transactions. M2 depends on the interest rate in such wise that it rises when the interest rate falls and falls when the interest rate rises.
This would seem to be the most important new relationship introduced by Mr. KEYNES; new, not in the sense that it has never been suggested in the literature, but in the sense that it has never been carried through consistently. We may formulate this theorem also by saying that hoarding tends to be stimulated by a fall, and checked by a rise, in interest rates. Hoarding becomes cheaper when interest rates fall, and costly when they rise. In still other words, we may say that the velocity of circulation of money104 is positively correlated to the rate of interest.105
It will be convenient in the following analysis to distinguish sharply between liquidity preference in the wider sense and in the narrower sense. By the former, we mean the demand for money for all purposes, inclusive of the transaction purpose (M1 + M2); by the latter, demand for idle balances, M2, alone. The narrower definition corresponds better to the everyday meaning of the term “liquidity preference”. We shall therefore call it “liquidity preference proper” If somebody sells an asset against money and keeps the proceeds idle or if he refrains from spending all his money receipts as usual, we may describe that as an increase in his liquidity preference. Suppose, on the other hand, that wages rise but interest rates remain constant because the banks increase the money supply; then the average cash holdings of the working population will rise, and we have to describe that in Mr. KEYNES’ terminology as a rise in liquidity preference in the wider sense: more money is held for transaction purposes.106
This terminology does not appear to be in accord with everyday language.
Let us now consider how far Mr. KEYNES’ liquidity-preference theory and the traditional demand-for-and-supply-of-loanable-funds theory of interest are really at variance.
How a rise in investment demand influences the interest rate.
Take, first, an increase of the demand for capital—that is, in Mr. KEYNES’ terminology, an upward shift of the schedule of the marginal efficiency of capital, which is characteristic of the prosperity phase of the business cycle. Suppose an increase in consumers’ expenditure (however brought about) or improved expectations or inventions make entrepreneurs eager to invest. They demand investible funds, and, according to the traditional views, that will tend to drive up interest rates.
In spite of the impression to the contrary, this is not in contradiction with Mr. KEYNES’ theory. We have only to translate what we have just said into his terminology. There are, in fact, two possibilities. First, if an entrepreneur borrows additional money from the market in anticipation of a future increase in his expenditure for investment purposes,107 this represents an increase in his liquidity preference, for his demand for money has increased without either a fall in interest rate or, as yet, a rise in the volume of transactions. But, secondly, the entrepreneur may borrow additional funds no quicker than he spends additional funds on the increased investment. In this case, as indeed in the previous case also, there will be a rise in the volume of business transactions, and this will lead, sooner or later, to an increased demand for money to finance the larger turnover. This will involve a rise in interest rates, according to Mr. KEYNES, because less of the existing supply of money will remain available to satisfy the speculative motive for liquidity.
In either case, therefore, if the supply of money does not rise, the rate of interest must go up. This qualification about the supply of money cannot give rise to any disagreement, for it will be accepted by the adherents of the traditional views. All agree that, in spite of an increase in demand for loanable funds, the interest rate will not go up if (a) the banks supply the necessary funds or (b) the public supplies them by dishoarding at unchanged interest rates.
Case (a) has been recently described by Mr. KEYNES, alternatively, as an increase of the willingness of the banking system to become illiquid, which cancels the rise in the liquidity preference of the public. “One could regard the rate of interest as being determined by the interplay of the terms on which the public desires to become more or less liquid and those on which the banking system is ready to become more or less illiquid.”108 Apart from terminological differences, therefore, this theory and the loanable-fund (in this case bank-fund) theory would seem to be almost identical.
In Mr. KEYNES’ terminology, case (b) would have to be construed as a decrease in the liquidity preference of those who are “willing to release cash”109 which cancels the increase in the liquidity preference of the entrepreneurs and thus leaves the interest rate constant.
When the entrepreneurs then spend the money on wages, etc., they become less liquid (their liquidity preference decreases), but the successive recipients of the money become more liquid (their liquidity preference increases). This can also be expressed by saying that income (or transactions), which is one source of the demand for money, goes up. More money is needed to satisfy the transactions-motive, and this drives up (or keeps up) the interest rate, unless less money is needed for satisfying the speculative-motive—in other words, unless somebody “releases cash” (that is, dishoards).
Planned investment and interest rates.
In a recent contribution, “The ‘Ex-Ante’ Theory of the Rate of Interest”,110 Mr. KEYNES has modified, and elucidated, his theory in a way which makes its similarity with the loanable fund theory still clearer. In his General Theory, he explained that the demand for money depended on the rate of interest (determining the demand for idle balances) and on the actual level of activity (determining the demand for circulating balances). This, it is now admitted, was an incomplete statement. “The additional factor, previously overlooked, to which Professor OHLIN’S emphasis on the ex-ante character of investment decisions has directed attention, is the following.”111 There is a third factor affecting the demand for money—viz., the necessity of providing what Mr. KEYNES proposes to call “finance” for planned investment. Before activity has actually gone up, funds for the intended outlay must be secured. “During the interregnum—and during that period only—between the date when the entrepreneur arranges his finance and the date when he actually makes his investment, there is an additional demand for liquidity without, as yet, any additional supply of it necessarily arising” (page 665). The adherents of the loanable-fund theory would merely substitute “credits” for the word “liquidity” in this sentence.
Mr. KEYNES rightly points out that this additional demand must meet with additional supply, if the rate of interest is not to rise. Somebody, the banks or the public, must “deplete their existing cash” (page 666), and he criticises Professor OHLIN for suggesting that ex-ante saving out of future income can satisfy the demand for finance. This is the same criticism as was made above when it was said that ex ante saving in the sense of saving out of a future income cannot affect the bond market now. This criticism loses its validity, however, if ex-ante saving is interpreted, as was suggested above, in the Robertsonian sense, as saving out of a previously received income. The demand for finance can be satisfied by increased saving in this sense or by dishoarding. Both sources can be described (in Mr. KEYNES’ words) as a depletion of existing cash—cash from idle balances or, in the case of additional savings, cash released from transactions balances by the reduced expenditure on consumption goods.
One point regarding Mr. KEYNES’ theory of “finance” has given rise to an interesting discussion which throws much light on the whole issue.112 It is Mr. KEYNES’ insistence that “finance is essentially a revolving fund . . . . As soon as it is ‘used’ in the sense of being expended, the lack of liquidity is automatically made good and the readiness to become temporarily unliquid is available to be used over again.”113
Professor ROBERTSON objected that finance funds which have been spent can be made available for new financing only if they are saved (in Professor Robertson’S sense) by one of the successive recipients. Mr. KEYNES’ reply clearly indicated that there is no disagreement except a terminological one, due to the different definition of the concept of saving. Mr. KEYNES explains: “The demand for cash falls away unless the completed activity (associated with the expenditure of the finance funds) is being succeeded by a new activity.”114 It would appear that this condition might well be accepted by Professor ROBERTSON: for the primary activity will be succeded by a new one, if the money is again spent on consumption; if it is saved, the “chain of activities” is interrupted, the demand for cash falls away unless the saving leads to a fall in interest rates which stimulates investment, or unless the marginal efficiency of capital rises—changes which are excluded by Mr. KEYNES’ ceteris-paribus assumption.
The influence of saving on the rate of interest.
On the question whether an increase in saving (a fall in the propensity to consume) affects the rate of interest or not, Mr. KEYNES’ views still seem to be very different from the traditional views. He expresses the difference in principle between his and the traditional view as follows. Economists have “almost invariably . . . assumed . . . that, ceteris paribus, a decrease in spending will tend to lower the rate of interest and an increase in investment to raise it. But if what these two quantities determine is not the rate of interest, but the aggregate volume of employment, then our outlook on the mechanism of the economic system will be profoundly changed. A decreased readiness to spend will be looked on in a quite different light if, instead of being regarded as a factor which will, ceteris paribus, increase investment, it is seen as a factor which will, ceteris paribus, diminish employment.”115
Some misunderstanding seems to have arisen in this connection from different interpretations of the ceteris-paribus clause. The classical writers, when they are not dealing with money and the business cycles, are in the habit of taking total monetary outlay as constant; it is included in the cetera that remain the same. Then a decrease in one division (consumption spending) implies an increase in the other (investment). Assuming the marginal efficiency of capital to be constant, this implies a fall in the interest rate. Mr. KEYNES, on the other hand, includes liquidity preference among the other things that remain unchanged; then, since M has remained unchanged, the rate of interest cannot fall.116
Now the loanable-fund theorists would not deny that this might happen, but they would describe it differently: people may hoard the money which they fail to spend. In Mr. KEYNES’ theory, this has to be described as a rise in liquidity preference proper;117 demand for money for “speculative purposes”, M2, has risen. This implies a decrease in M1, which is connected with the fall in activity. Thus total demand for money and the quantity of money remaining unchanged, the rate of interest remains unchanged too.
If, however, the producers of consumers’ goods who experience a decrease in demand try to maintain activity by selling securities, the rate of interest will rise, and these sales will have to be construed as an increase in their liquidity preference.
There may be a difficulty in the timing of the processes; it is, however, clearly possible to conceive of a case where people spend less on consumption (save), but direct the money simultaneously to the purchase of new securities.
It would appear from the foregoing discussion that Mr. KEYNES’ views on the question of how the rate of interest is influenced by changes in the propensity to consume (save)118 are not so radically different from the views of other authors as may at first sight appear. In a very recent exposition of his theory, Mr. KEYNES has himself suggested this.119 “The analysis which I gave in my General Theory of Employment is the same as the ‘general theory’ by Dr. LANGE on page 18 of his article.”120 On this page, Dr. LANGE states that “the traditional statement that the rate of interest . . . moves in the opposite direction to the propensity to save holds fully in our generalised theory”.121
Changes in M and the rate of interest.
There remains one more case in respect of which the liquidity-preference theory seems to be at variance with the traditional views—viz., the effect of an increase in the quantity of money on the rate of interest. It would seem that, according to Mr. KEYNES, such an increase must always lead to a fall in the rate of interest. This is, however, not Mr. KEYNES’ view, because in many cases, such an increase will, automatically and uno actu raise the liquidity-preference schedule. “Suppose that M consists of gold coins and that changes in M can only result from increased returns to the activities of gold-miners. . . . In this case, changes in M are, in the first instance, directly associated with changes in Y, since the new gold accrues as someone’s income. Exactly the same conditions hold if changes in M are due to the Government printing money wherewith to meet its current expenditure;—in this case also, the new money accrues as someone’s income.”122 The increased level of income represents increased demand for money; hence the increased M does not lead at once to a rise in the rate of interest.
“The new level of income, however [Mr. KEYNES elaborates], will not continue sufficiently high for the requirements of M1 to absorb the whole of the increase in M; and some portion of the money will seek an outlet in buying securities or other assets until the rate of interest has fallen so as to bring about an increase in the magnitude of M2 and, at the same time, to stimulate a rise in Y to such an extent that the new money is absorbed either in M2 or in the M1 which corresponds to the rise in Y caused by the fall in the interest rate. Thus at one remove this case comes to the same thing as the alternative case where the new money can only be issued in the first instance by a relaxation of the conditions of credit by the banking system”, and thus automatically entails a fall in the interest rate.123
This passage calls for some comments. The statement that “money will seek an outlet in buying securities” must surely imply that the recipients of the money whose incomes have risen save a part of it, in Professor ROBERTSON’S sense? In this case, saving will reduce the rate of interest, although that entails part of the money going into hoards (increases the magnitude of M2). If people did not save, but spent all the new money on consumption, M1 would still absorb the whole increase in M.
The course of events might presumably differ from the one which Mr. KEYNES described: thus the increase in Y might stimulate investment, and this might more than compensate the tendency to a fall in the interest rate. Indeed, it is impossible to say what the outcome will be. But it is clear that Mr. KEYNES’ theory does not imply that an increase in the quantity of money must in all circumstances entail a fall in the interest rate, and that its stimulating effect is conditioned by its having previously depressed the interest rate.124
Apart from terminological innovations, the real contribution brought by Mr. KEYNES’ General Theory of Interest would seem to consist, as we have seen, of the proposition that hoarding is a function of the rate of interest. This does not of course mean that factors other than the rate of interest may not also exert an influence as strong as that of the interest rate on the amount of inactive balances. In other words, even in the short run, shifts of the liquidity-preference schedule may be at least as important as movements along the curve.125
Infinite elasticity of demand for idle balances.
Besides and in addition to the general empirical assumption about “demand for idle cash balances” (propensity to hoard), there is a more specific assumption about the shape of that demand curve (liquidity-preference schedule proper) which frequently plays an important rôle in Mr. KEYNES’ theory. This more specific assumption constitutes Mr. KEYNES’ “special theory”, as Dr. Hicks has aptly called it.
This assumption is to the effect that, for low interest rates, “say 2%” (page 202), the demand for idle balances (“demand for liquidity”) becomes more and more elastic and, at a rate well above zero, absolutely elastic—that is, insatiable. In technical parlance, the interest-elasticity of the demand for liquidity becomes infinite:126 the schedule of liquidity preference proper becomes horizontal. It is very important to realise that this is equivalent to saying that, when this critical level of interest rates has been reached, any amount of money which might be created by the banks will be hoarded, in addition to any amount which people save in excess of the current demand for investment purposes (in Mr. KEYNES’ terminology, we should rather say: any amount of money which is released from balances held for business or income purposes). Suppose, for instance, that, at the depth of a depression, investment demand for loanable funds is at a low ebb, and that the rate of interest has reached that critical level of (say) 2%; suppose, moreover, that there is a reasonable degree of competition, so that wages and prices continue to fall so long as there is unemployment: then money is constantly released from the transaction sphere. But instead of being directed to the acquisition of assets, thus driving up their prices (which is equivalent to reducing the interest rate) and stimulating investment and employment, all this money is being hoarded. Hoards grow without limit in terms of money and, because of the fall in prices, still faster in real terms.
A limit to the fall in interest rates.
If such a situation exists,—i.e., if the demand for money-to-hoard (liquidity preference curve proper) is perfectly elastic— “a rise in the schedule of the marginal efficiency of capital only increases employment, and does not raise the interest rate at all”.127 Likewise, a rise in the rate of saving (propensity to consume) decreases employment without decreasing the rate of interest. The idea that such a situation might arise is original and is of considerable theoretical interest.
Let us ask how, according to Mr. KEYNES, such a situation could come about, and whether, according to him, it has ever arisen.
The reason for the existence of a minimum, below which the rate of interest cannot possibly fall, we may paraphrase in the words of Dr. HICKS: “If the costs of holding money can be neglected, it will always be profitable to hold money rather than lend it out, if the rate of interest is not greater than zero. Consequently, the rate of interest must always be positive. In an extreme case, the shortest short-term rate may perhaps be nearly zero. But if so, the long-term rate must lie above it, for the long rate has to allow for the risk that the short rate may rise during the currency of the loan, and it should be observed that the short rate can only rise, it cannot fall. This does not only mean that the long rate must be a sort of average of the probable short rates over its duration, and that this average must lie above the current short rate. There is also the more important risk to be considered—that the lender on long term [e.g., bondholder] may desire to have cash before the agreed date of repayment, and then, if the short rate has risen meanwhile, he may be involved in a substantial capital loss.”128 Thus, in the words of Mr. KEYNES, “the rate of interest is a highly conventional phenomenon. For its actual value is largely governed by the prevailing view as to what its value is expected to be.”129 The argument is perhaps more intelligible when put in terms of asset prices (e.g., bond prices) instead of interest rates. If asset prices are expected to fall (long-term rates to rise), asset prices cannot remain at a level much higher than the expected price, because people would prefer, to keep their resources in cash, in spite of very low short rates.130
Weighty arguments against the assumption that the expected rate of long-term interest (asset prices) is likely to persist unchanged for any length of time, in spite of a fall in the current short-term rate, have been brought forward by Mr. HAWTREY.131 We need however, not go into this matter more thoroughly, because Mr. KEYNES himself (quite rightly, it would seem) believes that this contingency of an “absolute liquidity-preference” is a theoretical possibility which has actually not yet arisen. “But whilst this limiting case”, in which “the monetary authority would have lost effective control over the rate of interest” (and in which, we may add, no fall in wages and prices could depress the rate of interest by releasing money from the transaction sphere), “might become practically important in future, I know of no example of it hitherto. Indeed, owing to the unwillingness of most monetary authorities to deal boldly in debts of long term, there has not been much opportunity for a test.”132 Nor, we may add, has the alternative to a policy of increasing the quantity of money—viz., a sustained fall of all prices and wages—been put to a real test.133
Summary.
An almost perfectly elastic demand for idle balances up to a very considerable amount may occasionally occur, and has occurred temporarily (Mr. HAWTREY’S temporary credit deadlock), but the hypothesis that it may exist indefinitely has not yet been put to the test of fact.134
§ 4. THE “MULTIPLIER” AND THE “MARGINAL PROPENSITY TO CONSUME”
The “psychological” determinants of Mr. Keynes’ system.
“Three fundamental psychological factors—namely, the psychological propensity to consume, the psychological attitude to liquidity and the psychological expectation of future yield from capital assets”(which govern, together with “the given factors” capital equipment, etc., the marginal efficiency of capital or demand for capital)135—constitute the skeleton of Mr. KEYNES’ theoretical system which “determines the national income and the quantity of employment.” Mr. KEYNES is careful to explain that these psychological propensities (together with some non-psychological factors such as the wage unit and the quantity of money) can only “sometimes” be regarded as the “ultimate independent variables” (page 246). He recognises that they are “themselves complex and that each is capable of being affected by prospective changes in the others”136 and, presumably, a fortiori, by actual changes in the others. (Thus we have seen that the liquidity preference is influenced by actual and prospective changes in the marginal efficiency of capital.)
As will be illustrated by various examples in the following pages, we have here a source of frequent misunderstandings. Those who have become accustomed to think in terms of Mr. KEYNES’ system take the determinant propensities, the wage unit,137 etc., as given, and regard them as independent from one another, whilst other writers, brought up in traditional modes of thought, frequently make assumptions which imply a mutual influencing of Mr. KEYNES’ determinants, or treat some of them as variables. These differences in the starting-point are concealed by differences in terminology.
Marginal efficiency of capital (demand for capital) and liquidity-preference having been discussed, we now turn to an examination of the concept “marginal propensity to consume” and the closely related “multiplier”.
The problem of the “multiplier”.
Mr. KEYNES considers the theory of the so-called “multiplier” “an integral part of his theory of employment” (page 113). The multiplier—k— “establishes a precise relationship, given the propensity to consume, between aggregate employment and income and the rate of investment” (page 113). “It tells us that, when there is an increment of aggregate investment, income will increase by an amount which is k times the increment of investment” (page 115): ΔY = k ΔI, and ΔY = ΔC + ΔI, if by ΔY, ΔI and ΔC we denote small increments of income, investment and consumption respectively. (We need not go into the question of the unit in which these magnitudes are expressed. Mr. KEYNES discusses this question carefully and elects to express all these magnitudes in “wage units.” We may, however, think of them just as well in “real” terms or in terms of money.) “The fundamental notion” underlying the theory is that, if “we conceive the monetary or other public authority to take steps to stimulate or to retard investment, the change in the amount of employment” will not be confined to the investment industries, but will extend to the consumption industries and “will be a function of the net change in the amount of investment”; and the theory aims “at laying down general principles by which to estimate the actual quantitative relationship between an increment of net investment and the increment of aggregate employment which will be associated with it” (pages 113 and 114).
The pure theory of the “multiplier”.
The pure theory of the multiplier consists of the establishment of a precise relationship between the multiplier and the marginal propensity to consume. The propensity to consume is defined as the functional relationship between “a given level of income” and “the expenditure on consumption out of that level of income” (page 90). The marginal propensity to consume is then the relationship between an increment of income and the expenditure on consumption out of this increment. It is measured by  which is always smaller than unity, because “the normal psychological law” holds that, “when the real income of the community increases or decreases, its consumption will increase or decrease, but not so fast” (page 114).138 The marginal propensity to consume “tells us how the next increment of output will have to be divided between consumption and investment” (page 115). A marginal propensity to consume of, for example,
 means that of the next increment of income will be consumed. If the marginal propensity to consume is 1, the whole increment will be consumed; if it is zero, the whole will be saved. It follows that the (marginal) propensity to save has to be defined as 1 minus the (marginal) propensity to consume. If the latter is , the former is
 , this being the proportion (of the next increment) of income saved. If the marginal propensity to consume is 1, the marginal propensity to save is zero; if the former is zero, the latter is 1.
It should be kept in mind that the terms “propensity to consume (save)” and “marginal propensity to consume (save)” are usually used in the schedule sense—that is to say, they usually denote the whole schedule, showing what proportion of different hypothetical incomes or increments to income an individual or society as a whole would consume (save). Sometimes, however, when speaking of the propensity to consume, reference is made to a particular point (mainly the point actually realised) on the schedule of alternatives. Although it will usually be clear from the context in what sense the word is used, it would be better to speak, when not referring to the schedule as a whole, of “the rate of consumption (saving)”139 or, better still, of “the proportion of income consumed (saved)
What is the relation between the marginal propensity to consume and the multiplier? The relationship is quite simple:
ΔY = kΔI

Since ΔY = ΔC + ΔI
Thus, the multiplier k is, by definition, equal to 1 divided by 1 minus the marginal propensity to consume; and the marginal propensity to consume, is equal to  Since
 is the marginal propensity to save, we can also say that the multiplier is the repicrocal of the marginal propensity to save, and vice versa. We have thus three interchangeable expressions for the same thing. The expression “marginal propensity to consume” can always be replaced, without a charge in meaning, by the expression “1 minus the marginal propensity to save” or by “1 minus the reciprocal of the multiplier”.
It follows that if, for instance, the marginal propensity to consume is (the marginal propensity to save being ), the multiplier is 10; “the total employment caused (for example) by public works will be ten times the primary employment provided by the public works themselves, assuming no reduction of investment in other directions” (pages 116 and 117). This result is clearly implied by the assumption made. If we assume that an increment in Y is divided in the proportion of 1: 9 between I and C, then we assume that an increase in I by x units will mean an increase of 9x in C and an increase of 10x in Y. If we assume the marginal propensity to consume to be zero—in other words, that an increment in Y is wholly confined to I—then we assume that an increment in I increases Y by no more than its own amount. If the marginal propensity to consume is assumed to be 1—that is, if we assume that “the next increment of output will have to be divided between consumption and investment” in the proportion of 1 to 0—then, in order not to contradict that assumption, we must assume that any increase in I is accompanied by an infinite increase in C and Y: the multiplier is infinitely high. In plain English, there can be no increase in I.
It will be well to keep in mind the logical nature of the “pure theory of the multiplier”140 which is clearly revealed by the foregoing discussion. The theory is not intended by Mr. KEYNES as a statement about a relationship in the real world between two distinguishable phenomena; there are not two facts, the marginal propensity to consume on the one hand, and the multiplier on the other, of which the former influences and governs the latter. The logical theory of the multiplier establishes a terminological rule for the use of the two terms “marginal propensity to consume” and “multiplier” and nothing more.
The practical problems behind the multiplier.
The practical problem to the solution of which the theory of the multiplier and the attempts at a statistical measurement of its magnitude are directed is the determination, if possible in advance, of the indirect effects of Government expenditure on public works and the like. The underlying idea is that, if the Government spends several hundred million dollars on public investment and thereby creates additional employment, the first recipients of the money will spend at least a part of their income on consumption; the consumption industries will be stimulated; the money will be spent again and again; and a whole series of successive income- and employment-creating expenditure will emanate from the first investment. The question is, how big will be the secondary, tertiary, etc., effects flowing from the primary investment of a given magnitude?141 For the reasons given below, the pure theory of the multiplier cannot provide a final answer to that question.
The problem of determining “net investment”.
(1) The multiplier refers to the effect of an increment of net investment. Hence, as Mr. KEYNES states, “if we wish to apply [the theory of the multiplier] without qualification to the effect of (for example) increased public works, we have to assume that there is no off-set through decreased investment in other directions” (page 119). In other words, a concrete amount of public works cannot, without examination, be accepted as net new investment; the public works policy may have unfavourable repercussions on private investment (a) by raising prices of material and labour; (b) by raising the interest rate, because of the method of financing employed; (c) owing to repercussions “through psychology”, if a Government deficit shakes confidence; (d) through unfavourable influences on the international balance of trade and payments.
Some of these factors have been discussed by Mr. KEYNES (General Theory, pages 119 to 121), Mr. KAHN (loc. cit.), and by other writers in the considerable recent literature on expansionist policies in general and public works in particular.142
Secondary investment.
(2) Mr. KEYNES speaks only of “adverse reactions on investment” of a public works policy, but it may have favourable reactions too. Indeed, it is generally considered as a condition of success of a “pump priming policy” that it should stimulate private investment. Public investment may stimulate private investment either directly or by first stimulating consumption.143 All this is now well known and has been thoroughly discussed, but it all lies outside the pure theory of the multiplier.
The propensity to consume for society as a whole.
(3) But the theory of the multiplier needs to be expanded and qualified in other ways. By expressing the multiplier in terms of the marginal propensity to consume, the impression is conveyed that it is possible to base the analysis on a fairly stable psychological magnitude. People’s habits as to saving and spending are regarded as fairly constant, and this constancy and stability is transmitted by definition to the multiplier. A closer examination reveals, however, that this stability may be exaggerated. Mr. KEYNES speaks frequently of “the fundamental psychological law, upon which we are entitled to depend with great confidence both a priori from our knowledge of human nature and from the detailed facts of experience”;144 this law is to the effect that “men are disposed . . . to increase their consumption as their income increases, but not by as much as the increase in their income”. He refers to the consumer, and sometimes to society as a whole. But the marginal propensity to consume of society as a whole (which corresponds to the multiplier) cannot be identified with a psychological law about the behaviour of the individual consumer, for many other factors besides the consumers’ behaviour determine the marginal propensity to consume of the society.
For a number of reasons, the stability of the multiplier must not be over-emphasised.
(a) As has been pointed out above (page 198), in the short run, the psychological traits of the individual in respect to saving and spending cannot safely be regarded as constant.145
Changes in income distribution.
(b) As Dr. STAEHLE146 has shown, changes in the distribution of income are very important for the propensity to consume of society as a whole, even from the short-run point of view. Since the propensities for different people or groups of people are different, a change in the distribution may give an unexpected turn to the marginal propensity to consume of society as a whole (contrary to the fundamental psychological law), even if the propensity of each individual is constant and conforms to “the fundamental psychological law”, to which Mr. KEYNES appeals. For this reason, in using the concept of the multiplier, allowance must be made for the changes in the distribution of income which are likely to be associated with a change in the level of incomes.
(c) Laws relating to consumers’ behaviour cannot be directly applied to collective magnitudes, because what society as a whole invests and consumes is determined also by decisions of big corporations and of public bodies which cannot be so confidently assumed to be subject to the “fundamental psychological law” on which Mr. KEYNES depends for his empirical generalisations. In making use of the multiplier, allowance must be made for the proportion of any additional profit which companies are likely to save by adding to their reserves.
Government consumption and investment.
Moreover, with respect to public expenditure, the distinction between consumption and investment is in many cases very arbitrary. Expenditure connected with the construction of battleships, river-dams and the like will be classified as investment. Dole payments to unemployed and expenditure for war veterans’ bonus will be counted as consumption expenditure and, if the Government borrows to meet this expenditure, as dissaving. But how are we to classify money paid to unemployed workers to perform “public works” of very doubtful value? Suppose these works consist of digging holes in the ground and filling them up again. Or suppose a road is built at a cost which far exceeds its value to the community.147 Evidently, the classification, and still more the estimate of the value of investment involved in such cases, is highly arbitrary and conventional.148 But the magnitude of the multiplier will be influenced by such arbitrary decisions. The fewer are the doubtful cases regarded as investment and the lower is the investment value assumed in each case, the greater will be the multiplier—that is, the marginal propensity to consume of society as a whole. Hence the value of the latter will pro tanto depend upon these arbitrary classifications and not on the psychological propensities of the consumer.
Fortunately, in order to form an opinion on the probable secondary effects of public expenditure, classification as consumption or investment is generally of minor importance. What matters are the factors stressed by traditional theory: the methods used by the Government in raising the money, the rapidity with which the successive recipients spend it, the manner of spending, etc. In this latter respect, individual propensities with regard to saving and consumption come into the picture, but together with many other determining factors, so that no simple and unique relationship between them and the multiplier (marginal propensity to consume of society as a whole) can be expected.
(d) Mr. KEYNES expresses the view that, in the short run, the marginal propensity to consume (multiplier) may deviate from its “normal” value, but he assumes that it will gradually return to it.149 Such a deviation will occur if producers of consumers’ goods do not foresee the increase in demand resulting from an expansion in the capital-goods industries. Then, momentarily, prices of consumers’ goods will rise or stocks be depleted. The same is true when full employment is reached or bottle-necks prevent consumers’ goods industries from expanding. All these factors, which cannot be said to be governed by a psychological law, must be taken into account in order to determine the marginal propensity to consume of the community (multiplier).
The multiplier and income velocity of money.
(e) Certain difficulties arise when we consider the relation between the multiplier and the income velocity of circulation of money. Suppose the psychological marginal propensity to consume of those who receive money from the Government through public works is unity; that is, they save nothing, but spend the whole amount they receive on consumption. This is a conceivable situation, even if it is deemed unlikely. For reasons which will be discussed at some length in the second part of this book (Chapter 10, § 6), we should normally expect the secondary effects of a public works policy to be greater in that case than if the marginal propensity to consume was smaller than 1. But we should not expect to find an infinite rise in demand for consumption goods. This is, however, what follows from the assumption that Mr. KEYNES’ marginal propensity to consume for society as a whole is unity; for this latter implies, as we have seen, that the multiplier is infinite. As Mr. KEYNES’ says, “the logical theory of the multiplier . . . holds good continuously, without time-lag, at all moments of time”.150 Hence, as there will, in fact, be some time-lag between the receipt of money and its expenditure, and since this time-lag will prevent an increase in investment from causing an immediate rise in consumption to infinity, we must say, in Mr. KEYNES’ language, that there is a temporary distortion of the propensity to consume, and that consumption will only gradually tend to increase to infinity if the net increase in investment expenditure is permanently maintained. Hence, to determine the secondary effects, in time, of new public expenditure, we need, in addition to the information about the marginal propensity to consume of the various individuals, also information about the income velocity of money. This point has been well discussed by Professor J. M. CLARK (op. cit.).
Conclusions.
We are now in a position to sum up the conclusions of our discussion. The pure theory of the multiplier shows the definitional relation between the “propensity to consume” and the multiplier. Many problems which are frequently discussed under the heading “multiplier” lie outside the pure theory of the multiplier. They can be divided into two groups, those relating to (a) the determination of the amount of net investment associated with a given amount of spending under varying circumstances and (b) the determination of the numerical value of the multiplier. The marginal propensity to consume of the individual to which Mr. KEYNES’ fundamental psychological law refers, is only one of many factors which are causally important for the determination of the marginal propensity to consume (multiplier) of society as a whole. For this reason, care must be taken not to exaggerate the stability of the multiplier, which cannot be treated as a datum, but must be included among the variables (quaesita) of the theoretical system.151
§ 5. THE THEORY OF UNDER-EMPLOYMENT
Application, to the business cycle of Mr. Keynes’ system.
Mr. KEYNES’ theory does not furnish a readymade answer to the riddle of the business cycle, but is intended to supply tools for the analysis of all sorts of problems concerning short-term fluctuations as well as long-run conditions. “The object of our analysis is . . . to provide ourselves with an organised and orderly method of thinking out particular problems; and, after we have reached a provisional conclusion by isolating the complicating factors one by one, we then have to go back on ourselves and allow, as well as we can, for the probable interaction of the factors amongst themselves. This is the nature of economic thinking.”152
The analysis of the preceding pages should have made it abundantly clear that Mr. KEYNES’ theoretical apparatus is not incompatible with any one of the theories of the cycle, or particular phases thereof, which have been reviewed earlier in this book. All these theories can be expressed in Keynesian language. Mr. KEYNES’ own application of his theoretical apparatus to the typical business cycles, as contained in his “Notes on the Trade Cycle”,153 have been briefly reviewed above in connection with the psychological theories (Chapter 6).
An over-saving theory of depression.
However, the theory, or theories, of economic depressions—cyclical and otherwise—which are generally associated with, or have emerged under, the influence of Mr. KEYNES’ General Theory of Employment can be best described as a special sort of under-consumption or over-saving theory. All the determinants which play a rôle in Mr. KEYNES’ system are always involved: the liquidity-preference, the supply of money, the marginal efficiency of capital and the propensity to consume. But it is the last one which is stressed most. This under-consumption theory is to be found in many passages of the General Theory and in numerous writings of Mr. KEYNES’ followers; it seems to refer primarily to depressions of longer duration; since, however, that is not always quite clear, we shall simply speak of periods of underemployment.
Let us first consider the description, in Mr. KEYNES’ terms, of an equilibrium with less than full employment. Such situations are described in earlier parts of Mr. KEYNES’ book, before all relationships (especially the liquidity-preference) have been introduced, and hence are there presented without all the necessary qualifications. This fact makes the theory appear more contradictory to traditional views than it really is. Suppose the liquidity-preference and the quantity of money are given. Hence the rate of interest is given. If the schedule of marginal efficiency of capital is given, the amount of investment is determined. And if the schedule of the marginal propensity to consume (multiplier) is known, the level of income and employment is also determined.
Let us now consider the interrelation of the last two schedules—the liquidity-preference schedule, the quantity of money and hence the interest rate being given and remaining unchanged. In wealthy communities, the propensity to save (consume) is great (small). Therefore much investment is needed to “fill the gap” between total output and that part of it which the “community chooses” to consume. There is no guarantee that at full employment there are enough opportunities to invest (at the given rate of interest) to maintain full employment.154 If, as frequently happens, not enough investment is forthcoming, the level of employment and income must fall. This fall will induce people to save less of their income; some may even draw on accumulated resources and consume more than their income—i.e., may dissave. Likewise, “the Government will be liable, willingly or unwillingly, to run into a budgetary deficit”, in order to provide for relief, etc., which is equivalent to a strengthening of the propensity to consume of society as a whole. Thus a new equilibrium will be reached when saving has fallen sufficiently for investment to fill the gap between ouput and consumption. It is not difficult to introduce here the liquidity-preference schedule: when income falls, money is liberated from the transaction sphere, M1 falls, M2 rises, the interest rate falls, and equilibrium can be reached at a higher level than if interest rates had not fallen.
The three schedules, together with the quantity of money and some other data such as the available factors of production (labour, equipment, etc.) and the wage-unit,155 determine the level of employment and unemployment. Hence it is impossible to blame any one of the three “psychological factors” (schedules) above for the absence of full employment. Or, if one chooses, one may attribute the existing unemployment to either one alternatively, if all the other data are given: other things being given, employment would be greater (smaller), if the propensity to consume was greater (smaller) than it actually is. Or: other things being given, employment would rise, if the liquidity-preference were to fall; or if the marginal efficiency of capital were greater, etc.
Other theories in Mr. Keynes’ terms.
It is now easy to see that any one of the various hypotheses concerning the causes of the downturn or the upturn of the business cycle which we have reviewed in the earlier chapters is compatible with, and can be expressed in terms of, Mr. KEYNES’ theoretical apparatus. Employment may start to fall, (a) because the propensity to save has become stronger without an offsetting weakening of the liquidity-preference; (b) because, for one reason or the other, the marginal efficiency of capital collapses (that is Mr. KEYNES’ own tentative hypothesis for the crisis in the typical trade cycle); (c) because the liquidity-preference proper becomes stronger (i.e., because M2 increases—i.e., people hoard) or the banks contract the quantity of money.156
Similarly, the various hypotheses concerning the forces which may bring about an upturn in employment can be classified according to the Keynesian categories. Employment and income may start to rise (a) because of a shift to the right of the schedule of the marginal efficiency of capital: this may be due to inventions, to an increase of replacement requirements, or to an improvement in expectations of entrepreneurs, however brought about. In all these cases, traditional theory would add the condition that the supply of investible funds must not be wholly inelastic. If that were the case, the shift in the marginal efficiency of capital would raise the rate of interest, but not the volume of investment. In Mr. KEYNES’ terms, we have to say that the liquidity-preference schedule proper must not be a vertical straight line. Mr. KEYNES always assumes this to be the case, and most writers now agree that this is true in times of depression. Employment will rise, (b) if the propensity to consume increases. Assuming other things to be equal and the liquidity-preference schedule elastic, this is clearly the case. Some writers, it is true, would object to the assertion that a decrease in saving will stimulate employment. The reason is, however, that they assume an inelastic liquidity-preference schedule. In that case, if some people save less and spend more on consumption, correspondingly less will be spent on investment, the rate of interest will rise and aggregate effective demand remain unchanged. But most writers will agree that this is an unrealistic assumption, at least in depressions.
Thanks largely to Mr. KEYNES, there is to-day almost general agreement that Government spending, barring psychological repercussions and assuming an elastic liquidity-preference schedule, will stimulate employment. This must be construed, in Mr. KEYNES’ terminology, either as an increase in the propensity to consume or as a shift of the marginal efficiency of capital, depending upon the classification of Government expenditure as investment or consumption.
Similarly, dishoarding by private individuals has to be described as a decrease of liquidity-preference proper (shift to the left of the liquidity-preference curve) coupled with an increase either of the marginal propensity to consume (if the money is spent on consumption) or an increase in the marginal efficiency of capital (if the money is spent on investment goods). In both cases, it tends to stimulate employment.157
The cumulative nature of a process of expansion and contraction after it has once started cannot be deduced from Mr. KEYNES’ theory. It requires additional assumptions of a dynamic character, as we find them in various business-cycles theories. These dynamic relationships can, however, be formulated in his terms. Assume, for instance, that the marginal efficiency of capital drops (rises) when income falls (rises) or that liquidity-preference proper (propensity to hoard) rises (falls) when activity contracts (expands).
Voluntary and involuntary unemployment.
So far, we have detected a number of terminological differences between Mr. KEYNES’ theory and the traditional views as represented by, say, Professor PIGOU’S Industrial Fluctuations, Professor ROBERTSON’S writings or the synthesis attempted in Part II of the first edition of this book, which is reproduced, with slight changes, in the present edition. In addition, we have suggested (cf. pages 209 and 218 above) that Mr. KEYNES has made an important contribution by his insistence on the relationship between “hoarding” and the rate of interest. Apart from this, we have not as yet discovered any essential differences between Mr. KEYNES’ theory and that of the other recognised authorities. According to Mr. KEYNES, however, there is a fundamental discrepancy between the two, inasmuch as the “classical” theory cannot conceive at all of an equilibrium with less than full employment. “The classical theory is only applicable to the case of full employment.”158 More precisely, it is involuntary unemployment which is, according to Mr. KEYNES, incompatible with classical equilibrium; voluntary unemployment may, of course, exist in equilibrium; that is to say, if some people prefer not to work at the prevailing wage, they are not counted as unemployed; or “an eight-hour day does not constitute unemployment because it is not beyond human capacity to work ten hours” (page 15).
Involuntary unemployment, which classical theory is accused of having overlooked, or being unable to explain, is defined as follows: “Men are involuntarily unemployed if, in the event of a small rise in the price of wage-goods relatively to the money-wage [we could also say: in the event of a fall in real wages], both the aggregate supply of labour willing to work for the current money-wage and the aggregate demand for it at that wage would be greater than the existing volume of employment”159
Free competition in the labour market and unemployment.
This is a new definition. The incompatibility of involuntary unemployment in this sense with classical equilibrium has therefore never been explicitly denied. Is such a definition implicit in the traditional position? The traditional view is generally taken to be that, under free competition in the labour market, unemployment is incompatible with equilibrium because, with free competition, money-wages will be flexible. Only if money-wages are rigid in the downward direction, if they are prevented from falling either by tradition, by trade-union pressure, or by Government action, can unemployment exist in equilibrium. This position does not, however, exclude the existence of involuntary unemployment in Mr. KEYNES’ sense. Suppose there is unemployment and wages are rigid in the downward direction. Few classical writers will deny that employment may and will rise when aggregate demand and prices are raised by a revival of investment financed by new bank credit or by dishoarding. As there was then previously involuntary unemployment, its compatibility with equilibrium is not implicitly denied by the traditional view.
A difference of opinion can and does exist only in respect of the consequences and desirability of free competition in the labour market, which would ensure a complete flexibility of wages. However, the following two propositions would presumably be accepted both by Mr. KEYNES and by the classical school. First, if there is free competition in the labour market, money-wages will fall continuously, so long as there is unemployment. A situation in which wages fall continuously can hardly be called an equilibrium position.160 Secondly, in point of fact wages are, and probably have always been, rigid, because of trade-union resistance, unemployment relief, tradition, etc.
Money-wages and real wages.
There seems to exist, however, a real difference of opinion between Mr. KEYNES and the classical school concerning the influence of a fall in money-wages on employment. Mr. KEYNES expresses the view that, “with a given organisation, equipment and technique”, an increase in output and employment necessitates a fall in real wages.161 But whilst the “classical theory assumes that it is always open to labour to reduce its real wage by accepting a reduction in the money-wage”,162 Mr. KEYNES’ contention is that “there may exist no expedient by which labour as a whole can reduce its real wage to a given figure by making revised money bargains with the entrepreneur”;163 the reason being that “prices change in almost the same proportion, leaving the real wage . . . practically the same as before”.164 Mr. KEYNES is, however, careful to add that “this argument would . . . contain . . . a large element of truth, though the complete results of a change in money-wages are more complex”.165 In Chapter 19, “Changes in Money-Wages”, he discusses the question in detail, and introduces many modifications into the original simple argument; but the argument is sometimes presented by economists in its simple unmodified form.166 A closer analysis of this chapter seems to suggest that there is no fundamental difference between Mr. KEYNES’ results and those reached by those more orthodox writers (such as Professor PIGOU in his Industrial Fluctuations) who pay attention to possible short-period repercussions of wage reductions. Since there is substantial agreement, except in terminology, between Mr. KEYNES’ analysis and the one given in Chapter 11, § 9, of the present book, only a few points will be raised in this connection.
Reduction in money-wages and aggregate demand.
According to Mr. KEYNES, the “accepted explanation” of the consequences of a reduction of money-wages starts from the assumption that aggregate effective demand remains unchanged; then, naturally, employment will rise. Mr. KEYNES points out (as was observed in the first edition of this book167) that this assumption assumes away almost the whole problem. It may be legitimate in a rigid equilibrium theory which deliberately argues under the simplifying assumption of constant aggregate demand; but it is certainly illegitimate in business-cycle theory, and it is usually not made there.
In his view, a “reduction in money-wages will have no lasting tendency to increase employment except by virtue of its repercussions either on the propensity to consume for the community as a whole, or on the schedule of marginal efficiencies of capital, or on the rate of interest”.168 This is true, because the three terms are so defined that any change in output and employment resulting from a fall in money-wages must be describable in terms of one or the other, or a combination of the three magnitudes mentioned. If investment output rises, the rate of interest and consumption having remained unchanged, the marginal efficiency of capital schedule is said to have shifted; if consumption rises without an increase in investment and without a change in the interest rate, the propensity to consume of the community as a whole is said to have increased, etc.
Mr. KEYNES, however, characterises such influences of wage reductions on employment as “roundabout repercussions”,169 and suggests that the classical theory erroneously supposes that there is a direct route by which wage reductions may affect output and employment without affecting the propensity to consume, the marginal efficiency of capital or the rate of interest. But, in fact, the repercussion may be quite direct, even though it can always be expressed in Mr. KEYNES’ terminology if one desires to do so. Let us take the most straightforward case. Suppose wages in a pure consumption trade, say, of domestic servants, are reduced and the elasticity of demand for these services is unity. Then the consumption of these services and employment will rise. The effect of the wage reduction on employment is obviously direct; but in Mr. KEYNES’ terms we must describe it as an influence via an increase in the propensity to consume.
Mr. KEYNES quite rightly stresses that, in order to evaluate the total effect of a wage reduction, it is not sufficient to consider it only in its cost aspects; effects through an increase or decrease of workers’ purchasing power must be considered too. This matter will be taken up in extenso in Chapter 11 below. He then discusses various routes via which wage reductions may react, in an internationally closed system, or in an “open” one, through creating expectations on the part of entrepreneurs with respect to future changes of wages in an upward or downward direction or by producing “a more optimistic tone in the minds of entrepreneurs, which may break through a vicious circle of unduly pessimistic estimates of the marginal efficiency of capital and set things moving again on a more normal basis of expectation” (page 264).
Wage reductions increase liquidity.
The most important influence which definitely operates in the direction of a rise in employment and output (whilst many of the others may cut either way) goes via the liquidity-preference. “The reduction in the wages-bill, accompanied by some reduction in prices and in money-incomes generally, will diminish the need for cash for income and business purposes; and it will therefore reduce, pro tanto, the schedule of liquidity-preference for the community as a whole. Ceteris paribus, this will reduce the rate of interest and thus prove favourable to investment” (page 263). A fall in wages and prices is considered equivalent to an increase in the quantity of money. “If, indeed, labour were always in a position to take action (and were to do so), whenever there was less than full employment, to reduce its money demands by concerted action to whatever point was required to make money so abundant relatively to the wage-unit that the rate of interest would fall to a level compatible with full employment, we should, in effect, have monetary management by the trade unions, aimed at full employment, instead of by the banking system” (page 267).
In our terminology, that amounts to saying that unemployment with flexible wages leads—in the unfavourable case where the wage-bill falls in response to a fall in wages—to an indefinite increase of idle funds (in liquidity) in terms of money and still faster in real terms; and there must be somewhere a limit at which people will stop hoarding and begin to spend again, either on consumption or investment. (See below, Chapter 11, § 8.)
We conclude once more that, according to Mr. KEYNES’ theory, his equilibrium with unemployment can exist only if money-wages are rigid in the downward direction. This seems quite inescapable; and if Mr. KEYNES never quite admits it, at one point he comes very near to doing so: if there were “competition between unemployed workers”, “there might be no position of stable equilibrium except in conditions consistent with full employment, since the wage-unit might have to fall without limit until it reached a point where the effect of the abundance of money in terms of the wage-unit on the rate of interest was sufficient to restore a level of full employment. At no other point could there be a resting-place.”170
Does flexibility of wages and prices promote stability?
From this statement, with which all adherents of the classical school would agree, it does not, however, follow that very flexible wages (absolutely perfect competition in the labour market) are necessarily the best policy to get rid of unemployment. One may still hold with KEYNES that, under such conditions, prices may become very unstable, which may make business calculations difficult and affect unfavourably the marginal efficiency of capital.171 The problem is a pressing one which has not yet been solved satisfactorily. Is absolute flexibility or is a certain degree of rigidity of prices and money-wages more conducive to stability of real income? There is one section where competition has been strong and prices have been very flexible—viz., agriculture. During the last depression, for instance, prices of agricultural products fell drastically, but output and employment were maintained. In industry (especially in capital-goods and durable-goods industries), prices were better maintained, but output shrank. It goes without saying that, for the farming population, that is a very unfavourable situation. But many people would argue that, if industry behaved like agriculture, prices would fall all around, but production would be well maintained. This may be so, but it must be said that it has not yet been rigorously proven. It may well be, as KEYNES says, that violent fluctuations of prices, and in particular reductions of prices, would create great uncertainty and very unfavourably affect the demand for capital and the willingness to invest. Thus the result may be that unemployment could be eliminated and the labour market cleared by a very drastic cut in wages, but at the price of a fall of real wages to a very low level. (Thus Mr. KEYNES’ assertion that prices would fall pari passu with a fall in wages—which has been carried to extreme lengths by Mr. LERNER, loc. cit.—may be unduly optimistic.) In other words, if owing to rapid price changes entrepreneurs became very pessimistic, or at least very uncertain about the future, the demand for labour might become very inelastic.
Hence, although the classical theory is right in saying that an equilibrium with unemployment is incompatible with competition in the labour market, it does not necessarily follow that plasticity of wages would eliminate depressions. (Compare the cautious and well-balanced treatment of this problem in Professor PIGOU’S Industrial Fluctuations, Chapter XX, “The Part played by Rigidity in Wage Rates”).172
Chronic depressions due to under consumption.
At the beginning of this section (see page 233 above), it was stated that the depression theory most frequently associated with Mr. KEYNES’ theoretical system is an under-consumption or over-saving theory. This statement may not seem to have been borne out by the detailed analysis of Mr. KEYNES’ pure theory in the preceding pages. It is nevertheless true in the sense that Mr. KEYNES, in many places, emphasises the low propensity to consume prevailing in rich countries as the main source of troubles. “But worse still. Not only is the marginal propensity to consume weaker in a wealthy country, but, owing to its accumulation of capital being already larger, the opportunities for further investment are less attractive” (page 31). Moreover, in various places, the spectre is raised of a lower limit to a fall in the rate of interest “which in present circumstances may perhaps be as high as 2% or 2½% on long term. If this should prove correct, the awkward possibility of an increasing stock of wealth, in conditions where the rate of interest can fall no further under laissez-faire, may soon be realised in actual experience.”173 “The post-war experiences of Great Britain and the United States are, indeed, actual examples of how an accumulation of wealth, so large that its marginal efficiency has fallen more rapidly than the rate of interest can fall in the face of the prevailing institutional and psychological factors, can interfere, in conditions mainly of laissez-faire, with a reasonable level of employment and with the standard of life which the technical conditions of production are capable of furnishing” (page 219). “I should guess that a properly run community equipped with modern technical resources, of which the population is not increasing rapidly, ought to be able to bring down the marginal efficiency of capital in equilibrium approximately to zero within a single generation” (page 220). Mr. KEYNES believes “it to be comparatively easy to make capital goods so abundant that the marginal efficiency of capital is zero” (page 221).
Among writers who accept, as well as among those who reject these diagnoses and forecasts, the impression seems to prevail that they can be deduced from Mr. KEYNES’ General Theory, but not from the traditional theoretical apparatus. This impression appears to be unfounded. In either case, additional empirical assumptions are required to establish the validity of those diagnoses, and, given these assumptions, they can be deduced from, or rather expressed, in terms of, either one of the two theoretical systems.
The empirical foundation and justification of these visions need not be examined in this book, where we are interested more in the formal logical structure of the general theory. If they are not new, they have at least received a strong impetus from Mr. KEYNES’ General Theory. The views expressed have been elaborated by various writers on the empirical side and much raiment has been put around Mr. KEYNES’ bare contentions. We may mention a few broad facts which have been adduced to support his thesis.
The drying-up of investment opportunities.
Investment opportunities are said to have become scarcer, as compared with the nineteenth century, because of the less rapid growth of population; the cessation of migration on a large scale and of the opening of new territories and continents; the reduction of international lending for the reason just mentioned and others of an institutional and political character. More precarious assumptions are also made—for instance, that capital-consuming technical inventions are less likely to be made in the future than in the past.
On the other hand, reasons are given which make it unlikely that the volume of saving will decrease, and it is stressed that important changes in the structure of the supply of saving have occurred which impede their smooth absorption into the available investment channels: savings are increasingly made by institutions such as life insurance and social insurance companies, which are, in most countries, prevented from investing in equities. In other words, capital has become less venturesome, more timid than it used to be in the heydays of capitalism. This tendency creates a situation of scarcity amidst plenty in the capital market and eliminates a number of important outlets for investment.
These speculations about secular tendencies and developments are necessarily vague and are easily coloured by the subjective attitude of the particular writer and the surrounding conditions. Their persuasiveness often depends less on the logical force of the argument than on the way in which relevant facts are selected. Temporary hitches in the flow of investment, due to psychological shocks, rigidities, etc., are frequently interpreted as being due to a chronic lack of investment opportunities. The conditions necessary for chronic unemployment are overlooked or not clearly stated: for example, it is often not realised that either money-wages and prices must be rigid against downward pressures, or else, if they are allowed to fall gradually under the pressure of competition, it must be assumed that people are willing to hoard unlimited amounts of money.
However, the clear realisation of all the necessary qualifications of these theories cannot definitely disprove their validity, although it may reduce their persuasiveness. Only the careful scrutiny of a mass of experience and the study of historical processes can make the hypothesis more or less probable.174
§ 6. STATIC VERSUS DYNAMIC THEORIES: SOME METHODOLOGICAL OBSERVATIONS
We may properly terminate the first part of this book by reflecting briefly on certain fundamental characteristics of the theories reviewed, thereby reverting to the logical problems touched upon in the first chapter.
General versus partial equilibrium.
On an earlier occasion, we characterised Mr. KEYNES’ General Theory as a general interdependence (equilibrium) theory in macro-economic terms. The theory is a general interdependence theory in the sense that it explicitly embraces the economic system as a whole and represents it by means of a limited number of magnitudes interrelated by a few easily comprehensible relationships. This explicit generality distinguishes Mr. KEYNES’ system favourably from many business-cycle theories which give only a partial picture, confining themselves, consciously or unconsciously, to exhibiting only some particular relationships, which are supposed to be the crucial ones, and leaving the rest hidden, so that it is left to the reader to supply from general economic theory the missing relationships which are necessary to make the system determinate.
Macroscopic versus microscopie analysis.
Mr. KEYNES’ system is conceived in terms of macro-economic concepts, inasmuch as its fundamental data consist of complex magnitudes which relate to society as a whole, such as national income, savings, investment, volume of production of producers’ or consumers’ goods, effective aggregate demand, price levels, etc. Its macroscopic nature Mr. KEYNES’ theory has in common with most business-cycle theories. If a theory which aims at representing the economic process as a whole is to be manageable, it cannot avoid using broad averages and aggregates of a collective nature. It is very well to preach a microscopic approach and to urge the investigator to go back to the individual units (households and firms). It is true, of course, that direct and indirect observations of individual behaviour and happenings are the only source of information about the magnitude and behaviour of collective phenomena. But the final175 statements at which the theory aims (as distinguished from the methods by which they are reached) must practically always run in terms of aggregates and averages.176
The broader these aggregates, the smaller their number, the more easily manageable (theoretically and statistically) the resulting system. Unfortunately, however, it is usually not possible to find between very broad aggregates significant relationships which can be relied upon to be borne out by the facts. If so, the aggregates must be subdivided, the method must be made more miscroscopic. But so long as aggregates, even restricted in scope, are used, there is always the danger that the internal structure of these aggregates (in other words, the relationships between their subdivisions) may prove to be significant; this would force the economist to split up the aggregates so far undivided and to try to construct his system in terms of subdivisions of these aggregates. Thus the business-cycle theorist is always torn between the temptation, on the one hand, to go into minute details and to work out an endless number of individual cases where the course of events is decisively influenced by small details, and the passion, on the other hand, for constructing sweeping theories with a few bold strokes of the pen. The stony path of the economist working in this field leads constantly between the Scylla of a maze of individual cases of an unmanageable casuistry and the Charybdis of ingenious and clean-cut but lofty and half-true theories.
Static versus dynamic theories.
Mr. KEYNES’ theory has still another characteristic which distinguishes it from all business-cycle theories: it is essentially static. By a static theory, we mean a theory where all the variables (magnitudes to be explained) relating to a certain point or period of time are explained by data relating to the same point or period of time.177 Such a theory can never explain a movement in time. It can only answer the question: Given certain data at a certain moment, what will be the result at that moment? True, if the data change in time, then the results will also change. But a change in data cannot be explained. (If it could, then the data would cease to be data and become variables.) They must be given (or assumed) anew for each successive point in time. This method of dealing with economic change is frequently called “comparative statics”.178
To explain the business cycle, or any change of the economic system over time, we need either a law about a (cyclical) change in certain data or a dynamic theory. In the first case, we speak of an “exogenous” theory of the cycle. (See Chapter 1.) The paradigma is the weather theory of the cycle. But explanations of this sort can be discarded at once as insufficient.
By a dynamic theory, we mean “a theory that explains how one situation grows out of the foregoing. In this type of analysis, we consider not only a set of magnitudes in a given point of time and study the interrelations between them, but we consider the magnitudes of certain variables in different points of time, and we introduce certain equations which embrace at the same time several of these magnitudes belonging to different instants.”179 We may also say that a theory is dynamic, if a magnitude is explained by another relating to an earlier (or, more generally, to another) point of time. In still other words: if there are lags in the causal nexus. If we say, for instance, that the volume of production (of a particular commodity or of commodities in general) is governed by the relation of cost and prices, we obviously must allow for a certain lag: cost and prices to-day govern production to-morrow. The acceleration principle is a dynamic relationship: investment is explained by a previous change in demand for the product. The “multiplier relationship” may be formulated dynamically, by allowing a time-lag between investment and the resulting increase in consumption demand. (In Mr. KEYNES’ system, it will be recalled, it is a timeless terminological rule; only incidentally are some remarks made about the probable change of the value of the multiplier, or of the marginal propensity to consume, over time.180
Such a dynamic theory is endogenous in character. The determinants at any moment of time cease to be simply assumed. Today’s determinant data are yesterday’s variables (and are thus explained), and to-day’s variables become to-morrow’s data. The successive situations (short-run equilibria) are interconnected like the links of a chain. Hence, in order to explain a movement (cyclical or otherwise), we need not assume a corresponding change in the data;181 we need be given only the first position or an initial change in data, at the beginning of the process.
The skeleton of Mr. KEYNES’ theory, as it is represented precisely in diagrammatic form by Professor LANGE,182 is essentially static. There are no time-lags, and all the data and variables relate to the same point of time. There are, however, many allusions to dynamic relationships in incidental remarks and illustrative observations which are thrown out in great number all over the book. Moreover, dynamic theories can be grafted upon (or, as it is more correct to say, may be expressed in terms of) Mr. KEYNES’ system. This has been done, for example, by Mr. HARROD,183 who introduced the dynamic acceleration principle (and seems to interpret the multiplier dynamically). Another example is Mr. M. KALECKI’S theory,184 which introduces a lag between investment decisions as determined by the current situation and the actual volume of investment.185
Are expectations a dynamic element?
There is, however, one feature about Mr. KEYNES’ system which has given the impression to many readers that the General Theory of Employment is a dynamic theory—namely, the fact that, following the lead of Swedish writers such as MYRDAL and LINDAHL, it runs in terms of expectations. Almost every concept is defined in terms of expectations: “aggregate demand function”, “supply function”, “effective demand”, “marginal efficiency of capital”, etc., are defined with the help of such concepts as “the prospective yield of capital”, “proceeds which entrepreneurs expect to receive”, etc.186 Now, in a sense it is true that the explicit introduction of expectations tends to make a theory truly dynamic. In the sense, namely, that the introduction of expectations into the causal nexus is essentially an incomplete idea which requires, in order to become at all useful, a complement which makes the theory dynamic: if we confine ourselves to saying that it is not actual (current) prices, costs, profits, etc., but expected prices, costs, profits which induce an entrepreneur to produce and to invest, we do not say very much, unless we give some hint as to how these expectations are determined.
A theory which takes the expectations as given at any point of time, and does not say anything on how they grow out of past experience, is of very little value; for such a theory would still be static, and it is almost impossible to determine expectations as such.187 Only if it is possible to give some hypotheses about how expectations are formed on the basis of past experience (prices, state of demand, costs, profits, etc.) can a really useful and verifiable theory be evolved. And such a theory is evidently dynamic in the sense explained above, for it links the past with the present: past prices, costs and profits via the state of expectation with present production, consumption and investment.188
Mr. KEYNES has, of course, much to say on the formation of expectations and the difficulties and limitations confronting any theory on this subject. But all this is contained in the wealth of remarks, observations and obiter dicta which—elaborating, supporting, illustrating and, at times, contradicting and blurring—surround the main outline of his theory: the dynamic aspects do not penetrate the heart of his theory.
Professor ROBERTSON’S “period analysis”, on the other hand, is a clear step in the right direction of a truly dynamic analysis, Similarly, a number of Swedish writers, especially Dr. Eric LUNDBERG in his Studies in the Theory of Economic Expansion,189 have visualised the problem clearly. Dr. LUNDBERG characterises the method as “sequence analysis” and has constructed a number of macroscopic dynamic models—“model sequences” as he calls them.190
Theoretical versus statistical models.
Dr. LUNDBERG’S models are theoretical—that is to say, the figures are assumed (not found statistically); the relationships postulated, although assumed and selected so as to be not impossible on a priori grounds, are too simple and too few in number to give an adequate picture of the enormous complexity of real life.191 Professor TINBERGEN, on the other hand, in a number of pioneering studies, has tried to evaluate statistically a great number of dynamic relations for particular countries and to construct concrete models which give at least a rough quantitative approximation of the principal economic magnitudes and of the dynamic laws by which they are interrelated.192
A dynamic theory of the business cycle, if fully elaborated in precise terms, so as to do some justice to the enormous complexity of the real world, requires a highly complicated mathematical technique and presents formidable problems from the purely formal logical point of view.193
________________
194 Cf. mainly contributions by various writers to recent issues of the Economic Journal, Econometrica, Economica, Zeitschritt für Nationalökonomie, Quarterly Journal of Economics, etc
195 Professor Robertson has recently made an attempt at separating terminological from substantial differences. Cf. “A Survey of Modern Monetary Controversy” in The Manchester School, Vol. 9, No, 1, April 1938.
196 Cf., for example, A. P. Lerner: “Alternative Formulations of the Theory of Interest” in the Economic Journal, Vol. 48, June 1938, passim.
197 In the following pages, we shall frequently use the following symbols: S = Saving, I = Investment, Y = Income, C = Consumption.
198 The use of the equality of saving and investment as an equilibrium condition has been ably criticised by W. Fellner in his article “Saving, Investment and the Problem of Neutral Money” in Review of Economic Statistics, Vol. XIII, November 1938.
199 See especially: Keynes, General Theory, passim; A. P. Lerner, “Saving equals Investment” in Quarterly Journal of Economics, Vol. 52, February 1938, and “Mr. Keynes’ General Theory of Employment” in International Labour Review, October 1936; Mrs. J. Robinson, Introduction to the Theory of Employment (London, 1937), especially pages 14 to 16, “The Hoarding Fallacy”; R. F. Kahn’s review of the first edition of the present book in the Economic Journal, Vol. 47, 1937, Page 671; and R. F. Harrod, The Trade Cycle, London, 1936, pages 65 et seq.
200 General Theory, page 63.
201 I put “inflation” in quotation marks, because some writers would like to reserve the word “inflation” to such an increase in the quantity of money as leads to a rise, or to an “excessive” rise, in prices; they resent the use of the word for cases where the increased amount of money (or of monetary demand) is matched by an increase in the flow of goods and hence does not bring about a rise in prices. (Cf., for example, Mr Kahn’s review of the first edition of this book in the Economic Journal, Vol 47, 1937, page 675, and my answer, ibid, Vol. 48, 1938, pages 326 and 327.)
202 The Trade Cycle, page 72.
203 Ibid., page 72. If prices of consumers’ goods rise, the income and savings of the retailers go up.
204 Mr. Lerner admits that “if we take artificial periods—say often minutes each—our definitions acquire an artificial flavour too. We would then have to say that in the ten-minute period in which a man receives his weekly wage, he saves (nearly) all of it, and that in all the other ten-minute periods in which he makes any expenditure, he dissaves” (Quarterly Journal of Economics, Vol. 52, 1938, page 304.) Mr. Lerner is, however, not right when he says that this artificiality disappears “if we take reasonable periods”. Owing to the overlapping of periods, it never disappears completely. Moreover, the order of magnitude of the phenomenon in question is not correctly indicated by speaking of ten-minute periods.
205 Sometimes another account of how S and I are equated has been given by followers of Mr. Keynes. For instance, Mrs. J. Robinson, in her Introduction to the Theory of Employment, puts the matter in the following way. Assume £1 per week is invested in housebuilding. Then make certain assumptions about the saving by the successive recipients of the money. “At each round”, a certain proportion is saved by workers, profit earners, etc. On this assumption, the author constructs a series of acts of saving which add up exactly to the figure of investment outlay (pages 20 and 21). If by “round”, turnover (change of hand) of money is meant, and if money does not circulate with infinite rapidity, this account of the matter proves the contrary to what it is intended to prove. For it takes time (strictly speaking, an infinite period of time under Mrs. Robinson’s assumption) before the savings made at successive rounds add up to the total which is equal to the investment. What can be said is that there is a tendency for S to approach I, but owing (a) to the infinite length of these series and (b) to the overlapping of series set up by successive acts of investment, there can never, or only under very special assumptions, be an absolute equality of S and I.
206 Not all money received by an individual or a firm is (net) income. Part of the receipts of a producer is to be set aside for the replacement of capital, either of working capital or of fixed capital. In the first case, it is sometimes said that the money constitutes “working capital”; in the second case, we speak of “depreciation allowances” or “amortisation quotas”. Naturally, the more durable a capital instrument is, the greater is the freedom and arbitrariness in distributing over the period of its life-time the corresponding amortisation allowances. Therefore many writers (for example, Mr. Hawtrey) define gross income inclusive of depreciation allowances. It should, however, not be forgotten that the transition from fixed to working capital is gradual and that, in principle, the same problems are involved in the replacement of either.
207 It should be noted how easy it is to describe the phenomenon without using the words “saving” and “investment” in terms of receiving and spending of money.
208 It could be objected that a retailer may cut his consumption and maintain his saving. This is quite true, but this further decrease in consumers’ outlay (act of saving) can be treated exactly as the original one: it must again reduce somebody else’s income and cannot give rise to a divergence between S and I.
209 Mr. Harrod, for example, speaks of “the new-fangled view, sponsored by Mr. Keynes in his Treatise, that the volume of saving may be unequal to the volume of investment” (“Mr. Keynes and Traditional Theory”, in Econometrica, Vol. 5, 1937, page 75). On the Continent, the view that S and I need not be equal has been held at least since Wicksell, and, as Mr. Hawtrey has pointed out, in the classical English writings the equality of S and I has always been regarded as an equilibrium condition rather than an identity (although not all the implications of this view have been recognised or explored).
210 The reader’s attention might be called to the possibility of interpreting, what Mr. Keynes was aiming at in terms of the Swedish ex ante and ex post analysis, which will be reviewed below (page 180). Y is clearly defined as an ex ante concept, while profits and losses are ex post magnitudes. Likewise, S is defined in ex ante terms and I in ex post terms. (This was pointed out to me by Dr. Redvers Opie, Oxford.)
211 This has been pointed out by Professor Hayek, Professor Hansen, Mr. Tout and Mr. Hawtrey in their respective analyses of the Treatise. Cf., especially, Hawtrey: The Art of Central Banking, pages 334 et seq.
212 Vide his article “Saving and Hoarding,” Economic Journal, Vol. 43, September 1933, page 399, and the subsequent discussion between Professor Robertson, Mr. Keynes and Mr. Hawtrey, ibid., page 699.
213 The analysis must, of course, be extended to payments other than income payments.
214 General Theory, page 78.
215 Cf. his review of the General Theory in the Journal of Political Economy, Vol. 44, 1936, page 674, now reprinted in Full Recovery or Stagnation, New York, 1938, page 22.
216 “Undeflated”, that is, at current prices, or “deflated” by any sort of price index.
217 “Some Notes on the Stockholm Theory of Savings and Investment”, Economic Journal, Vol. 47, 1937, page 65. Mr. Lerner, on the other hand, always speaks of acts of expenditure, which are classified either as consumption or investment, while both together constitute income.
218 Studies in the Theory of Economic Expansion, London, 1937.
219 Studies in the Theory of Money and Capital, London, 1939.
220 “Der Gleichgewichtsbegriff als Instrument der geldtheoretischen Analyse” in Beiträge zur Geldtheorie, ed. by Hayek 1933 (an English version of which will soon be published by William Hodge, London).
221 “Some Notes on the Stockholm Theory of Savings and Investment”, Economic Journal, Vol. 47, 1937, pages 53 et seq. and 221 et seq, and “Alternative Theories of the Rate of Interest”, ibid., pages 423 et seq.
222 See especially his Capital and Employment, passim.
223 Professor Myrdal was the first to introduce this distinction. Professor Ohlin’s exposition is, however, more accessible and more developed. Therefore, reference will be made chiefly to him.
224 Other members of the group seem to lean rather to Professor Robert-son’s, definition. See Ohlin (loc. cit., page 57): “. . . my terminology has been viewed with great scepticism by some of the younger Stockholm economists, chiefly because of my way of defining income so as to make savings and investment always equal ex definitione”. We shall, however, see that the two analytical schemes, if fully thought out, are by no means exclusive of each other.
225 Ohlin, loc. cit., page 425.
226 It will be noted that, in spite of the appearance to the contrary, no statements about facts are involved in the following analysis. What actually happens, if planned saving and investment differ, is assumed by way of illustration, and can be described in terms of receiving and spending of money and of movement of goods between individuals and into and out of existence without using the terms “savings” and “investment”. No particular process is required to make S and I equal ex post All sorts of reactions are possible, but, whatever actually happens, they must be equal, because the terms are chosen in such a way.
227 Ohlin, loc cit., pages 64 and 65.
228 Ibid., pages 65 and 66.
229 This analysis can be readily translated into Robertsonian language. We would have to say that investment actually exceeds saving by 3 millions. The difference is “financed by other means than by saving from (disposable) income”. This way of expressing the matter has the advantage that it calls attention explicitly to the fact (which is, of course, implied also by Professor Ohlin’s analysis) that bank credits must be expanded or that some people must dishoard—i.e., “reduce their quantity of cash”. (Ohlin, loc. cit., page 425.) The supply of loanable funds must be elastic; otherwise the planned investments could not go ahead undisturbed by the fact that people spend more on consumption than was foreseen. This assumption about the elasticity of the money supply may be correct in many cases, especially if the period in question is sufficiently short. It need, however, not always be correct, and if it is not, the rate of interest will rise so much (or credit will be rationed in such a way) that the investment plans will be sufficiently scaled down. This may very well lead to more or less serious disturbances in the capital-goods industries, as analysed by Professor Hayek. That shows again that Professor Hayek’s theory can be well expressed with the help of the Swedish terminological apparatus.
230 Ohlin, loc. ext., page 69.
231 “Alternative Theories of the Rate of Interest”, Economic Journal, Vol. 47, 1937, Page 423 et seq.
232 It is not quite clear whether his Swedish colleagues all agree on this.
233 Strictly speaking, there are different markets for different kinds of credit—short-term, long-term, etc.
234 Loc. cit., page 425. There are some other possible differences between supply of credit and ex ante saving. “Besides, one can plan to extend credit instead of reinvesting ‘capital made free’—i.e., ‘ depreciation money’” (page 425). A failure of reinvesting depreciation quotas can evidently be treated as negative investment, and could accordingly be deducted from the investment curve (demand curve for credit, of which the investment curve constitutes an element), instead of being added to the supply of credit.
235 Ibid. The latter two items could be considered as negative saving and thus be deducted from the supply curve (curve of ex ante saving), instead of being added to the demand curve (curve of ex ante investment).
236 “Alternative Formulations of the Theory of Interest”, in Economic Journal, Vol. 48, 1938, pages 213 to 215. It is true, Mr. Lerner puts this account of the matter forward as an interpretation, not of Professor Ohlin’s theory, but of “the position [of the theory of interest] as it appears after the first step [from the ‘classical’ to the ‘modern’ view] has been taken” (page 213). This first step consists of the recognition “that ‘hoarding’, ‘dishoarding’ and changes in the amount of money also have something to do with the supply of ‘credit’ and the rate of interest—in the short period, at any rate” (page 211). This seems to me precisely the position taken by Professor Ohlin. Mr. Lerner merely does not take cognisance of the ex ante nature of supply and demand curves of saving in Professor Ohlin’s theory. He interprets S and I throughout ex post. Hence, in a second graph (page 216), he draws just one curve, which is a saving and investment curve at the same time, whilst Professor Ohlin emphasises that S and I ex ante are not necessarily equal. Mr. Lerner probably has been misled by the fact that Professor Ohlin introduces the interpretation of the ex ante concepts of S and I in the schedule sense as an afterthought, as it were, in a reply to a criticism by Mr. Keynes; in his original articles, he did not make it clear that he meant schedules when he spoke of ex ante saving and investment.
237 Equilibrium in the sense of immediate market equilibrium. There need be no equilibrium in any more ambitious sense.
238 Mr. Lerner says that “this exactly portrays the disturbed state of mind of people who declare that saving can be greater than investment if the difference is hoarded” (page 215). Mr. Lerner is led to this statement by his erroneous and rather naive imputation to other writers of his own definition (a) of S and I and (b) of hoarding and dishoarding. He defines S and I throughout as identical and ex post, while in the above diagram it must be defined ex ante (or, as we shall see presently, à la Robertson). Mr. Lerner’s definition of hoarding and dishoarding, which he shares with Messrs. Keynes, Harrod, Kahn and others, will come up for discussion in § 3 of this chapter.
239 It may be noted once more that these words used by Professor Ohlin are rather misleading. Strictly speaking, no process is needed, because S and I ex post are equal at any moment of time. The word “process” suggests—erroneously—that there is only a tendency towards their becoming equal at the end of the process and that they are unequal at the beginning and during that process. In reality, according to the definition given, they are equal at any moment of time.
240 “The Outcome of the Saving-Investment Discussion”, Quarterly Journal of Economics, Vol. 52, August 1938, page 604.
241 We abstract from a number of difficulties connected with the overlapping of the plans, which is due to the fact that plans of different individuals are not always made at the same time and do not all extend over the same period.
242 This problem has been well discussed by E. Lundberg, loc. cit., passim.
243 Loc. cit., page 423.
244 Loc cit., page 424.
245 This is said very clearly, although not with these words, op. cit., page 425. “Will not the planned supply of credit [= demand for bonds] be equal to the planned savings? . . . No, not quite.” And then follow the qualifications about hoarding, dishoarding, etc., which have been mentioned above, page 184.
246 An excess of ex ante saving over ex ante investment, we have seen, leads to a deficiency of demand for consumers’ goods and causes losses to the retailers. This is one of the “processes” which bring about equality between S and I ex post. Clearly, if this construction is to make sense, ex ante saving cannot be interpreted as saving out of a future income. That could not affect retail sales now. To be sure, expectations about future income may affect present saving as a motive. But so will expectations about a hundred other things, and the manner in which, and extent to which, they affect the present situation is by no means uniquely determined.
These considerations illustrate a basic difficulty of the whole ex ante (expectation) analysis: How can mere plans about the future influence the present situation? People are, on the whole, not so much influenced by other people’s expectations or plans, as by their actions. Does not the whole expectation analysis stand in need of a behaviouristic re-interpretation? As Professor Robertson puts it: “Changes in ‘-nesses’ [he is speaking of thriftiness] and ‘propensities’ do not in themselves exercise any effect on the external world. Nor does a decision to get up early necessarily indicate any reduction in the propensity to lie in bed—it may rather indicate an increased determination not to indulge in that propensity!” (Economic Journal, September, 1938, page 555.)
247 These difficulties have been clearly noticed by W. Fellner, “Savings, Investment, and the Problem of Neutral Money”, in Review of Economic Statistics, Vol. 20, November 1938, page 188. Cf. also the criticism of the ex ante concept by Professor H. Neisser in Studies in Income and Wealth, vol. II, New York, 1938, page 172 et seq.
248 There remain unanswered, of course, a number of questions—philosophical questions, we may perhaps say—about the precise nature of the instantaneous curves. Is it justifiable to characterise a demand curve, as Professor Ohlin does, as a series of alternative plans? This language suggests that the various, strictly infinite, alternatives are thought out in advance in the mind of the individuals. A more behaviouristic interpretation may be better, because it allows one to dispense with this questionable assumption. We cannot here go into these problems and, fortunately, need not; for, whatever we answer to these questions, it remains true that the plans which are upset must be kept apart from the “plans” or decisions represented in the instantaneous curves.
249 It is not quite clear whether “undesigned investment” is identified with “an Involuntary accumulation of unsold goods” or whether the latter is only a special case of the former. If the former interpretation were correct, Mr. Hawtrey’s undesigned investment would be a narrower concept than Professor Ohlin’s difference between ex ante and ex post investment.
250 Capital and Employment, London, 1937, pages 176 and 177. See also Economic Journal, 1937, page 439, where Mr. Hawtrey discusses the relation between his and Ohlin’s concepts. The distinction between ex ante and ex post, designed and undesigned, S and I has been clearly-anticipated in Professor Robertson’s Banking Policy and the Price Level. His “spontaneous lacking” corresponds clearly to ex ante or designed investment and his “induced lacking” to undesigned investment, which is the difference between ex ante and ex post investment. (This was pointed out to me by Dr. J. G. Koopmans, The Hague.)
251 General Theory, pages 20 and 21, 210.
252 Economic Journal, Vol. 47, 1937, page 250. It is misleading to say that income must change, in order to ensure the equality of S and I. Whatever the level of income may be, S and I must be equal, because they are made so by definition. The change of level of income comes in as a condition only because Mr. Keynes takes the ‘multiplier’—‘the marginal propensity to consume’ (compare § 4 below for a definition of these concepts)—as a constant quantity. He assumes that there is a certain relationship between a (small) increase in investment and in income. Suppose, for example, the multiplier is 3 (in other words, the marginal propensity to consume is ⅔)—that is, to any small increment in I, corresponds an increment in Y three times as great. If that assumption is to be borne out by the facts, we must find that, whenever a change in investment has occurred, income must have changed by three times as much. But the multiplier (alternatively expressed: the marginal propensity to consume) need not be a stable magnitude, independent of the nature of the change in I” and the surrounding conditions. (This, Mr. Keynes himself has recognised.) Hence, if in a concrete case we find that income did not change as we expected on the basis of what we assumed about the multiplier, we shall not say ‘this is impossible, because S is not equal to I, or ‘S can now not be equal to I’, but we shall say the multiplier (marginal propensity to consume) was different from what we expected.
The same in slightly different formulation: If we assume (expect) something about the magnitude of the multiplier, we implicitly assume (expect) something about the change in income subsequent to a change, say an increase, in investment. Income must change, not because it is necessary to ensure the equality between S and I, but because we have assumed it by assuming the multiplier.
We have here an example of a confusion between a terminological relationship between symbols (in other words: a relationship between concepts by definition) and an empirical relationship between conceptually independent magnitudes. In other words: the impression is created that a statement is made about an alleged regularity in the real world, whilst in reality a rule is given for the consistent application of the terms. On the relationship between ‘multiplier’ and marginal propensity to consume’ in Mr. Keynes’ system, compare § 4 below and G. Haberler: ‘Mr. Keynes’ Theory of the Multiplier in Zeitschrift füt Nationalökonomie, Vol. 7, 1936, pages 299 et seq. On the logical and methodological principles involved, see T. W. Hutchinson: The Significance and Basic Postulates of Economic Theory, London, 1938, passim.”
253 Ibid., page 249.
254 Ibid. Cf. also General Theory, Chapter 7.
255 Further elaborations will be found in G. Haberler: “National Income, Savings and Investment”, in Studies in Income and Wealth, Vol. II, published by the National Bureau of Economic Research, New York, 1938.
256 In a series of (unpublished) lectures delivered at the London School of Economics, 1933, and in an unpublished paper submitted to the American Economic Association at its meeting in Atlantic City, December 1937. The history of the two groups of theories and of the attempts at bridging the gap between them will be traced in Professor Marget’a forthcoming Vol. II of his Theory of Prices.
257 See footnote 1 on page 40 above.
258 The English Capital Market, London, 1921 (3rd ed., 1934)
259 Economic Journal, Vol. 47, page 428.
260 Professor J. R. Hicks, too, in his book Value and Capital (which appeared—Oxford, 1939—when this edition was already in print) distinguishes between “real capital” theories of interest and “loanable funds” theories (page 153). He calls this a “serious division of opinion” which marks a “real dispute” But the real dispute has lately been complicated by a sham dispute within the ranks of those who adhere to the monetary approach.” This refers to the dispute between Mr. Keynes and his followers on the one hand, and the demand-for-and-supply-of-loanable-funds theorists on the other hand.
261 Cf. General Theory, Chapter 14, pages 175 to 193.
262 Loc ext., page 178.
263 In some contexts, Mr. Keynes and many other writers make a stronger assumption: they assume that when incomes rise, not only the absolute amount of saving rises, but also the proportion of income saved goes up. This is, for instance, implied by the widely accepted proposition that a more unequal distribution of the national income tends to increase the amount saved by society as a whole.
264 It has frequently been pointed out that some people may save less at a higher than at a lower interest rate, although it has been widely assumed that, for very low rates of interest, the saving incentive for the community as a whole tends to vanish.
265 These remarks are by no means intended to be exhaustive. The problem could be settled only by extensive empirical studies. Some further observations will be found in Chapter io, § 6, below. Here the aim is to caution the reader against accepting too easily the view now prevalent that the positive correlation between income and the amount of saving can be taken as a secure basis of further deductions for the purpose of explaining the business cycle as well as for long-run tendencies.
266 It would be easy to construct a three-dimensional diagram exhibiting the dependence of the rate of saving on the two factors: level of income and rate of interest. A complete theory would have to take still other factors into consideration—e.g., the rate of change of income.
267 Mr. Keynes has not included in his theoretical scheme (although he has made some slight allusions to it) the obvious fact that investment (demand for capital), must be assumed to depend, not only on the rate of interest, but also on the level of income.
Mr. J. R. Hicks and Mr. O. Lange, in their respective diagrammatic expositions of the Keynesian theory (“Mr. Keynes and the ‘Classics’; A Suggested Interpretation”, in Econometrica, Vol. 5, 1937, and “The Rate of Interest and the Optimum Propensity to Consume”, in Economica, February 1938), have filled that gap. It would, however, seem to be more correct to say that the investment demand depends on the rate of change rather than on the level of income. That amounts to introducing into the system the acceleration principle which is a dynamic relationship (in a sense which will be discussed in § 6 of this chapter).
268 Whether this theory, in spite of its admitted shortcomings, has not its merits, in relation to long-period equilibrium or as an ideal case realisable under certain special assumptions or as a purely theoretical standard of reference, we need not discuss in this connection, because we are here concerned more with the short-run (monetary) variety of interest theory which is used in business-cycle analysis.
269 Mr. Keynes accuses the “orthodox” theory of having overlooked these monetary influences; hence he must have the “pure” theory of interest in mind. Cf. his “The Theory of Interest” in Lessons of Monetary Experience, New York, 1937, page 147.
270 A. P. Lerner: “Alternative Formulations of the Theory of Interest”, in the Economic Journal, Vol. 48, June 1938, page 215
271 General Theory, page 174.
272 As is usual with economic terms, there are points of detail where the general usage is not unambiguous. They will be discussed presently.
273 This argument has been frequently expressed in recent years. See, for instance, J. M. Keynes, General Theory, page 174, and Economic Journal, 1937, pages 250-251; A. P. Lerner, “Mr. Keynes’ General Theory of Employment, Interest and Money” (International Labour Review, Vol. 34, October 1936, page 435; R. F. Harrod, Zeitschrift für Nationalökonomie 1937, page 494. R. F. Kahn, Economic Journal, Vol. 47, 1937, Page 671.
274 It is hoped that further details lying behind the concept of “velocity” may remain undiscussed—viz.,the fact that we have, strictly speaking, to distinguish between a “transaction-velocity”, an “income-velocity” and some other varieties, and correspondingly between a “transaction-k”, an “income-k”, etc., the formal nature of the relation between V and k—viz., that of reciprocity—remaining in all cases the same. On this, compare the literature quoted, above, Chapter 3, §6, page 62.
275 This has been frequently mentioned in connection with international flows of funds. Cf., for example, J. Viner: Studies in the Theory of International Trade, Chapters VI and VII, passim.
276 k usually refers to income; it is then the reciprocal of income velocity. But there is, as was pointed out above, a “transaction-k”. It will be observed that it does not matter whether we express the magnitudes involved (income, volume of transaction, average cash holding) in monetary or in “real” terms (e.g., in wheat, as Professor Pigou, following Marshall, does), because the denominator and numerator of the fraction would have to be deflated by the same index number, if we changed from one numéraire to another.
277 If we adopt this definition in respect to individual hoarding, and if we agree that any hoarding by society as a whole must be allocated to certain individuals, we have implicitly answered the terminological questions raised above as to the relation between the “hoarding” and “velocity” concepts. Suppose there is no change in the habits of payment; if, then, demand shifts in such a way that the income of people who hold a small proportion of their income in the shape of money (whose k is relatively small) decreases, while the income of people who hold a large proportion of their income in money (whose k is great) increases, velocity of circulation decreases for society, whilst nobody need have hoarded, on our definition. This would, for example, be the case if demand for agricultural products increases (assuming that the farmer’s k is greater than the industrialist’s k).
278 Mr. Keynes is, of course, quite right in saying that “the decision to hoard is not taken absolutely” (General Theory, page 174). It may depend on the price obtainable for certain assets. Given a certain situation, we may conceive of a demand curve for idle balances plotted against the rate of interest.
279 General Theory, page 174.
280 Ibid., page 167. Precisely the same definition has been given by Professor Albert Hahn in his Volkswirtschaftliche Theorie des Bankkredits, Tübingen, 1920.
281 Ibid., page 167.
282 Economic Journal, 1937, page 431. “The fact that the rate of interest measures the marginal convenience of holding idle money need not prevent it from measuring also the marginal inconvenience of abstaining frcm consumption. Decumulation, as well as keeping-hoarded, is an alternative to keeping invested.”
283 Keynes: General Theory, page 173, bottom.
284 Everybody means by “the rate of interest” the rate of interest on money loans—money loans of different duration, security, etc. By a money loan, we mean a loan which is expressed in terms of money. Interest and principal could be expressed in terms of other things than money. But even if they are expressed in money, the loan need not be paid out or repaid in money (cash). It may be given and repaid in kind and still be a money loan. Hence, what is needed is a numéraire and not actual money of exchange.
285 On the various meanings with which it is used by Mr. Keynes in different places in his writings, compare, especially, Max Millikan: “Liquidity-Preference Theory of Interest”, in American Economic Review, Vol. 28, June 1938, pages 247 et seq.
286 General Theory, page 194.
287 Ibid., pages 140, 165, 184 and 185.
288 General Theory, page 170.
289 Ibid., page 195.
290 Compare footnote 1 on page 59 (Chapter 3, § 6). The locus classicus of the discussion of these problems is Professor Marget’s Theory of Prices, New York, 1938.
291 General Theory, page 196.
292 Ibid., page 170.
293 Ibid., page 197.
294 Ibid., page 199. Mr. Keynes realises that this is not quite correct, because “the amount of cash which an individual decides to hold to satisfy the transactions- . . . and precautionary-motive is not entirely independent of what he is holding to satisfy the speculative motive”.
295 We think of the velocity of M, whilst Mr. Keynes (General Theory, page 201) speaks of the velocity of M1 alone. Mr. Keynes speaks further-more of income velocity rather than of transactions velocity.
296 A very instructive mathematical and diagrammatic exposition of these relationships and of Mr. Keynes’ General Theory, in toto, has been given by Dr. Hicks: “Mr. Keynes and the Classics”, Econometrica, April 1937, and by O. Lange: “The Rate of Interest and the Optimum Propensity to Consume”, in Economica, February 1938, pages 12 et seq. Of the latter, Mr. Keynes says that it “follows very closely and accurately [his] line of thought”. (Economic Journal, Vol. 48, June 1938, page 321.)
297 Mr. Keynes himself states his theory sometimes in terms of liquidity preference in the wider sense and sometimes in terms of liquidity preference proper. An example of the latter will be found in Economic Journal, 1937, page 250. “If we mean by ‘hoarding’ the holding of idle balances, then my theory of the rate of interest might be expressed by saying that the rate of interest serves to equate the demand and supply of hoards”.
298 This case is an example of the demand for “finance” for planned investment, which is discussed below, page 212.
299 Economic Journal, Vol. 47, 1937, page 666.
300 Ibid., page 667.
301 Ibid., pages 663 et seq.
302 Economic Journal, loc. ext., page 665.
303 Compare Professor Robertson’s article, “Mr. Keynes on Finance”, in Economic Journal, Vol. 48, June 1938, page 314 et seq., and Mr. Keynes’ reply, ibid., page 318. See also E. S. Shaw, “False Issues in the Interest-Theory Controversy”, in Journal of Political Economy, Vol. 46, December 1938, page 838.
304 Economic Journal, Vol. 47, 1937, page 666.
305 Economic Journal, Vol. 48, 1938, page 319.
306 General Theory, page 185. This passage conveys the incorrect impression that, in Mr. Keynes’ opinion, an increase in investment does not tend to raise tne interest rate.
307 This point was also made by T. W. Hutchinson: The Significance and Basic Postulates of Economic Theory, London, 1938, pages 44 and 45.
308 Compare the definition of this concept given above on page 210.
309 Since the propensity to save is equal to 1 minus the propensity to consume, any proposition regarding the propensity to save can be translated into a proposition regarding the propensity to consume and vice versa.
310 See footnote 1 page 321, in Economic Journal, June 1938.
311 Economica, February 1938.
312 Hence we must conclude that Dr. Lange is not right when he attributes, rather unqualifiedly, to Mr. Keynes, not his general theory, but a special case of it—viz., that case where the “interest elasticity of the demand for liquidity is infinite” (page 19). It seems fair to say that Mr. Keynes holds that this situation obtains under special circumstances—viz., in deep depressions. It is “depression economics” (as Dr. Hicks, loc. cit., says) and not the “general theory” For further discussion of this special case, see the text below, page 218.
313 General Theory, page 200.
314 Ibid.
315 Some economists, however, have interpreted Mr. Keynes’ theory to mean that an increase in the quantity of money could operate on the economic system only via the rate of interest. For example, Mrs. J. Robinson, in a review of Professor Bresciani-Turroni’s Economics of Inflation, remarks: “The author assumes that an increase in the quantity of money was the root cause of the inflation [in Germany, in 1919-1923]. But this view it is impossible to accept. An increase in the quantity of money no doubt has a tendency to raise prices, for it leads to a reduction in the interest rate, which stimulates investment and discourages saving, and so leads to an increase in activity. But there is no evidence whatever that events in Germany followed this sequence” (italics not in the original). Economic Journal, Vol. 48, 1938, page 509.
316 The same difficulties have to be faced by any two-dimensional analytical apparatus when applied to such a complex phenomenon as the demand for idle balances and the rate of interest. Compare on this point M. Millikan, loc. ext., pages 254 et seq.
317 Lange, op. cit., pages 18 and 19.
318 Hicks, op, cit., page 154.
319 Loc. cit., pages 154 and 155. Compare also Professor Hicks’ book, Value and Capital, Oxford, 1939, especially Chapter XI.
320 General Theory, page 203.
321 When put in terms of asset prices, it becomes clear that it is an optical illusion to say that the rate of interest cannot fall farther because it is “so near to zero” Between, say, one per cent and zero per cent, there are still as many intermediate positions as there are between the price at $400 of a $100 4% bond (corresponding to a capitalisation at an interest rate of 1%) and the infinitely high, price of the same bond corresponding to a capitalisation at a rate of zero per cent.
322 Capital and Employment, 1937, Chapter VII. See also Mr. Kaldor’s reply to Mr. Hawtrey’s criticism of Mr. Keynes, “Mr. Hawtrey on Short and Long Term Investment in Economica, November 1938, pages 464 and 465.
323 General Theory, page 207. It must, however, be admitted that there are many passages in Mr. Keynes’ writings which are difficult to reconcile with this pronouncement and seem to assume the actual existence of cases of an insatiable desire for liquidity.
324 It should be understood that, according to Mr. Keynes’ theory, the two policies are alternative means only in one respect, which is, however (in the present context), the important one. Both policies serve to increase the quantity of money in terms of real purchasing power, “in terms of wage units” as Mr. Keynes says. On page 234 of his General Theory, Mr. Keynes says, for example: “The only relief [for an excessive liquidity preference—that is, for an extreme desire to hoard]—apart from changes in the marginal efficiency of capital—can come . . . from an increase in the quantity of money, or—which is formally the same thing—a rise in the value of money.” (Note that this passage contains an explicit statement to the effect that a fall in wages and prices will eventually bring relief. We wish, however, by no means to deny, nor does Mr. Keynes, that in many other respects the two policies are very different and cannot be regarded, from a practical point of view, as good substitutes. Cf. § 5 of this chapter below.)
325 Chronic unemployment with stable money wages is no proof of an absolute liquidity preference.
326 General Theory, pages 246 and 247.
327 Ibid., page 184. In the course of the discussion, Mr. Keynes is sometimes inclined to forget these limitations of his theory. This has misled some economists to overlook them altogether. The usefulness of the system ci early depends on the degree of independence of these variables. If they were highly interdependent, they could not be regarded as “ultimate independent variables”. This, is, of course, a difficulty which any interdependence theory, especially one in macro-economic terms, has to face. It is impossible to build up a theory which explains national income and employment in terms of a few complex, strictly independent factors without having regard to their internal structure. Such a procedure can yield only rough approximations. Mr. Keynes is well aware of these difficulties. See, for example, his remarks, General Theory, page 297.
328 In particular, the assumption regarding the stability of the wage unit, with its implication of rigid money wages, is apt to be lost sight of, but should be well kept in mind. (This will be discussed at greater length below, § 5 of this chapter.)
329 It may be observed, en passant, that the marginal propensity to consume of an individual may conceivably be greater than unity: that is to say, an individual may be induced by an increase in his income to spend more than that increment on consumption. This need not, however, make his average propensity to consume greater than unity—in other words, it need not mean dissaving. (An average propensity to consume greater than unity means that C > Y—i.e., that the individual dissaves, “lives on his capital”.) Mr. Keynes does not consider this case. (Compare, however, Mr. G. R. Holden’s paper “Mr. Keynes’ Consumption Function, A Rejoinder”, Quarterly Journal of Economics, August 1938, and Mr. Keynes’ reply Ibid., November 1938.)
330 It will be observed that what is meant is not the time rate of consumption (saving), the amount consumed (saved) per unit of time, but the income rate, amount consumed (saved) per unit of income. This rate of consumption is measured by  the rate of saving by
 Since S = Y − C, the rate of saving is i minus the rate of consumption:

331 Mr. Keynes calls it the “logical theory of the multiplier” (General Theory, page 122).
332 The idea that investment stimulates consumption is almost as old as business-cycle theory. That it is inherent in the Wicksellian theory of the cumulative process of expansion has already been said (see Chapter 3, pages 33 et seq., above). Mr. Kahn, among others, has analysed the problem in his article “The Relation of Home Investment to Unemployment” (Economic Journal, June 1931), and has contributed the word “multiplier”.
333 See, for example, A. D. Gayer, Public Works in Prosperity and Depression (New York, 1929), and J. M. Clark, Economics of Planning Public Works (Washington, 1935).
334 This latter relationship is described by the acceleration principle.
335 General Theory, pages 96 and 114.
336 Cf. Elizabeth W. Gilboy, “The Propensity to Consume” in Quarterly Journal of Economics, Vol. 53, November 1938, and Mr. Keynes’ reply, ibid., May 1939.
337 “Short Period Variations in the Distribution of Incomes Review of Economic Statistics, Vol. 19, 1937 (pages 133 to 143) and the comments by F. C. Dirks, Review of Economic Statistics, Vol. 20, and rejoinder by Dr. Staehle, ibid.
338 Compare, for instance, this case with another one where the same road is built with less labour and at a much lower cost, and the superfluous workers receive a dole. Part of the total money spent ‘is investment and the other part consumption, whilst, in the case mentioned in the text, all is counted as investment.
339 These problems are discussed at great length in various contributions to Studies in Income and Wealth, Vol. I and II (ed. by National Bureau of Economic Research, New York, 1937 and 1938).
340 General Theory, page 123.
341 Ibid., page 122.
342 This is also the opinion of Mr. E. Lundberg (cf. Studies in the Theory of Economic Expansion, London, 1937, Page 36), who believes that the multiplier will exhibit a cyclical movement over time.
343 General Theory, page 297
344 Ibid., pages 313 et seq.
345 Compare, for example, General Theory, pages 31, 98 and 105.
346 See General Theory, pages 41 and 247. That the wage-unit—that is, “the money-wage of a labour unit”—must be given, is a highly important fact which is frequently overlooked and will come up for discussion below (page 238). It implies that an equilibrium with less than full employment can exist only if money wages are rigid.
347 For further details and hypotheses, see Chapter 11, section B, below.
348 For further details and other hypotheses, see Chapter 11. section A, below.
349 General Theory, page 16.
350 General Theory, page 15. Italics in the original. An extensive discussion of this definition will be found in J. Robinson, Essays in the Theory of Employment, London, 1937, Part I. See also Viner’s criticism, Quarterly Journal of Economics, Vol. 51, 1936, pages 147 et seq.
351 Compare the following statement by Mr. J. E. Meade, “A Simplified Model of Mr. Keynes’ System” (Review of Economic Studies, Vol. IV, page 99): “If we suppose that the money-wage rate would fall so long as any labour were unemployed, the system cannot be in equilibrium without full employment.” Professor Alfred Amonn also points out that only with monopolistic wage rigidities can there be equilibrium with less than full employment. “Grundfragen der Konjunkturtheorie und Konjunkturpolitik” in Festschrift für Oskar Engländer, Brünn, 1937 passim.
352 General Theory, page 17. Professor Viner considers this an unwarranted concession to the classical doctrine, as it is quite possible that real wages may rise with increasing employment. Cf. Quarterly Journal of Economics, Vol. 51, 1936, pages 149 and 150. This has been shown statistically by J. T. Dunlop: “The Movement of Real and Money Wage Rates”, Economic Journal, Vol. 48, 1938, pages 413 et seq. Mr. Dunlop’s article has induced Mr. Keynes to modify his position somewhat. See his paper: “Relative Movements of Real Wages and Output”, Economic Journal, March 1939.
353 General Theory, page 11.
354 Loc. cit., page 13. Mr. Keynes adds: “This will be our contention.”
355 Loc. cit., page 12.
356 Loc. cit., same page, footnote 1. See also page 269.
357 See, for example, Mr. A. P. Lerner: “Mr. Keynes’ ‘General Theory of Employment, Interest and Money’”, International Labour Review, Vol. 34, 1936. Mr. Lerner there “proves” that prices must fall “in just the same proportion as wages” (pages 441 and 442). It is true that he qualifies that statement by admitting “that a reduction of money-wages may have all sorts of indirect influences”. But this qualification is again qualified, and the short paragraph devoted to the matter gives a very cursory summary of Mr. Keynes’ analysis.
358 See Chapter 11, § 9, below.
359 General Theory, page 262.
360 General Theory, page 257 and passim.
361 General Theory, page 253 (italics not in the original). For this reason, it is clear that the alleged intractability of slump conditions (discussed in Chapter 17 of the Theory, especially on pages 229 to 235) can refer only to conditions in which money-wages are not allowed to fall indefinitely. It is therefore as true to attribute the persistence of unemployment to the rigidity of wages and prices as to attribute it to the peculiarity of money as compared with other assets. This does not, of course, exclude the view that unemployment may be relieved—perhaps more effectively—by measures other than a reduction in wages—e.g., by an increase in the quantity of money combined with Government spending.
362 General Theory, page 269.
363 It is always possible to conserve the favourable effects of a policy of wage reductions in its cost aspect, and at the same time to eliminate the unfavourable ones, by combining the policy of wage reductions with a policy of public works (or similar measures), so as to make sure that total purchasing power does not fall.
364 General Theory, page 219. See also however the passage on page 203 already quoted.
365 The most balanced and best considered statement is to be found in Professor Hansen’s Full Recovery or Stagnation, New York, 1938, passim, and in his paper, “Economic Progress and Declining Population Growth”, American Economic Review, March 1939. A very good but rather unqualified statement is to be found in An Economic Program for American Democracy by Paul M. Sweezy, R. V. Gilbert and others, New York, 1938. Compare also Gerhard Colm and Fritz Lehman, Economic Consequences of Recent American Tax Policy, Supplement I to Social Research, New York, 1938; and G. Haberler, “Interest Rate and Capital Formation”, in Capital Formation and its Elements, ed. by the National Industrial Conference Board, New York, 1939.
366 “Final” in a relative sense.
367 Professor Frisch (“Propagation and Impulse Problems”, in Economic Essays in Honour of Gustav Cassel, London, 1933, Page 172) uses the term “macro-analysis” in the sense of “general” (embracing the economic process as a whole) and “micro-analysis” in the sense of “partial equilibrium analysis”. He points out that a general interdependence theory can be given in all detail (in our terminology: in microscopic terms) only “if we confine ourselves to a purely formal theory. Indeed, it is always possible by a suitable system of subscripts and superscripts, etc., to introduce practically all factors which we may imagine (all individual commodities, all individual entrepreneurs, all individual consumers, etc.), and to write out various kinds of relationship between these magnitudes, taking care that the number of equations is equal to the number of variables. Such a theory, however, would have only a rather limited interest. In such a theory it would hardly be possible to study such fundamental problems as the exact time, shape of the solutions, etc.” (page 172).
368 Cf., for example, Frisch, loc. cit., and J. Tinbergen, “Suggestions on Quantitative Business-cycle Theory”, Econometrica, Vol. 3, 1935, page 241.
369 Usually, the assumption is made that, after a change in the data has occurred, a certain period of time must elapse before a new equilibrium emerges. Comparative statics in the strict sense confines itself to describing the two equilibria, the starting-point and the destination of the economic system. Any attempt, on the other hand, at analysing in detail the process of transition from one equilibrium to the other (e.g., in Marshallian manner, by distinguishing between short- and long-period effects) marks the first step towards a “dynamisation” of static theory. For it leads inevitably to the recognition of the fact that, as the result of certain reactions, the process of transition, and hence the final equilibrium, may be different. It also suggests that, after a given change in the data, a stable position will be reached only under special assumptions (stability conditions), which cannot be taken for granted without careful analysis.
370 Frisch, loc. cit., page 171. Tinbergen formulates: “A theory [is called] ‘dynamic’ when variables relating to different moments appear in one equation” (loc. cit., page 241).
371 Professor Tinbergen, loc. cit., has enumerated many different dynamic relationships which have been used at one time or another in business-cycle theory.
372 This was the definition of an endogenous theory. Cf. Chapter i, page 9.
373 Economica, February 1938. Mr. Keynes has accepted this exposition as correct. See also J. E. Meade: “A Simplified Model of Mr. Keynes’ System”, in the Review of Economic Studies, Vol. IV, 1936/37, page 98.
374 The Trade Cycle, Oxford, 1936.
375 “A Theory of the Business Cycle”, in Review of Economic Studies, Vol. IV, February 1937, pages 77 et seq., reprinted in Essays in the Theory of Economic Fluctuations, London, 1939.
376 These theories, although inspired by Mr. Keynes’ General Theory, can be and have been expressed in a more classical terminology.
377 General Theory, pages 24, 25, 46 et seq., 141, 147 et seq. Compare also what has been said earlier in this book in Chapter 6, § 2, on the rôle of expectations.
378 Expectations may almost be called “non-operational concepts”. The only way of finding out something about them would be to question individual business-men—a very questionable procedure.
379 From a strictly logical point of view, the psychological link between the past and the present consisting of expectations may be dropped and the theory stated in terms of a direct relationship between observable phenomena at different points of time. Psychologically it may, however, be useful to retain the word “expectations”, or a similar concept, as a link, because it reminds us of the fact that those dynamic “laws” (relationships) are nothing but hypotheses; that they can hardly ever be stated very precisely in great detail; and that they may always be subject to rapid change “without notice”.
380 London, 1937, especially Chapter IX.
381 Compare the following remarks from his book: “The introduction of causal elements linking up economic factors in successive periods of time means a more radical departure from equilibrium-theories than the dynamisation claimed by Myrdal, and later by Keynes, when paying attention to the independent rôle of expectations and anticipations. . . . The introduction of expectations can, in a way, be said to mark the stepping-stone to dynamic analysis, because they express the connection linking present plans and activities with future events. However, economists have indulged in too much purely formal exercise with this term. . . . It is sensible to link actions with expectations, only if the latter can be explained on the basis of past and present economic events. Total lack of correlation here would mean the complete liquidation of economics as a science. . . . In every process of economic reasoning, we. . . . have to make certain assumptions, often not specified, concerning the relation between expectations, on the one hand, and current or past prices, profits, etc., on the other” (loc. cit., page 175).
382 Dr. Lundberg is, of course, well aware of these limitations.
383 See, for example, An Economic Approach to Business-cycle Problems and the companion volume, Lesx Fondements Mathématiques de la Stabilisation du Mouvement des Affaires, Paris, 1937 and 1938. For a detailed discussion of the statistical methods and measurements involved, compare Professor Tinbergen’s memoranda published by the Economic Intelligence Service of the League of Nations, Geneva, 1939, in the series: Statistical Testing of Business-Cycle Theories.
384 Hence this branch of economics has been cultivated by mathematical economists. See especially the work of Frisch and Tinbergen.
- 1Cf. J. M. Clark, Strategic Factors in Business Cycles, New York, 1935. pages 4-5 and passim.
- 2See especially Tinbergen: “Suggestions on Quantitative Business Cycle Theory” in Econometrica, Vol. Ill, No. 3, July 1935, page 241.
- 3See his book: Strategic Factors in the Business Cycle, passim.
- 4What is to be regarded as “outstanding” and “plausible” is, of course, a matter of dispute. As there is always something happening somewhere, it is always possible to find some external events which can be made the basis of a tentative explanation.
- 5This special purpose explains the difference between the following exposition and the classification of theories and theorists given in such works as A. H. Hansen: Business Cycle Theories, Boston, 1927; W. M. Persons: “Theories of Business Fluctuations” (Quarterly Journal of Economics, Vol. 41, reprinted in Forecasting Business Cycles, New York, 1931); F. A. Hayek: Monetary Theory and the Trade Cycle, London, 1933; Macfie: Theories of the Trade Cycle, London, 1934.
- 6For this reason, anything like perfect regularity in respect of the amplitude, length, intensity and concomitant symptoms of the cyclical movement is a priori improbable.
- 7The Lessons of Monetary Experience, page 131.
- 8Trade and Credit, London, 1928, page 98.
- 9Currency and Credit, 3rd ed., London, 1928, page 153.
- 10Op. cit., page 171.
- 111913, page 186.
- 12Cf. his Trade Depression and the Way Out, 2nd ed., pages 29-31 and 133-135, Capital and Employment, pages 85-87, “A Credit Deadlock”; and his contribution to The Lessons of Monetary Experience (edited by A. D. Gayer), “The Credit Deadlock”, pages 129-145.
- 13Monetary Reconstruction, 2nd ed., London, 1926, page 135.
- 14Currency and Credit, 3rd ed., page 155.
- 15No attempt has been made to establish priorities or to trace the various lines of thought to their historical origins.
- 16See his paper “Money and Index-Numbers” in Journal of the Royal Statistical Society, 1930, reprinted in The Art of Central Banking, pages 303-332.
- 17See below Ch. 3, §§ 8,16, and Part II, Ch. 11.
- 18It has been questioned whether this process of saving and investment runs smoothly. A great number of writers believe that the process of saving is likely to produce serious disturbances (a) because saving produces depression in the consumption industries which then spreads to the higher stages, (b) because money which is saved frequently disappears on the way and is not invested (deflation), (c) because increased investments eventually bring about an increase in the production of consumers’ goods, which cannot be sold at the prevailing prices unless the flow of money is increased. But it is not with these alleged frictions and disturbances that we are here concerned. They will have to be discussed at a later stage of our enquiry. The theorists now under review believe that ordinarily the process of saving and investment runs smoothly. According to them, troubles arise only if voluntary saving is supplemented from “inflationary sources”, that is, by new bank credit or by expenditure from money hoards (which is equivalent to by a rise in the velocity of circulation of money).
- 19A. H. Hansen and H. Tout, in “Investment and Saving in Business Cycle Theory,” Econometrica, April 1933, have pointed out the underlying assumptions.
- 20Ibid., page 58.
- 21The concept “forced saving” has a long history (cf. F. A. HAYEK, “A Note on the Development of the Doctrine of Forced Saving” in Quarterly Journal of Economics, Vol. 47, page 123). In addition to the writers of the present group, Professor Schumpeter has given it a prominent place in his account of the upward phase of the cycle. (See his Theory of Economic Development, English translation from the last German edition, 1934. First German edition, 1911.) Unlike the monetary over-investment theorists, however, he does not use the alleged peculiarities of forced saving to explain the crisis. This point will be taken up later (cf. Ch. 5, § 3). Recently the doctrine of forced saving has been attacked by Mr. Keynes (The General Theory of Employment, Interest and Money, pages 79-81, 183). But, as Professor Robertson has pointed out (cf. “Some Notes on Mr. Keynes’ General Theory of Employment” in Quarterly Journal of Economics, Vol. 51, 1936, page 178), Mr. Keynes’ objections are purely verbal. He banishes the word, but is forced to recognise the thing which the word denotes, though in another dress, when he says that, under the pressure of investment which is imperfectly foreseen, there may occur a “temporary reduction of the marginal propensity to consume” (loc. cit., pages 123 and 124).
- 22The fact that the production of consumers’ goods can be expanded only at the expense of a reduction in the production of producers’ goods and vice versa does not, of course, hold if there are idle factors of production available. Furthermore, it does not preclude the possibility that, besides this physical connection between the production of the two categories of goods, there may be connections of another nature—e.g., an increase in the production of consumers’ goods may tend to stimulate the production of producers’ goods, as postulated by the “acceleration principle” (see below, § 17 et seq. of this chapter), or there may be a causal connection in the opposite direction as postulated by the so-called “multiplier” (see below, passim).
- 23Mr. Durbin argued that if the rate of increase of production is constant (say 10% per year) an increasing amount of money can be put into circulation without raising prices, because the absolute increase in output per unit of time increases (the 10% is reckoned from an are ever-increasing total). Evidently, different quantitative assumptions can be made, and it is impossible to say which one corresponds best to reality. For further comments on the failure of the writers of the present school to make their assumptions quantitatively precise, see the following paragraph.
- 24Kapital und Produktion, Vienna, 1934, page 195, and “Die Produktion unter dem Einfluss einer Kreditexpansion”, in Schriften des Vereins für Sozialpolitik, Vol. 173, 1928.
- 25Banking Policy and the Price Level, 1932 ed., page 48.
- 26Ibid., page 57.
- 27See Les Crises industrielles en Angleterre, Paris, 1913 (translated from the Russian). For further references, see A. H. Hansen, Business Cycle Theory, 1927, Ch. IV.
- 28Ibid., page 131, and Monetary Reconstruction, page 133.
- 29Capital and Employment, page 86.
- 30Kapital und Produktion, Vienna, 1934.
- 31“Relations between Capital Goods and Finished Products in the Business Cycle” in Economic Essays in Honour of Wesley Clair Mitchell, New York, 1935.
- 32See F. Vito: “Il Risparmio forzato e la teoria di cicli economici” in Revista internazionale di scienze sociali, 1934, and “Die Bedeutung des Zwang-sparens für die Konjunkturtheorie” in Beiträge zur Konjunkturlehre, 1936.
- 33Hayek, op. cit., pages 160 and 161.
- 34Since the appearance of the first edition of this book, a very lucid analysis, also in “real” terms but much more elaborate than the above, has come to the author’s notice: Autour de la crise américaine de 1907, ou Capitaux-réels et Capitaux-apparents, by Marcel Labordère (enlarged reprint from the Revue de Paris of February 1st, 1908), Paris, 1908. This important study has been entirely overlooked by the whole literature on the subject.
- 35The following statement of a prominent adherent of the monetary over-investment theory is significant: “This theory does not make the pretence of being the only explanation of all cycles and crises that have ever occurred, nor does it pretend that it states unconditional necessities” (F. Machlup, “Professor Knight and the ‘Period of Production’” in Journal of Political Economy, Vol. 43, October 1935, page 622.
- 36Les crises économiques, Paris, 1922; 2nd ed., 1930.
- 37Such an over-narrow interpretation of the “Austrian” theory seems to be implied in Professor D. H. Robertson’s article: “Industrial Fluctuations and the Natural Rate of Interest” in Economic Journal, Vol. 44, 1934, Page 653.
- 38See, in particular: Keynes: A Treatise on Money, London, 1930. Robertson: Banking Policy and the Price Level, and the controversy in Economic Journal of the following dates: Robertson, “Mr. Keynes’ Theory of Money”, September 1931; Keynes, “A Rejoinder to Mr. Robertson”, September 1931; Robertson, ‘‘Saving and Hoarding”, September 1933, and three notes on “Saving and Hoarding”, by Keynes, Hawtrey and Robertson, December 1933.
- 39It is not quite clear whether his Swedish colleagues all agree on this.
- 40“Monetary Expansion and the Structure of Production” in Social Research, Vol. I, New York, November 1934, pages 434 et seq. Similar objections had been raised by Piero Sraffa, Economic Journal, March 1932.
- 41This qualification is necessary, because there are other facts which influence the proportion mentioned in the text. If, for example, two or more successive stages of production are merged and run by a single firm instead of by two independent firms, the transfer of the intermediate goods from the former to the latter will from that time on be accomplished without the help of money. The amount of money required in the business sphere is reduced by such an act of integration.
- 42In the earlier versions of the theory, the assumption was made, more or less explicitly, that the discrepancy between the equilibrium rate and money rate of interest is always brought about by a lowering of the money rate—that is, from the supply side. It is now pretty generally accepted that the situation is more complex and that the equilibrium rate is likely to move upward under the influence of psychological forces, price changes, inventions and discoveries, etc.
- 43HAYEK: Prices and Production, 2nd ed., London, 1934, page 57.
- 44In so far as entrepreneurs repay loans to the banks, they find themselves in possession of a real surplus, since their obligations have remained unchanged, while their receipts, etc., have risen owing to the rise in prices. This surplus may, and probably will, to a certain extent be utilised for increased consumption. Professor Robertson has drawn attention to this consideration: see his Banking Policy and the Price Level, 2nd ed., London, 1932, page 73. A further factor which operates in the direction of increasing demand for consumers’ goods is the fact that, with rising prices, the consuming public is likely to dishoard and “to hurry on with the purchase of goods (such as clothes and motor-cars) of which the exact moment of purchase can be varied within pretty wide limits” (Robertson, op. cit., page 75).
- 45Professor Hayek in particular has laid down the methodological rule that the analysis of the cyclical movement should never start on the assumption of existing unemployment, because that would beg the question of why unemployment can exist at all. This postulate would seem to narrow down unduly and quite unnecessarily the scope of such analyses.
- 46It may be noted once more that these words used by Professor Ohlin are rather misleading. Strictly speaking, no process is needed, because S and I ex post are equal at any moment of time. The word “process” suggests—erroneously—that there is only a tendency towards their becoming equal at the end of the process and that they are unequal at the beginning and during that process. In reality, according to the definition given, they are equal at any moment of time.
- 47If competition in the labour market and the mobility of labour are imperfect, the condition of full employment can, of course, be relaxed.
- 48Geldwertstabilisierung und Konjunkturpolitik, Jena, 1928, pages 56-61.
- 49This problem has been well discussed by E. Lundberg, loc. cit., passim.
- 50Cf., e.g., the highly interesting analysis of the cyclical movement on the basis of the Cassel-Spiethoff theory by Professor Georg Halm in his article “Das Zinsproblem am Geld- und Kapitalmarkt” in Jahrbücher für Nationalökonomie und Statistik, Vol. 125, 1926, pages 1-34 and 97-121.
- 51The durable means of production constructed during the upswing outlast, of course, the boom. But the contention is that they are lost economically. They are not used at all or axe used in such a way that their marginal product does not cover the cost of reproduction. It should, however, be noted that important qualifications are called for in respect of permanent goods or instruments where the cost of maintenance is negligible compared with production cost.
- 52We need not go into the causes which give a country an advantage in the production of this or that type of goods. They range from climatic conditions and the quality of the soil to the structure of the tariff and social legislation. Cf. B. Ohlin, Interregional and International Trade, passim, Cambridge, Mass. (U.S.A.), 1933.
- 53An excess of ex ante saving over ex ante investment, we have seen, leads to a deficiency of demand for consumers’ goods and causes losses to the retailers. This is one of the “processes” which bring about equality between S and I ex post. Clearly, if this construction is to make sense, ex ante saving cannot be interpreted as saving out of a future income. That could not affect retail sales now. To be sure, expectations about future income may affect present saving as a motive. But so will expectations about a hundred other things, and the manner in which, and extent to which, they affect the present situation is by no means uniquely determined.
- 542nd ed., pages 55 et seq.
- 55Hayek: “Capital and Industrial Fluctuations” in Econometrica, Vol. II, April 1934, page 161. Reprinted as Appendix to 2nd ed. of Prices and Production. See also E. F. M. Durbin: Purchasing Power and Trade Depression, London, 1933, pages 153-155. The latter concludes that the crisis is a purely monetary phenomenon, brought about by the refusal of the banks to continue the expansion of credit.
- 56Cf. C. Bresciani-Turroni, “The Theory of Saving” in Economica, 1936, pages 165 et seq.
- 57See Theory of Social Economy, revised ed., London, 1932, Vol. II (translated from the German).
- 58See especially L. Robbins: The Great Depression, London, 1934.
- 59See Spiethoff’s article “Krisen” in the Handwörterbuch der Staatswissenschaften, Vol. VI, 4th ed., Jena, 1925, page 49.
- 60See: Crises and Cycles, London, 1936 (translated from the German). “Geldtheorie und Weltkrise” in Deutscher Volkswirt of September 25th, 1931. “Praktische Konjunkturpolitik” in Weltwirtschaftliches Archiv, 34. Band, 1931. “Trends in German Business Cycle Policy” in Economic Journal, September 1933.
- 61Op. cit., page 74.
- 62Kapital und Produktion, Vienna, 1934, pages 208 et seq.
- 63Loc. cit., page 251.
- 64See footnote 1 on page 40 above.
- 65See especially L. Robbins: The Great Depression, London, 1934.
- 66This idea is fundamental to the Neo-Marxian theory of Imperialism of such writers as Rosa Luxemburg, Akkumulation des Kapitals, and Fritz Sternberg, Imperialismus (1928). For a brief review, criticism and references to this literature compare H. Neisser, Some International Aspects of the Business Cycle, Philadelphia, 1936, pages 161-172.
- 67Professor J. R. Hicks, too, in his book Value and Capital (which appeared—Oxford, 1939—when this edition was already in print) distinguishes between “real capital” theories of interest and “loanable funds” theories (page 153). He calls this a “serious division of opinion” which marks a “real dispute” But the real dispute has lately been complicated by a sham dispute within the ranks of those who adhere to the monetary approach.” This refers to the dispute between Mr. Keynes and his followers on the one hand, and the demand-for-and-supply-of-loanable-funds theorists on the other hand.
- 68On this subject, compare M. W. Holtrop: De Omloopssnelheid van het geld, Amsterdam, 1928, and “Die Umlaufsgeschwindigkeit des Geldes” in Beiträge zur Geldtheorie, ed. by Hayek, Vienna, 1933, pages 115-211. Compare further J.Marschak: “Volksvermögen und Kassenbedarf” in Archiv für Sozialwissenschaft u. Sozialpolitik, Vol. 68, 1932, pages 385-419, and “Vom Grössensystem der Geldwirtschaft,” loc. cit., Vol. 69, 1933, pages 492-504. H. Neisser: Der Tauschwert des Geldes, Jena, 1928. “Der Kreislauf des Geldes” in Weltwirtschaftliches Archiv, 1931, Vol. 33, pages 365-408. “Volksvermögen und Kassenbedarf “in Archiv für Sozialwissenschaft u. Sozialpolitik, Vol. 69, 1933, pages 484-492. A. W. Marget: “A Further Note on Holtrop’s Formula for the ‘Coefficient of Differentiation’ and Related Concepts” in Journal of Political Economy, Vol. 41, pages 237-241 and “The Relation between the Velocity of Circulation of Money and the Velocity of Circulation of Goods”, loc. cit., Vol. 40, 1932, pages 289-313 and 477-512. J. Schumpeter: “Das Sozialprodukt und die Rechenpfennige” in Archiv für Sozialwissenschaft u. Sozialpolitik, Vol. 44, pages 627-715. The whole literature on this subject is well reviewed and summarised by Professor H. S. Ellis, German Monetary Theory 1905-1933 (Cambridge, Mass., 1934), Part II, and by A. W. Marget, The Theory of Prices. A Re-examination of the Central Problems of Monetary Theory, Vol. I, New York, 1938, passim.
- 69“A Non-monetary Cause of Fluctuations in Employment” in Economic Journal, September 1914.
- 70In some contexts, Mr. Keynes and many other writers make a stronger assumption: they assume that when incomes rise, not only the absolute amount of saving rises, but also the proportion of income saved goes up. This is, for instance, implied by the widely accepted proposition that a more unequal distribution of the national income tends to increase the amount saved by society as a whole.
- 71“A Suggestion for a Theory of Industrial Depressions” in Quarterly Journal of Economics, May 1903.
- 72Strigl, op. cit., Anhang I. It may be added that, owing to the existence of the various reserves which will have been accumulated during the depression, the expansion can go far with little or no help from the banks.
- 73This statement is somewhat simplified for purposes of exposition. It is here tacitly assumed that the demand for, and supply of, the finished product jumps suddenly at the beginning of a new year to the extent of 10 per annum. Simultaneously, new machines must be available to the extent of 50, which, added to the replacement output of 50 per annum, brings the total machine output for the year to 100. It would be more realistic perhaps to suppose that the rise in demand comes about gradually and evenly in the course of the year. In this case the machine output would, as before, be 100 (i.e. an increase of 50 over the year before the expansion began); but the augmentation of the output of the finished product would amount only to 10/2=5. It is further assumed that machines retain their productive efficiency unimpaired throughout their lifetime.
- 74Mr. Keynes has not included in his theoretical scheme (although he has made some slight allusions to it) the obvious fact that investment (demand for capital), must be assumed to depend, not only on the rate of interest, but also on the level of income.
- 75See, however, Bresciani-Turroni, “The Theory of Saving” in Economica, May 1936, pages 172-174.
- 76See the above-mentioned article by Frisch.
- 77Compare Professor H. Neisser’s criticism in his article: “Notenbankfreiheit?” in Weltwirtschaftliches Archiv, Vol. 32, pages 446-461, and Vera Smith, The Rationale of Central Banking, London, 1936.
- 78See his book, Börsenkredit Industriekredit und Kapitalbildung, Vienna, 1931, pages 161-178.
- 79See his book, Börsenkredit Industriekredit und Kapitalbildung, Vienna, 1931, pages 161-178.
- 80The term “unused capacity” must be interpreted with great care. There is always some inferior capacity which can handle an increase of demand.
- 81This argument has been frequently expressed in recent years. See, for instance, J. M. Keynes, General Theory, page 174, and Economic Journal, 1937, pages 250-251; A. P. Lerner, “Mr. Keynes’ General Theory of Employment, Interest and Money” (International Labour Review, Vol. 34, October 1936, page 435; R. F. Harrod, Zeitschrift für Nationalökonomie 1937, page 494. R. F. Kahn, Economic Journal, Vol. 47, 1937, Page 671.
- 82Whilst there can be little doubt that we have here a possible source of inflation (whatever its quantitative importance), it is difficult to see in this factor any independent cyclical significance.
- 83Therefore, the statement made in the text is perfectly compatible with the free-trade argument. The qualifications made should be sufficient to exclude protectionist measures from the arsenal of a rational depression policy.
- 84See especially R. Nurkse: Internationale Kapitalbewegungen, Vienna, 1935. Ch. V, pages 187-211.
- 85See his criticism of Harrod’s rather unqualified utilisation of the acceleration principle in The Quarterly Journal of Economics, Vol. 51, May 1937, pages 509 et seq. (now reprinted in Full Recovery or Stagnation, New York, 1938).
- 86Cf. Durbin: The Problem of Credit Policy, 1935; Bresciani-Turroni, “The Theory of Saving” in Economica, May 1936, pages 175 and 176.
- 87Criticism by C. O. Hardy before the American Statistical Association, December 1931. Quoted by J. M. Clark in Journal of Political Economy, October 1932, page 693.
- 88Ibid., page 167. Precisely the same definition has been given by Professor Albert Hahn in his Volkswirtschaftliche Theorie des Bankkredits, Tübingen, 1920.
- 89Ibid., page 167.
- 90See “Vorbemerkungen zu einer Theorie der Ueberproduktion” in Jahrbuch für Gesetzgebung, Verwaltung und Volkswirtschaft, 1902. “Krisen” in Handwörterbuch der Staatswissenschaften, 1925.
- 91But how, it may be asked, does he describe this maladjustment from which there is no escape except through a more or less severe crisis? “It is the steep rise of the absolute amount of investments which matters, not the fact that our economic system must rely on credit expansion to make this rise possible.” And again: “The scale of investment grows, and so long as the rate at which it grows remains constant, or even increases, the boom has the power to last. Eventually, however, the moment must come when investment is not suddenly broken off certainly, but ceases to grow at the previous rate. We cannot always be building and ‘rationalising’ further, always constructing new electricity works, etc.—especially as the power of the credit system to go on continually financing this investment delirium is finally exhausted. At this point, the boom must come to an end, since the shrinkage of the capital goods industries is unavoidable.”
- 92Everybody means by “the rate of interest” the rate of interest on money loans—money loans of different duration, security, etc. By a money loan, we mean a loan which is expressed in terms of money. Interest and principal could be expressed in terms of other things than money. But even if they are expressed in money, the loan need not be paid out or repaid in money (cash). It may be given and repaid in kind and still be a money loan. Hence, what is needed is a numéraire and not actual money of exchange.
- 93See, e.g., The Downfall of the Gold Standard, Oxford, 1936. Like Mr. Hawtrey, he believes that “the economic development of post-war times has been so strikingly dominated by great monetary disturbances that trade cycles of the earlier kind are no longer applicable” (The Theory of Social Economy, Vol. II, page 538).
- 94These quotations do not make the situation envisaged by our author perfectly clear; but it is the nearest we can get to his meaning. In the second part of this book (see § 5 of Chapter II) it is proposed to work out a situation which perhaps covers what Professor RÖPKE really has in mind.
- 95Ibid., pages 140, 165, 184 and 185.
- 96G. Cassel: The Theory of Social Economy, revised ed., London, 1932, page 552.
- 97Ibid., page 195.
- 98Ibid., page 195.
- 99Compare footnote 1 on page 59 (Chapter 3, § 6). The locus classicus of the discussion of these problems is Professor Marget’s Theory of Prices, New York, 1938.
- 100See the penetrating critical analysis by Professor G. Halm (loc. cit., pages 30-34).
- 101Ibid., page 170.
- 102Ibid., page 197.
- 103Ibid., page 199. Mr. Keynes realises that this is not quite correct, because “the amount of cash which an individual decides to hold to satisfy the transactions- . . . and precautionary-motive is not entirely independent of what he is holding to satisfy the speculative motive”.
- 104Recent statistical studies have made it very doubtful whether such a lag actually exists. Compare, e.g., Professor J. Tinbergen in Statistical Testing of Business-Cycle Theories II. Business cycles in the United States, 1919-1937. In preparation.
- 105A very instructive mathematical and diagrammatic exposition of these relationships and of Mr. Keynes’ General Theory, in toto, has been given by Dr. Hicks: “Mr. Keynes and the Classics”, Econometrica, April 1937, and by O. Lange: “The Rate of Interest and the Optimum Propensity to Consume”, in Economica, February 1938, pages 12 et seq. Of the latter, Mr. Keynes says that it “follows very closely and accurately [his] line of thought”. (Economic Journal, Vol. 48, June 1938, page 321.)
- 106Mr. Keynes himself states his theory sometimes in terms of liquidity preference in the wider sense and sometimes in terms of liquidity preference proper. An example of the latter will be found in Economic Journal, 1937, page 250. “If we mean by ‘hoarding’ the holding of idle balances, then my theory of the rate of interest might be expressed by saying that the rate of interest serves to equate the demand and supply of hoards”.
- 107The Theory of Social Economy, Vol. II, page 649.
- 108See The Theory of Economic Development, Cambridge, Mass., 1934. (Translated from the German. The first German edition was published in 1911.) It must, however, be noted that Professor Schumpeter puts forward this theory, not as an explanation of the lower turning-point, but of the movement of the system away from equilibrium. He believes that it is possible to divide the upswing as well as the downswing in two sharply distinguishable phases: a movement towards equilibrium called revival and recession respectively, and a movement away from equilibrium, prosperity (or boom) and depression. Revival and prosperity constitute the upswing, recession and depression the downswing. The recuperative forces of adjustment inherent in the economic system are sufficient, so Professor Schumpeter believes, to lift output and employment from the subnormal level to which it has been reduced by the vicious spiral of deflation during the depression phase; no special incentives are needed to explain the lower turning-point. Professor Schumpeter’s “genial entrepreneur” and the crowd of imitators who follow him come in later during the upswing and prevent the system from settling down for any length of time at an equilibrium position.
- 109Ibid., page 667.
- 110Ibid., pages 663 et seq.
- 111Studien für Geschichte der Handelskrisen in England, Jena, 1901.
- 112See Chapter 6, § 2, page 148 below.
- 113Economic Journal, Vol. 47, 1937, page 666.
- 114Economic Journal, Vol. 48, 1938, page 319.
- 115Published by the University Institute of Economics, Oslo, 1938. See also article by the same author, “Reinvestment Cycles” in the Review of Economic Statistics, Vol. 20, February 1938.
- 116This point was also made by T. W. Hutchinson: The Significance and Basic Postulates of Economic Theory, London, 1938, pages 44 and 45.
- 117Compare the definition of this concept given above on page 210.
- 118Les crises périodiques de surproduction, Paris, 1913.
- 119See footnote 1 page 321, in Economic Journal, June 1938.
- 120Economica, February 1938.
- 121Hence we must conclude that Dr. Lange is not right when he attributes, rather unqualifiedly, to Mr. Keynes, not his general theory, but a special case of it—viz., that case where the “interest elasticity of the demand for liquidity is infinite” (page 19). It seems fair to say that Mr. Keynes holds that this situation obtains under special circumstances—viz., in deep depressions. It is “depression economics” (as Dr. Hicks, loc. cit., says) and not the “general theory” For further discussion of this special case, see the text below, page 218.
- 122A continuous replacement presupposes, of course, that the existing capital stock has been constructed in a continuous series of instalments. If that is not the case, replacement will be also discontinuous. “Replacement waves” may ensue, if the construction of the capital stock proceeds by fits and starts.
- 123Ibid.
- 124“The Inter-relation between Capital Production and Consumer Taking” in Journal of Political Economy, Vol. 39, October 1931, page 646. See also the subsequent discussion between Frisch and J. M. Clark in Vols. 39 and 40 of Journal of Political Economy. Pigou has already made sufficient allowance for this quantitative qualification in his formulation of the acceleration principle in his Industrial Fluctuations, Ch. IX.
- 125The same difficulties have to be faced by any two-dimensional analytical apparatus when applied to such a complex phenomenon as the demand for idle balances and the rate of interest. Compare on this point M. Millikan, loc. ext., pages 254 et seq.
- 126This point has been well put by Professor J. Tinbergen. In the article mentioned on page 87, he says:
- 127Hicks, op, cit., page 154.
- 128Compare e.g., § 4 of this chapter, page 45 above.
- 129General Theory, page 203.
- 130When put in terms of asset prices, it becomes clear that it is an optical illusion to say that the rate of interest cannot fall farther because it is “so near to zero” Between, say, one per cent and zero per cent, there are still as many intermediate positions as there are between the price at $400 of a $100 4% bond (corresponding to a capitalisation at an interest rate of 1%) and the infinitely high, price of the same bond corresponding to a capitalisation at a rate of zero per cent.
- 131Capital and Employment, 1937, Chapter VII. See also Mr. Kaldor’s reply to Mr. Hawtrey’s criticism of Mr. Keynes, “Mr. Hawtrey on Short and Long Term Investment in Economica, November 1938, pages 464 and 465.
- 132This has also been well put by Professor D. H. Robertson. “. . . Some of the principal forms of investment in the modern world—the instruments of power-production, of transport, of office activity—are, after all, very loosely geared to the visible demand for particular types of consumption goods and depend rather on fairly vague estimates of the future progress of whole areas and populations. (See his review of Harrod’s The Trade Cycle in The Canadian Journal of Economics and Political Science, Vol. III, 1937, page 126.)
- 133It should be understood that, according to Mr. Keynes’ theory, the two policies are alternative means only in one respect, which is, however (in the present context), the important one. Both policies serve to increase the quantity of money in terms of real purchasing power, “in terms of wage units” as Mr. Keynes says. On page 234 of his General Theory, Mr. Keynes says, for example: “The only relief [for an excessive liquidity preference—that is, for an extreme desire to hoard]—apart from changes in the marginal efficiency of capital—can come . . . from an increase in the quantity of money, or—which is formally the same thing—a rise in the value of money.” (Note that this passage contains an explicit statement to the effect that a fall in wages and prices will eventually bring relief. We wish, however, by no means to deny, nor does Mr. Keynes, that in many other respects the two policies are very different and cannot be regarded, from a practical point of view, as good substitutes. Cf. § 5 of this chapter below.)
- 134Chronic unemployment with stable money wages is no proof of an absolute liquidity preference.
- 135It follows that the expansionary effect of. a shift in the demand is more likely to be great if it occurs during a period when the demand for equipment in both industries is at a relatively low level. If it takes place while a general expansion is in progress, the acceleration principle has free play to operate in both directions and the effects on industry A and B are therefore more likely to compensate each other.
- 136Ibid., page 184. In the course of the discussion, Mr. Keynes is sometimes inclined to forget these limitations of his theory. This has misled some economists to overlook them altogether. The usefulness of the system ci early depends on the degree of independence of these variables. If they were highly interdependent, they could not be regarded as “ultimate independent variables”. This, is, of course, a difficulty which any interdependence theory, especially one in macro-economic terms, has to face. It is impossible to build up a theory which explains national income and employment in terms of a few complex, strictly independent factors without having regard to their internal structure. Such a procedure can yield only rough approximations. Mr. Keynes is well aware of these difficulties. See, for example, his remarks, General Theory, page 297.
- 137A somewhat different standpoint in this matter is taken up by Professor RÖPKE, who has recently laid great stress on the acceleration principle as affording an explanation of why a serious breakdown is unavoidable after a period of rapid expansion. His analysis of the rôle of the acceleration principle in the mechanism of expansion is the same as that which is given above. He does not, however, explain the ensuing breakdown by the emergence of capital shortage or of an insufficiency of consumers’ demand: nor does he believe that the breakdown can be avoided by more saving (as the capital shortage theorists do) or by more spending (as the under-consumption theorists do). He believes that, owing to the operation of the acceleration principle, a situation in the structure of production is bound to develop which can under no circumstances be maintained—either by less saving on the part of the public or by more—so that a serious breakdown is inescapable. According to him, this type of maladjustment is unavoidable after a period of rapid capital accumulation, even in a planned socialist economy of the Russian type.
- 138But how, it may be asked, does he describe this maladjustment from which there is no escape except through a more or less severe crisis? “It is the steep rise of the absolute amount of investments which matters, not the fact that our economic system must rely on credit expansion to make this rise possible.” And again: “The scale of investment grows, and so long as the rate at which it grows remains constant, or even increases, the boom has the power to last. Eventually, however, the moment must come when investment is not suddenly broken off certainly, but ceases to grow at the previous rate. We cannot always be building and ‘rationalising’ further, always constructing new electricity works, etc.—especially as the power of the credit system to go on continually financing this investment delirium is finally exhausted. At this point, the boom must come to an end, since the shrinkage of the capital goods industries is unavoidable.”
- 139It will be observed that what is meant is not the time rate of consumption (saving), the amount consumed (saved) per unit of time, but the income rate, amount consumed (saved) per unit of income. This rate of consumption is measured by the rate of saving by Since S = Y − C, the rate of saving is i minus the rate of consumption:
- 140Mr. Keynes calls it the “logical theory of the multiplier” (General Theory, page 122).
- 141The idea that investment stimulates consumption is almost as old as business-cycle theory. That it is inherent in the Wicksellian theory of the cumulative process of expansion has already been said (see Chapter 3, pages 33 et seq., above). Mr. Kahn, among others, has analysed the problem in his article “The Relation of Home Investment to Unemployment” (Economic Journal, June 1931), and has contributed the word “multiplier”.
- 142See, for example, A. D. Gayer, Public Works in Prosperity and Depression (New York, 1929), and J. M. Clark, Economics of Planning Public Works (Washington, 1935).
- 143This latter relationship is described by the acceleration principle.
- 144General Theory, pages 96 and 114.
- 145Cf. Elizabeth W. Gilboy, “The Propensity to Consume” in Quarterly Journal of Economics, Vol. 53, November 1938, and Mr. Keynes’ reply, ibid., May 1939.
- 146“Short Period Variations in the Distribution of Incomes Review of Economic Statistics, Vol. 19, 1937 (pages 133 to 143) and the comments by F. C. Dirks, Review of Economic Statistics, Vol. 20, and rejoinder by Dr. Staehle, ibid.
- 147Compare, for instance, this case with another one where the same road is built with less labour and at a much lower cost, and the superfluous workers receive a dole. Part of the total money spent ‘is investment and the other part consumption, whilst, in the case mentioned in the text, all is counted as investment.
- 148These problems are discussed at great length in various contributions to Studies in Income and Wealth, Vol. I and II (ed. by National Bureau of Economic Research, New York, 1937 and 1938).
- 149General Theory, page 123.
- 150Ibid., page 122.
- 151This is also the opinion of Mr. E. Lundberg (cf. Studies in the Theory of Economic Expansion, London, 1937, Page 36), who believes that the multiplier will exhibit a cyclical movement over time.
- 152General Theory, page 297
- 153Ibid., pages 313 et seq.
- 154Compare, for example, General Theory, pages 31, 98 and 105.
- 155See General Theory, pages 41 and 247. That the wage-unit—that is, “the money-wage of a labour unit”—must be given, is a highly important fact which is frequently overlooked and will come up for discussion below (page 238). It implies that an equilibrium with less than full employment can exist only if money wages are rigid.
- 156For further details and hypotheses, see Chapter 11, section B, below.
- 157For further details and other hypotheses, see Chapter 11. section A, below.
- 158General Theory, page 16.
- 159General Theory, page 15. Italics in the original. An extensive discussion of this definition will be found in J. Robinson, Essays in the Theory of Employment, London, 1937, Part I. See also Viner’s criticism, Quarterly Journal of Economics, Vol. 51, 1936, pages 147 et seq.
- 160Compare the following statement by Mr. J. E. Meade, “A Simplified Model of Mr. Keynes’ System” (Review of Economic Studies, Vol. IV, page 99): “If we suppose that the money-wage rate would fall so long as any labour were unemployed, the system cannot be in equilibrium without full employment.” Professor Alfred Amonn also points out that only with monopolistic wage rigidities can there be equilibrium with less than full employment. “Grundfragen der Konjunkturtheorie und Konjunkturpolitik” in Festschrift für Oskar Engländer, Brünn, 1937 passim.
- 161General Theory, page 17. Professor Viner considers this an unwarranted concession to the classical doctrine, as it is quite possible that real wages may rise with increasing employment. Cf. Quarterly Journal of Economics, Vol. 51, 1936, pages 149 and 150. This has been shown statistically by J. T. Dunlop: “The Movement of Real and Money Wage Rates”, Economic Journal, Vol. 48, 1938, pages 413 et seq. Mr. Dunlop’s article has induced Mr. Keynes to modify his position somewhat. See his paper: “Relative Movements of Real Wages and Output”, Economic Journal, March 1939.
- 162General Theory, page 11.
- 163Loc. cit., page 13. Mr. Keynes adds: “This will be our contention.”
- 164Loc. cit., page 12.
- 165Beiträge zur Geldtheorie, ed. by Hayek.
- 166See, for example, Mr. A. P. Lerner: “Mr. Keynes’ ‘General Theory of Employment, Interest and Money’”, International Labour Review, Vol. 34, 1936. Mr. Lerner there “proves” that prices must fall “in just the same proportion as wages” (pages 441 and 442). It is true that he qualifies that statement by admitting “that a reduction of money-wages may have all sorts of indirect influences”. But this qualification is again qualified, and the short paragraph devoted to the matter gives a very cursory summary of Mr. Keynes’ analysis.
- 167See Chapter 11, § 9, below.
- 168General Theory, page 262.
- 169General Theory, page 257 and passim.
- 170General Theory, page 253 (italics not in the original). For this reason, it is clear that the alleged intractability of slump conditions (discussed in Chapter 17 of the Theory, especially on pages 229 to 235) can refer only to conditions in which money-wages are not allowed to fall indefinitely. It is therefore as true to attribute the persistence of unemployment to the rigidity of wages and prices as to attribute it to the peculiarity of money as compared with other assets. This does not, of course, exclude the view that unemployment may be relieved—perhaps more effectively—by measures other than a reduction in wages—e.g., by an increase in the quantity of money combined with Government spending.
- 171General Theory, page 269.
- 172It is always possible to conserve the favourable effects of a policy of wage reductions in its cost aspect, and at the same time to eliminate the unfavourable ones, by combining the policy of wage reductions with a policy of public works (or similar measures), so as to make sure that total purchasing power does not fall.
- 173General Theory, page 219. See also however the passage on page 203 already quoted.
- 174The most balanced and best considered statement is to be found in Professor Hansen’s Full Recovery or Stagnation, New York, 1938, passim, and in his paper, “Economic Progress and Declining Population Growth”, American Economic Review, March 1939. A very good but rather unqualified statement is to be found in An Economic Program for American Democracy by Paul M. Sweezy, R. V. Gilbert and others, New York, 1938. Compare also Gerhard Colm and Fritz Lehman, Economic Consequences of Recent American Tax Policy, Supplement I to Social Research, New York, 1938; and G. Haberler, “Interest Rate and Capital Formation”, in Capital Formation and its Elements, ed. by the National Industrial Conference Board, New York, 1939.
- 175“Final” in a relative sense.
- 176Professor Frisch (“Propagation and Impulse Problems”, in Economic Essays in Honour of Gustav Cassel, London, 1933, Page 172) uses the term “macro-analysis” in the sense of “general” (embracing the economic process as a whole) and “micro-analysis” in the sense of “partial equilibrium analysis”. He points out that a general interdependence theory can be given in all detail (in our terminology: in microscopic terms) only “if we confine ourselves to a purely formal theory. Indeed, it is always possible by a suitable system of subscripts and superscripts, etc., to introduce practically all factors which we may imagine (all individual commodities, all individual entrepreneurs, all individual consumers, etc.), and to write out various kinds of relationship between these magnitudes, taking care that the number of equations is equal to the number of variables. Such a theory, however, would have only a rather limited interest. In such a theory it would hardly be possible to study such fundamental problems as the exact time, shape of the solutions, etc.” (page 172).
- 177Cf., for example, Frisch, loc. cit., and J. Tinbergen, “Suggestions on Quantitative Business-cycle Theory”, Econometrica, Vol. 3, 1935, page 241.
- 178Usually, the assumption is made that, after a change in the data has occurred, a certain period of time must elapse before a new equilibrium emerges. Comparative statics in the strict sense confines itself to describing the two equilibria, the starting-point and the destination of the economic system. Any attempt, on the other hand, at analysing in detail the process of transition from one equilibrium to the other (e.g., in Marshallian manner, by distinguishing between short- and long-period effects) marks the first step towards a “dynamisation” of static theory. For it leads inevitably to the recognition of the fact that, as the result of certain reactions, the process of transition, and hence the final equilibrium, may be different. It also suggests that, after a given change in the data, a stable position will be reached only under special assumptions (stability conditions), which cannot be taken for granted without careful analysis.
- 179Frisch, loc. cit., page 171. Tinbergen formulates: “A theory [is called] ‘dynamic’ when variables relating to different moments appear in one equation” (loc. cit., page 241).
- 180Professor Tinbergen, loc. cit., has enumerated many different dynamic relationships which have been used at one time or another in business-cycle theory.
- 181This was the definition of an endogenous theory. Cf. Chapter i, page 9.
- 182Economica, February 1938. Mr. Keynes has accepted this exposition as correct. See also J. E. Meade: “A Simplified Model of Mr. Keynes’ System”, in the Review of Economic Studies, Vol. IV, 1936/37, page 98.
- 183The Trade Cycle, Oxford, 1936.
- 184“A Theory of the Business Cycle”, in Review of Economic Studies, Vol. IV, February 1937, pages 77 et seq., reprinted in Essays in the Theory of Economic Fluctuations, London, 1939.
- 185“Business Acceleration and the Law of Demand” in Journal of Political Economy, March 1917. Economics of Overhead Costs, Chicago, U.S.A., 1923. Controversy with Ragnar Frisch in Journal of Political Economy, October and December 1931, April 1932. Strategic Factors in Business Cycles, New York, 1934, pages 33 et seq.
- 186General Theory, pages 24, 25, 46 et seq., 141, 147 et seq. Compare also what has been said earlier in this book in Chapter 6, § 2, on the rôle of expectations.
- 187Expectations may almost be called “non-operational concepts”. The only way of finding out something about them would be to question individual business-men—a very questionable procedure.
- 188From a strictly logical point of view, the psychological link between the past and the present consisting of expectations may be dropped and the theory stated in terms of a direct relationship between observable phenomena at different points of time. Psychologically it may, however, be useful to retain the word “expectations”, or a similar concept, as a link, because it reminds us of the fact that those dynamic “laws” (relationships) are nothing but hypotheses; that they can hardly ever be stated very precisely in great detail; and that they may always be subject to rapid change “without notice”.
- 189London, 1937, especially Chapter IX.
- 190Compare the following remarks from his book: “The introduction of causal elements linking up economic factors in successive periods of time means a more radical departure from equilibrium-theories than the dynamisation claimed by Myrdal, and later by Keynes, when paying attention to the independent rôle of expectations and anticipations. . . . The introduction of expectations can, in a way, be said to mark the stepping-stone to dynamic analysis, because they express the connection linking present plans and activities with future events. However, economists have indulged in too much purely formal exercise with this term. . . . It is sensible to link actions with expectations, only if the latter can be explained on the basis of past and present economic events. Total lack of correlation here would mean the complete liquidation of economics as a science. . . . In every process of economic reasoning, we. . . . have to make certain assumptions, often not specified, concerning the relation between expectations, on the one hand, and current or past prices, profits, etc., on the other” (loc. cit., page 175).
- 191Dr. Lundberg is, of course, well aware of these limitations.
- 192See, for example, An Economic Approach to Business-cycle Problems and the companion volume, Lesx Fondements Mathématiques de la Stabilisation du Mouvement des Affaires, Paris, 1937 and 1938. For a detailed discussion of the statistical methods and measurements involved, compare Professor Tinbergen’s memoranda published by the Economic Intelligence Service of the League of Nations, Geneva, 1939, in the series: Statistical Testing of Business-Cycle Theories.
- 193Hence this branch of economics has been cultivated by mathematical economists. See especially the work of Frisch and Tinbergen.
- 194The real distinction—in some cases—is between controllable and uncontrollable factors. The weather, e.g., is uncontrollable, while institutional factors are at least in theory controllable. Among factors, furthermore, which can in principle be controlled, there are those which one does not find it desirable, for one reason or another, to control or to eliminate altogether—e.g., inventions, or the liberty of the recipient of income to spend his income or to save it, or to exercise freedom of choice in regard to his consumption or occupation. Needless to say, opinion as to what it is possible and desirable to control or influence varies from time to time and from person to person.
- 195It has been attempted to give more precision to the distinction between exogenous and endogenous theories by saying that the former assume movements in the data, while the latter suppose the data to remain constant. This distinction is precise enough once the general theoretical system on which a writer builds his theory of the business cycle has been determined and accepted; but it is not possible to lay down beforehand once and for all what phenomena are to be regarded as accepted data and what are magnitudes to be explained and determined in the light of those data. What the theory of yesterday accepted as data, we try to explain to-day; and the independent variables (data) on which we build to-day may become dependent variables to-morrow. All attempts to make a definite distinction between data and results lead back to the earlier conception which regards forces or movements of a “non-economic” nature or “external” to the economic system as the “data” of economic theory. But this distinction between “economic” and “non-economic” phenomena is a purely conventional one. There is no reason why forces or movements not to be classified as economic should not become “dependent” or “explained” variables of a general—as distinct from an economic—theory.
- 196With very few exceptions, all serious explanations are neither purely exogenous nor purely endogenous. In almost all theories, both the “originating factors” and the “responses of the business system” (to use the expression of J. M. CLARK) play a rôle. On the one hand, a purely exogenous theory is impossible. Even if one assumes a weather cycle, the peculiar response of the business system, which converts harvest variations into a general alternation of prosperity and depression, has still to be explained. On the other hand, a purely endogenous theory is hardly satisfactory. It is not likely that, without outside shocks, a cyclical movement would go on for ever: and, even if it did go on, its course would certainly be profoundly influenced by outside shocks—that is, by changes in the data (however these may be defined and delimited by economically explained variables).
- 197One methodological rule of thumb may be suggested at this point, however, although it will find its full justification only later. For various reasons, it seems desirable, in the explanation of the business cycle, to attach as little importance as possible to the influence of external disturbances. In the first place, large swings in the direction of prosperity and depression as we find them in real life are difficult to explain solely by exogenous forces; and this difficulty becomes an impossibility when the alleged “disturbances” do not themselves show a wavelike movement. Even if a periodic character is assumed (e.g., in the case of crops or inventions), the hypothesis is full of difficulty. The responses of the business system seem prima facie more important in shaping the business cycle than external shocks. Secondly, historical experience seems to demonstrate that the cyclical movement has a strong tendency to persist, even where there are no outstanding extraneous influences at work which can plausibly be held responsible. This suggests that there is an inherent instability in our economic system, a tendency to move in one direction or the other. If it is possible (as we believe) to demonstrate that such a tendency exists and to indicate the conditions under which it works, it will be comparatively easy to fit all kinds of external perturbations, including all State interventions, into the scheme. Exogenous forces will then figure as the originators or disturbers of endogenous processes, with power to accelerate, retard, interrupt or reverse the endogenous movement of the economic system.
- 198The scope of the following analysis of theories has been defined in the Introduction (page I). The method followed in the exposition is thereby largely determined. No attempt has been made to present the various theories in chronological order or to picture the theoretical and sociological background of the various writers (except in so far as it may have been necessary in order to elucidate their doctrines). It has been preferred to present the theories in a systematic order, beginning (so far as possible) with the less complicated and proceeding thereafter to the more complicated. Frequently it happens that the latter cover all the factors on which the former lay stress, while drawing attention to others which the former have overlooked or treated as irrelevant or put aside by means of a convenient simplifying assumption (e.g., by a ceteris paribus clause).
- 199One methodological rule of thumb may be suggested at this point, however, although it will find its full justification only later. For various reasons, it seems desirable, in the explanation of the business cycle, to attach as little importance as possible to the influence of external disturbances. In the first place, large swings in the direction of prosperity and depression as we find them in real life are difficult to explain solely by exogenous forces; and this difficulty becomes an impossibility when the alleged “disturbances” do not themselves show a wavelike movement. Even if a periodic character is assumed (e.g., in the case of crops or inventions), the hypothesis is full of difficulty. The responses of the business system seem prima facie more important in shaping the business cycle than external shocks. Secondly, historical experience seems to demonstrate that the cyclical movement has a strong tendency to persist, even where there are no outstanding extraneous influences at work which can plausibly be held responsible. This suggests that there is an inherent instability in our economic system, a tendency to move in one direction or the other. If it is possible (as we believe) to demonstrate that such a tendency exists and to indicate the conditions under which it works, it will be comparatively easy to fit all kinds of external perturbations, including all State interventions, into the scheme. Exogenous forces will then figure as the originators or disturbers of endogenous processes, with power to accelerate, retard, interrupt or reverse the endogenous movement of the economic system.
- 200In more recent publications, under the impression of the slump of the nineteen-thirties, Mr. HAWTREY has modified his views to some extent. He now doubts whether it can be legitimately assumed that “the expectation of falling prices is (always) the result of a preceding experience of a prolonged actual fall” and that such a condition of stagnation is not possible except in the course of a reaction from a riot of inflation.
- 201“If the restriction of credit did not occur, the active phase of the trade cycle could be indefinitely prolonged, at the cost, no doubt, of an indefinite rise of prices and an abandonment of the gold standard.”
- 202The process of contraction is cumulative no less than the process of expansion. “When credit has definitely turned the corner, and a contraction has succeeded to an expansion, the downward tendency of prices is sufficient to maintain the process of contraction, even though the rate of interest is no longer, according to the ordinary standards, high.”
- 203“Thus there is a principle of the instability of velocity of circulation, which is quite distinct from the principle of the instability of credit, but is very apt to aggravate its effect.”
- 204In his earlier writings Mr. HAWTREY had already mentioned the theoretical possibility of a complete credit deadlock arising. That is a situation where even exceedingly low interest rates fail to evoke a new demand for credit. In such a situation, the ordinary means of bank policy prove wholly ineffective. In his Good and Bad Trade he ascribes this phenomenon to the fact that “the rate of depreciation of prices” may be so rapid that “nothing that the bankers can do will make borrowing sufficiently attractive” to lead to a revival in the flow of money.
- 205In more recent publications, under the impression of the slump of the nineteen-thirties, Mr. HAWTREY has modified his views to some extent. He now doubts whether it can be legitimately assumed that “the expectation of falling prices is (always) the result of a preceding experience of a prolonged actual fall” and that such a condition of stagnation is not possible except in the course of a reaction from a riot of inflation.
- 206But even so, Mr. HAWTREY thinks, the recurrence of the breakdown is not inevitable. The expansion could go on indefinitely, if there were no limits to the increase in the quantity of money. The gold standard is, in the last resort, responsible for the recurrence of economic breakdowns. Under the gold standard, it is the slow response of people’s cash balances which prevents the banks from stopping expansion or contraction in time. “If an increase or decrease of credit money promptly brought with it a proportionate increase or decrease in the demand for cash, the banks would no longer either drift into a state of inflation or be led to carry the corresponding process of contraction unnecessarily far.” Given, however, this slow response of the people’s cash balances, “so long as credit is regulated with reference to reserve proportions, the trade cycle is bound to recur”.
- 207Under the automatic working of the gold standard, “the length of the cycle was determined by the rate of progress of the processes on which the cycle depended, the absorption of currency during the period of expansion and its return during the period of contraction”.
- 208A feature of particular interest in Mr. HAWTREY’S monetary theory of the business cycle is the demonstration and analysis of the cumulative nature of the process of expansion and contraction. In this respect, there is, as we shall see, much agreement between theorists of different schools of thought. Mr. HAWTREY’S propositions on this point, largely taken over from MARSHALL and the Cambridge tradition, have found a place in the theory of a great number of writers.
- 209To complete the picture of Mr. HAWTREY’S theory, a word must be said as to the policy banks should pursue in order to eliminate the credit cycle, and with it the trade cycle. The banks, and especially the leaders of the banking system, the central banks, should not watch the reserve proportions so much as the flow of purchasing power. The demand for goods, the flow of money, is the important thing—not the outstanding aggregate of money units. The aim of banking policy should be to keep the consumer’s outlay constant, including (as has been pointed out) outlay for new investment. But account should be taken of changes in the factors of production—not merely the growth of population, but also the growth of capital—and allowance ought to be made for the proportion of skilled labour of varying grades and for the appropriate amount of economic rent. In other words, the aim should be to stabilise, not the price level of commodities, but the price level of the factors of production.
- 210With the purely monetary explanation of the business cycle, it is comparatively easy to account for various kinds of international complications. The analysis of any given international constellation involving two or more countries must invariably turn on the question of how the money supply in each of these countries is likely to be affected. This analysis has not yet been worked out systematically from the standpoint of the explanation of the business cycle. But the instruments of the analysis are ready to hand. The theory of the international money mechanism under different monetary standards is one of the most fully elaborated chapters of economic science.
- 211If the rate of interest falls because of increased savings, the demand for capital can be satisfied to a greater extent and the equilibrium point moves down along the curve of demand for capital. Investments which were extra-marginal under the higher rate now become permissible. Factors of production are shifted from the lower to the higher stages of production. The production process is lengthened and eventually the output of consumers’ goods per unit of input (in terms of “original factors” of production) is raised.
- 212It sounds perhaps paradoxical that a general increase in demand for consumers’ goods should have an adverse influence on the production of capital goods in general, which derive their economic value from the consumers’ goods which they help to produce. The paradox has puzzled many writers, but it is not difficult to explain. It should be borne in mind in the first place that the proposition holds good only if all factors of production are reasonably well employed or if at least some of the factors attracted to consumers’ goods trades would otherwise have been employed elsewhere. In other words, under full employment, the production of consumers’ good or that of producers’ goods are alternatives. At the end of the boom, the condition of reasonably full employment can as a rule be assumed to be true. Secondly, it is assumed that the demand for consumers’ goods rises relatively to the demand for producers’ goods. This second assumption excludes the possibility of a compensatory expansion of credit, since, if credit for the purpose of acquiring producers’ goods could be expanded pari passu with the increased demand for consumers’ goods, it would no longer be true that the proportion between demand for consumers’ goods and producers’ goods has changed. The change involves a rise in interest rates; for prosperity in consumers’ goods industries holds out good prospects of profits in the higher stages of production. Producers in the higher stages of production will be eager to continue lengthening the productive structure and will try to raise the necessary funds by borrowing from the banks. Demand for credit rises; but supply is unchanged, or not sufficiently changed—for it is assumed that credit ceases to expand, or does not expand sufficiently. This entails a rise in interest rates; and such a rise, as Professor HAYEK has shown, falls more heavily on production costs in the higher than in the lower stages of production. The situation is now, therefore, that money cost has risen, but demand has not risen (or not sufficiently risen), because the necessary funds are no longer forthcoming.
- 213In his Prices and Production, Professor HAYEK argues that, even where the extension of the structure of production which entrepreneurs were induced to undertake by the artificial cheapening of credit is completed, the old arrangement tends to be restored later on for the reason that consumers will “attempt to expand consumption to the usual proportion” and “the money stream will be re-distributed between consumptive and productive uses” in the same, or nearly the same, proportion as it was distributed before such proportion was artificially distorted from the normal by the injection of money.
- 214This comes about in the following way. Entrepreneurs who want to invest are provided with purchasing power by the banks and compete for capital goods and labour. Prices will rise or be prevented from falling—this last case we shall discuss in detail later—and consumers’ goods industries (the demand for the pro-duct of which has not risen, or not risen so much as the demand for capital goods, which is swollen by the newly created purchasing power) will be unable to retain at the enhanced prices all the factors of production which they used to employ. They will be compelled, therefore, to release means of production for use in the higher stages of production—that is, for the production of additional capital goods.
- 215It sounds perhaps paradoxical that a general increase in demand for consumers’ goods should have an adverse influence on the production of capital goods in general, which derive their economic value from the consumers’ goods which they help to produce. The paradox has puzzled many writers, but it is not difficult to explain. It should be borne in mind in the first place that the proposition holds good only if all factors of production are reasonably well employed or if at least some of the factors attracted to consumers’ goods trades would otherwise have been employed elsewhere. In other words, under full employment, the production of consumers’ good or that of producers’ goods are alternatives. At the end of the boom, the condition of reasonably full employment can as a rule be assumed to be true. Secondly, it is assumed that the demand for consumers’ goods rises relatively to the demand for producers’ goods. This second assumption excludes the possibility of a compensatory expansion of credit, since, if credit for the purpose of acquiring producers’ goods could be expanded pari passu with the increased demand for consumers’ goods, it would no longer be true that the proportion between demand for consumers’ goods and producers’ goods has changed. The change involves a rise in interest rates; for prosperity in consumers’ goods industries holds out good prospects of profits in the higher stages of production. Producers in the higher stages of production will be eager to continue lengthening the productive structure and will try to raise the necessary funds by borrowing from the banks. Demand for credit rises; but supply is unchanged, or not sufficiently changed—for it is assumed that credit ceases to expand, or does not expand sufficiently. This entails a rise in interest rates; and such a rise, as Professor HAYEK has shown, falls more heavily on production costs in the higher than in the lower stages of production. The situation is now, therefore, that money cost has risen, but demand has not risen (or not sufficiently risen), because the necessary funds are no longer forthcoming.
- 216Against this objection, the following argument has been advanced. It is true, in an economy where the output, owing to improvements in the methods of production, grows at a constant rate, that a steady expansion in terms of money may be made: that is to say, per unit of time a constant amount of new money may be put into circulation. But even if this is just enough to keep the price level of finished goods constant, prices of factors of production will rise continuously. Hence, successive additions to the money stock will only be able to buy successively diminishing amounts of the factors of production. But, to render the completion of the newly initiated processes of production possible, the entrepreneurs in the upper stages must be enabled to absorb factors of production àt a constant rate; and, as the prices of factors of production rise, a credit expansion at an increasing rate will be necessary to enable them to do so. The conclusion is that a relative inflation, such as can be made within the limits of a constant price level, is not sufficient to allow of the completion of the new roundabout methods of production which have been initiated under the stimulus of the expansion. Either the rate of expansion of credit will be sufficiently increased and prices will be driven up and the inevitable breakdown will be postponed, or the boom will collapse at once owing to an insufficiency in the capital supply.
- 217Treatment of these theories is complicated by the fact that there is as yet no agreement as to the exact use of the expression “forced saving”. It has been used to indicate the extra saving created by the transfer of resources and incomes from creditor to debtor, from rentier to State, from wage-earner (at least temporarily) to employer, as the result of inflation. Professor STRIGL has objected to this theory of forced saving that, if those with relatively fixed incomes get less and are obliged to restrict consumption, others expand their incomes to a corresponding amount and, unless they refrain voluntarily from expanding consumption to the required extent, there cannot be a net increase in capital formation. In other words, there is no forced saving, but only ordinary, voluntary saving.
- 218Apart, however, from the increase of saving as a result of what Professor PIGOU styles a “doctoring of past contracts”, there is a more direct channel whereby additional bank credits may increase investment. This is the process which Professor ROBERTSON discusses at length in Banking Policy and the Price Level under the head of “Automatic Stinting”. Either dishoarding or the expenditure of newly created money, he says, “brings on to the market an additional daily stream of money which competes with the main daily stream of money for the daily stream of marketable goods, secures a part of the latter for those from whom the additional stream of money flows, and thus deprives the residue of the public of consumption which they would otherwise have enjoyed”. As PIGOU argues in the particular case of the expansion of bank credits: “What in substance has happened is that the bankers have transferred to business-men purchasing power and, through purchasing power, real stuff in the form of wage goods and so on, formerly belonging to other people. They have done this by giving new money titles to business-men while leaving the money titles in other people’s hands untouched in exactly the same way as they would have done had they taken money titles from other people and handed them to business-men.”
- 219In his Prices and Production, Professor HAYEK argues that, even where the extension of the structure of production which entrepreneurs were induced to undertake by the artificial cheapening of credit is completed, the old arrangement tends to be restored later on for the reason that consumers will “attempt to expand consumption to the usual proportion” and “the money stream will be re-distributed between consumptive and productive uses” in the same, or nearly the same, proportion as it was distributed before such proportion was artificially distorted from the normal by the injection of money.
- 220The most prominent writers in this group are Professors A. SPIETHOFF and G. CASSEL. In the writings of these two authors (of SPIETHOFF especially), we find the culmination of a very important line of thought which can be traced back to MARX. Spiethoff’s immediate forerunner was the well-known Russian author TUGAN-BARANOWSKI. Both SPIETHOFF and CASSEL have had a great influence on business cycle theory, particularly in Germany, but also in the Scandinavian and Anglo-Saxon countries. WICKSELL himself adopted SPIETHOFF’S explanation of the cycle.
- 221In more recent publications, under the impression of the slump of the nineteen-thirties, Mr. HAWTREY has modified his views to some extent. He now doubts whether it can be legitimately assumed that “the expectation of falling prices is (always) the result of a preceding experience of a prolonged actual fall” and that such a condition of stagnation is not possible except in the course of a reaction from a riot of inflation.
- 222He still believes that “a failure of cheap money to stimulate revival” is “a rare occurrence” but he admits that “since 1930, it has come to plague the world and has confronted us with problems which have threatened the fabric of civilisation with destruction”.
- 223The theories of the following writers will now be examined: F. A. HAYEK, F. MACHLUP, L. MISES, L. ROBBINS, W. RÖPKE and R. STRIGL. The explanation given by these writers of the upswing and of the down-turn (crisis) is fundamentally the same. Such differences as exist are mainly in respect of amplifications in the later publications. Serious conflicts of opinion are to be found, on the other hand, in respect of the description and explanation of the downswing and the up-turn (revival). Professor RÖPKE, in particular, dissents strongly from the opinion of the other writers named in the interpretation of the later phases of such prolonged depressions as that of 1929-1936. The writers of this group have this in common with the purely monetary theory of Mr. HAWTREY, that they assume an elastic money supply. They argue that the circulating medium consists under modern conditions primarily of bank money (deposits), and that the banking system regulates the quantity of money by changing the discount rate and by conducting open-market operations. It has long been recognised that there is a complicated functional relationship between the interest rate, changes in the quantity of money and the price level. These relationships have been expounded systematically by KNUT WICKSELL; his theory, outlined below, is the basis of the explanation of the business cycle which follows. It should be added that, in what follows, we shall leave international complications for the moment out of account and disregard the fact that a change in the interest rate in one country will influence the flow of credit from and to other countries. These complications can easily be introduced into the picture later. For the present, we presuppose a closed economy.
- 224The following authors have developed the acceleration principle—Albert AFTALION, BICKERDIKE, Mentor BOUNIATIAN, T. N. CARVER, and MARCO FANNO. In recent years, it has been expounded most fully by J. M. CLARK, SIMON KUZNETS, A. C. PIGOU and R. F. HARROD. W. C. MITCHELL, D. H. ROBERTSON, and A. SPIETHOFF have incorporated it into their account of the cycle as a contributory factor. Mr. HARROD has, without much reference to the previous literature, rechristened the principle as “the Relation”.
- 225Professor Francesco VITO uses the expression “forced savings” for what is usually called “corporate saving”. If a business firm or company fails to distribute its entire profits to the shareholders, this may mean that the latter have been “forced” to save (against their will) by the directors of the corporation. Professor VITO believes that this type of forced saving is likely to cause the same troubles as the type envisaged by Professor HAYEK.
- 226Against this objection, the following argument has been advanced. It is true, in an economy where the output, owing to improvements in the methods of production, grows at a constant rate, that a steady expansion in terms of money may be made: that is to say, per unit of time a constant amount of new money may be put into circulation. But even if this is just enough to keep the price level of finished goods constant, prices of factors of production will rise continuously. Hence, successive additions to the money stock will only be able to buy successively diminishing amounts of the factors of production. But, to render the completion of the newly initiated processes of production possible, the entrepreneurs in the upper stages must be enabled to absorb factors of production àt a constant rate; and, as the prices of factors of production rise, a credit expansion at an increasing rate will be necessary to enable them to do so. The conclusion is that a relative inflation, such as can be made within the limits of a constant price level, is not sufficient to allow of the completion of the new roundabout methods of production which have been initiated under the stimulus of the expansion. Either the rate of expansion of credit will be sufficiently increased and prices will be driven up and the inevitable breakdown will be postponed, or the boom will collapse at once owing to an insufficiency in the capital supply.
- 227But suppose it had become impossible to carry through this ambitious plan. Suppose the Government had come to the conclusion half-way that the population could not stand the enormous strain and had decided to change the policy. In such a case, they would have been forced to give up the newly started roundabout methods of production and produce consumers’ goods as quickly as possible. They would have had to interrupt the construction of power-plants, steel works and tractor factories and try instead to produce as quickly as possible simple implements and tools to increase the output of food and shoes and houses. That would have involved an enormous loss of capital, sunk in the abandoned construction works.
- 228To sum up, we may say that the theory has not proved rigorously that a stabilisation of prices in a progressive economy must always lead to over-production, crisis and depression. The practical importance of this conclusion is considerable in view of the American prosperity in the twenties, a notable feature of which was the fact that wholesale prices did not rise.
- 229The following authors have developed the acceleration principle—Albert AFTALION, BICKERDIKE, Mentor BOUNIATIAN, T. N. CARVER, and MARCO FANNO. In recent years, it has been expounded most fully by J. M. CLARK, SIMON KUZNETS, A. C. PIGOU and R. F. HARROD. W. C. MITCHELL, D. H. ROBERTSON, and A. SPIETHOFF have incorporated it into their account of the cycle as a contributory factor. Mr. HARROD has, without much reference to the previous literature, rechristened the principle as “the Relation”.
- 230Furthermore, it can be shown that a mere stoppage of expansion without actual contraction is very likely to lead to serious trouble. The process of expansion and investment involves the banking system in heavy commitments for the future, not in the legal but in the economic sense. The newly started roundabout methods of production can be completed only if a flow of capital is available over a considerable period. If this flow is not forthcoming, the completion of the new schemes is impossible. This must not be interpreted in too narrow a sense. What is meant is not merely that the construction of an indivisible piece of investment, a railway line or a power-plant or a new Cunarder, may have to be interrupted. A much more important case is where a higher stage in the structure of production has been so much developed that it can work with full capacity only if the lower stages are adding to their equipment. If the steel industry, for example, has been developed to satisfy the needs of a rapid expansion in the building or automobile industry, it may suffer a contraction as soon as the building or automobile industry—without actually contracting—stops expanding and no longer adds to its equipment. This proposition will be discussed in greater detail in connection with the so-called “acceleration principle”. It explains or helps to explain why the transition from expansion to a stationary state is so difficult.
- 231(a) Professor RÖPKE has studied the question in various publications and has come to the conclusion that the process of deflation has a tendency to become cumulative and self-perpetuating. Genetically, it is true, it is connected with the extravagances of the preceding boom and the real maladjustment which the boom has produced. But the intensity of the deflation by no means necessarily corresponds to the extent of the over-investment. It is also untrue, he believes, that the deflation contributes (as is more or less vaguely suggested by the other authors of the monetary over-investment school) to bringing about the necessary adjustment (shortening) in the process of production. Once started, the deflation is propelled by its own momentum and by a number of institutional factors. What these factors are and how they work, we shall discuss at greater length in another connection. HAWTREY, KEYNES, PIGOU and ROBERTSON have contributed most towards the understanding of this phenomenon.
- 232In a later article, Professor OHLIN has given important elucidations of his theories. He explains there that his ex ante concepts of savings, investment as well as the other closely related pair of concepts—viz., demand and supply of credit—are intended to mean the same thing as demand and supply schedules. “Ex ante saving” means the schedule showing how much people are willing to save at different hypothetical rates of interest. And “ex ante investment” is the schedule showing how much people are planning to invest at different interest rates.
- 233But, as Professor NEISSER has shown, there is no reason to expect this return to the old arrangement, if the new roundabout methods of production have been brought to completion. When they are completed, the flow of consumers’ goods which was temporarily reduced will rise again, and will even reach a higher level than that from which the expansion started, so that consumers can safely expand their consumption. Forced saving will cease to be necessary when the new processes of production are completed. When they are completed, all that is required to maintain them is that the entrepreneurs—not the consumers—should refrain from “disinvestments”, that is, from consuming capital or from spending amortisation quotas on consumption. There is no reason why the old proportion between money spent for consumers’ and for producers’ goods should be restored. It is not true that the whole of newly injected money becomes income either at once or after a while. Part of it must be retained by the entrepreneurs in order to pay for intermediate goods (in contradistinction to payments for the original factors of production). In other words, only a part of the new money becomes income. Another part remains permanently in the business sphere. It is only if entrepreneurs “dissave”—i.e., if they eat up their capital and refrain from investing that part of their gross receipts which is not net income (working capital and amortisation quotas)—that the pre-inflation arrangement is restored.
- 234The whole stream of money or flow of purchasing power—that is, the demand for goods in terms of money per unit of time—is at any given point of time divided between producers’ goods and consumers’ goods. Since the productive process is split up into numerous successive stages—or, in other words, since the original factors of production (whatever that may mean) have to undergo numerous successive transformations before they are ready for final consumption—the money volume of transactions in producers’ goods per unit of time is a multiple of transactions in consumers’ goods. Much more money is spent per unit of time on producers’ goods in all stages than on consumers’ goods. If a part of income is saved and invested, ceteris paribus the proportion between the demand for consumers’ goods and the demand for producers’ goods is modified in favour of the latter; and it must be permanently modified because, by the act of saving, the stock of capital, as well as the volume of transactions in capital goods, has been permanently increased.
- 235The writers of the group under review are, however, well aware of the great danger that the discrepancy between the money rate and the equilibrium rate of interest, which prevailed during the depression, will at once be succeeded by a discrepancy in the opposite direction. In view of the falling prices and the state of pessimism and discouragement, the money rate during the downswing stands above the natural rate. When the fall of prices comes to an end and pessimism gives way to a more optimistic outlook, the current money rates, without being changed, will soon stand below the equilibrium rate. In other words, the equilibrium rate is likely to rise above the money rate. In terms of supply and demand, this can be expressed by saying that the credit demand curve will move to the right or, loosely speaking, that demand will rise. At the same time, the banks will be in a liquid position, and there is every reason to expect that they will liberally comply with the increased demand for credit. The barrier between the money market and the capital market is broken down, and the funds accumulated behind the barrier flow into the investment market.
- 236An analogous change in the proportion between money spent for consumers’ and producers’ goods may be induced by injections of bank credits for production purposes. But in that case, in contradistinction to the case of voluntary saving, there is a strong probability that individuals will tend to restore the old proportion. “Now, the sacrifice is not voluntary and is not made by those who will reap the benefit from the new investments. It is made by consumers in general who, because of the increased competition from the entrepreneurs who have received the additional money, are forced to forgo part of what they used to consume. . . There can be no doubt that, if their money receipts should rise again, they would immediately attempt to expand consumption to the usual proportion.” And receipts will rise sooner or later, for the new money is spent partly to hire labourers, partly to buy capital goods of all sorts; and in both cases the money, partly at once, partly after a while, becomes additional income in the hands of the owners of the factors of production.
- 237There is another factor which tends to swell the demand for consumers’ goods. Bookkeeping is more or less based on the assumption of a constant value of money. Periods of major inflations have shown that this tradition is very deeply rooted and that long and disagreeable experiences are necessary to change the habit. One of the consequences is that durable means of production—such as machines and factory buildings—figure in cost accounts at the actual cost of acquisition, and are written off on that basis. If prices rise, this procedure is illegitimate. The enhanced replacement cost should be substituted for the original cost of acquisition. This, however, is not done, or is done only to an insufficient extent and only after prices have risen considerably. The consequence is that too little is written off, paper profits appear, and the entrepreneur is tempted to increase his consumption. Capital in such case is treated as income. In other words, consumption exceeds current production.
- 238It is convenient at this point to introduce the question of the existence of unused productive resources of all kinds. The explanation given by the writers of the school under review for the upswing, or rather for the boom, almost invariably starts from an equilibrium position with full employment of the means of production. But the argument can easily be adapted to the other case. If there are unemployed resources, evidently the expansion of credit may go on much longer than when all resources are employed. There need, then, be no shift of factors from the lower to the higher stages, but only the absorption of unused resources predominantly in those stages of production which are especially stimulated by the expansion—namely, in the upper stages (capital goods industries). Arguing along the lines of the theory under review, one has to assume that the unemployed resources are mainly put to work in the higher stages (capital-goods industries). But, so long as there is a reserve of unemployed resources, the reaction from excess investment, which consists (as we have seen) of a comparative rise in the demand for consumers’ goods, will not produce a breakdown, since there is no necessity to detach factors of production from the higher stages. Prices need not rise much. The expansion of credit can go on.
- 239It should be observed that the diagram does not show savings and investment ex post; nor does it depict “the process”, set in motion by the ex ante difference between saving and investment, which brings about the equality ex post between saving and investment.
- 240It sounds perhaps paradoxical that a general increase in demand for consumers’ goods should have an adverse influence on the production of capital goods in general, which derive their economic value from the consumers’ goods which they help to produce. The paradox has puzzled many writers, but it is not difficult to explain. It should be borne in mind in the first place that the proposition holds good only if all factors of production are reasonably well employed or if at least some of the factors attracted to consumers’ goods trades would otherwise have been employed elsewhere. In other words, under full employment, the production of consumers’ good or that of producers’ goods are alternatives. At the end of the boom, the condition of reasonably full employment can as a rule be assumed to be true. Secondly, it is assumed that the demand for consumers’ goods rises relatively to the demand for producers’ goods. This second assumption excludes the possibility of a compensatory expansion of credit, since, if credit for the purpose of acquiring producers’ goods could be expanded pari passu with the increased demand for consumers’ goods, it would no longer be true that the proportion between demand for consumers’ goods and producers’ goods has changed. The change involves a rise in interest rates; for prosperity in consumers’ goods industries holds out good prospects of profits in the higher stages of production. Producers in the higher stages of production will be eager to continue lengthening the productive structure and will try to raise the necessary funds by borrowing from the banks. Demand for credit rises; but supply is unchanged, or not sufficiently changed—for it is assumed that credit ceases to expand, or does not expand sufficiently. This entails a rise in interest rates; and such a rise, as Professor HAYEK has shown, falls more heavily on production costs in the higher than in the lower stages of production. The situation is now, therefore, that money cost has risen, but demand has not risen (or not sufficiently risen), because the necessary funds are no longer forthcoming.
- 241Professor MISES gives the following answer to the question why the cycle of prosperity and depression recurs again and again. The behaviour of the banks is responsible for the occurrence of the business cycle. If the banks did not push the money rate below the natural rate by expanding credit, equilibrium would not be disturbed. But why do the banks make the same mistake again and again? “The answer must be: because the prevailing ideology among business-men and politicians looks on the reduction of the rate of interest as an important aim of economic policy, and because they consider an inflationary expansion of credit the best means to attain that objective” (page 58). “The root cause of the phenomenon that one business cycle follows the other is thus of an ideological nature” (page 60).
- 242The choice of the length of the unit period which suits Professor OHLTN’S theory is not to be made on the basis of the same principles as the choice of the length of Professor ROBERTSON’S unit period. The latter, Professor ROBERTSON’S “day”, is chosen so as to make it impossible, in view of the existing habits of payment, that money received during the day should be spent during the same day; Professor OHLIN’S unit period rests on the postulate that plans should remain unchanged during the period.
- 243The most prominent writers in this group are Professors A. SPIETHOFF and G. CASSEL. In the writings of these two authors (of SPIETHOFF especially), we find the culmination of a very important line of thought which can be traced back to MARX. Spiethoff’s immediate forerunner was the well-known Russian author TUGAN-BARANOWSKI. Both SPIETHOFF and CASSEL have had a great influence on business cycle theory, particularly in Germany, but also in the Scandinavian and Anglo-Saxon countries. WICKSELL himself adopted SPIETHOFF’S explanation of the cycle.
- 244If this cannot be achieved—and the chances that it will be achieved are almost nil—the new extensions to the structure of production are doomed to collapse. With some slight exceptions which are introduced as after-thoughts and treated as theoretical curiosities of no practical importance, the authors of the monetary over-investment school conclude that every credit expansion must lead to over-investment and to a breakdown. It is asserted over and over again with great emphasis that it is impossible to bring about a lasting increase in the capital stock of society as a whole by means of forced saving and that no permanent extension of the structure of production can be accomplished with the help of an inflationary credit expansion. What is thus built up during the upswing will inevitably be destroyed in the breakdown.
- 245An interesting question is how the composition of exports and imports of a country changes during the different phases of the cycle. It might be supposed that capital imports during the upswing are bound to be effected through the import of capital goods. As a general statement, this would, however, be wrong. In any given situation in respect of tariffs or otherwise, what a country imports will depend on the comparative cost situation or, in other words, on the comparative facilities of the various countries for the production of different types of goods. It is conceivable that capital for investment purposes may be imported, not in the shape of capital goods (raw materials, machinery, electrical equipment, etc.), but in the shape of consumers’ goods. This will be the case in a country where capital-goods industries and the production of raw materials are well developed, while consumers’ goods industries are less so.
- 246Let us now concentrate on what happens during any unit period. Professor OHLIN draws for the credit market an analogy with a village market for eggs where people appear with “alternative purchases and sales plans” as represented in their demand and supply curves. It is not quite clear how far the author wishes to carry this analogy, but if he carries it sufficiently far by taking a very short period, his theory really coincides with that of Professor Robertson, for ex ante saving then becomes saving out of the income received on the day before. Perhaps he would not want to go so far, because ex ante saving would then no longer be savings out of a future, expected and uncertain income, but out of an income which has already been received. On the other hand, the alternative construction presents very serious difficulties. Clearly, if planned savings were to mean savings out of a future income, which might not materialise at all, it would not be possible to say that “the price of 3% bonds—and thus the long-term rate of interest—is fixed on the bond market by the demand and supply curves in the same way as the price of eggs or strawberries on a village market” and to explain that planned savings constitue a part of the demand for bonds. How can future savings constitute supply of credit and affect the bond market before they are actually made?
- 247In his Prices and Production, Professor HAYEK argues that, even where the extension of the structure of production which entrepreneurs were induced to undertake by the artificial cheapening of credit is completed, the old arrangement tends to be restored later on for the reason that consumers will “attempt to expand consumption to the usual proportion” and “the money stream will be re-distributed between consumptive and productive uses” in the same, or nearly the same, proportion as it was distributed before such proportion was artificially distorted from the normal by the injection of money.
- 248It is evident that no collapse would occur if the credit expansion could go on indefinitely. It follows—the point is made by Professor HAYEK himself—that a crisis is equally inevitable in the case of voluntary saving if the flow of saving is suddenly reduced. It is, however, asserted—although the reasons given are not always quite convincing—that sudden changes are not likely to occur in respect of voluntary saving, while forced saving must come to an end abruptly. It is therefore very important to ask why should the expansion of credit stop. The answer is that in a closed economy, leaving out of account purely monetary and institutional factors (inability of the banking system to continue expansion within the limits fixed by the gold standard or some other legal or customary rules), the continuance of the expansion will involve a progressive rise in prices. A progressive rise in prices and the danger of a complete collapse of the monetary system is the only insurmountable barrier which prevents an indefinite continuation of the expansion.
- 249In any case, the theory in its fully developed form seems to make the emergence of a serious disequilibrium dependent upon relatively small fluctuations in the rate of forced saving. This being so, the question arises whether fluctuations of this order of magnitude are not equally likely to occur in the flow of voluntary savings. If they do occur, evil consequences must be expected, even in the absence of credit inflation. (We shall see, in connection with the discussion of other theories, that there are numerous other disturbances possible which may interrupt the upswing and start a vicious spiral downward—disturbances which are probably of the same, or even of a higher, order of magnitude than the fluctuations in the rate of forced or voluntary saving discussed above.)
- 250The most prominent writers in this group are Professors A. SPIETHOFF and G. CASSEL. In the writings of these two authors (of SPIETHOFF especially), we find the culmination of a very important line of thought which can be traced back to MARX. Spiethoff’s immediate forerunner was the well-known Russian author TUGAN-BARANOWSKI. Both SPIETHOFF and CASSEL have had a great influence on business cycle theory, particularly in Germany, but also in the Scandinavian and Anglo-Saxon countries. WICKSELL himself adopted SPIETHOFF’S explanation of the cycle.
- 251The theory of the depression is not nearly so fully elaborated by the authors of the monetary over-investment school as the theory of the boom. The depression was originally conceived of by them as a process of adjustment of the structure of production, and was explained in non-monetary terms. During the boom, they argued, the process of production is unduly elongated. This elongation has accordingly to be removed and the structure of production has to be shortened or, alternatively, expenditure on consumers’ goods must be reduced (by retrenchment of wages and other incomes which are likely to be spent wholly or mainly on consumers’ goods) sufficiently to make the new structure of production possible. This involves a lengthy and painful process of rearrangement. Workers are thrown out of work in the higher stages, and it takes time to absorb them in the lower stages of production. In modern times especially, with inflexible wage systems and the various other obstructions represented by all kinds of State intervention, this process of shifting labour and other means of production is drawn out much longer than is necessary for purely technological reasons.
- 252Both Professors SPIETHOFF and CASSEL emphatically assert that the business cycle is characterised by changes in the production of capital goods, especially of fixed capital equipment. The production of consumers’ goods does not exhibit the same regularity of change during the business cycle. Professor SPIETHOFF makes the point that upswings have occurred during which consumption has actually fallen. This was the case, according to him, in Germany in the years 1845-1847/48, when the economic situation of the working classes positively deteriorated because of rising food prices due to a series of crop failures. But, even if no account is taken of changes in agricultural production, which are only remotely connected with the ups and downs of industrial production, “the production of consumption goods shows no marked dependence on trade cycles. This means that the alternation between periods of boom and slump is fundamentally a variation in the production of fixed capital, but has no direct connection with the rest of production.”
- 253(a) Professor RÖPKE has studied the question in various publications and has come to the conclusion that the process of deflation has a tendency to become cumulative and self-perpetuating. Genetically, it is true, it is connected with the extravagances of the preceding boom and the real maladjustment which the boom has produced. But the intensity of the deflation by no means necessarily corresponds to the extent of the over-investment. It is also untrue, he believes, that the deflation contributes (as is more or less vaguely suggested by the other authors of the monetary over-investment school) to bringing about the necessary adjustment (shortening) in the process of production. Once started, the deflation is propelled by its own momentum and by a number of institutional factors. What these factors are and how they work, we shall discuss at greater length in another connection. HAWTREY, KEYNES, PIGOU and ROBERTSON have contributed most towards the understanding of this phenomenon.
- 254The monetary side of this process is not closely analysed. But Professor SPIETHOFF admits that “credit is an indispensable means to the upswing”. Professor CASSEL is less explicit in this respect. But it can be inferred from various remarks which he lets fall that he realises the necessity for an elastic currency supply. Both writers seem to believe that monetary funds are accumulated during the depression, on which the producers can draw during the upswing to finance the expansion. It follows that no positive steps need be taken by the banking system, at any rate during the first phases of the upswing. It is, however, not denied that, after a certain point, support by the banks is required to carry on. These monetary conditions and the monetary mechanism of credit expansion have been more thoroughly explored by the monetary school. In the writings of Professor ROBERTSON, Mr. KEYNES and Professor PIGOU (all of whom have much in common with SPIETHOFF and CASSEL) will be found the best synthesis of the monetary and non-monetary aspects of the process.
- 255The most coherent theory of the depression along these lines is that of Professor STRIGL. He admits that the breakdown of the boom induces a process of hoarding and deflation. After the breakdown of the boom, the banks will not merely stop expansion: they will contract credit in order to increase their liquidity. Under the influence of the general feeling of insecurity and pessimism, industrial firms will also seek to strengthen their cash reserves, and amortisation quotas will be kept in liquid form instead of being invested. This general struggle for liquidity involves hoarding. It means that money, whose function it is to be the vehicle of investment of real capital, fails to fulfil this function and is sterilised for the time being in swollen cash reserves or, in the case of bank money (deposits), annihilated altogether. The general price fall which ensues operates as a further deterrent to investment. The profit rate falls below the money rate. Perhaps the most important external symptom of this process is the intense liquidity and the extremely low rates on the money market which develop during the depression. The low money rates are caused by the fact that the overflow of funds from the money market to the capital market is impeded by an invisible barrier of distrust and pessimism.
- 256We may well start the discussion of this section with a famous metaphor from Professor SPIETHOFF’S forerunner—Michael TUGAN-BARANOWSKI. TUGAN-BARANOWSKI likens the working of the business-cycle mechanism to that of a steam-engine. “The accumulation of free, loanable capital plays the role of the steam in the cylinder; when the pressure of the steam on the piston attains a certain force, the resistance of the piston is overcome, the piston is set in motion and moves to the end of the cylinder; an opening appears for the steam and the piston recedes to its old position. In the same manner the accumulating free loan capital, after having attained a certain pressure, forces its way into industry, which it sets in motion; it is spent and industry returns to its earlier position.”
- 257For a long time, the theory of interest has had two distinct branches or stages. There is (a) the “pure” theory of interest in essentially non-monetary terms explaining the rate of interest as the price of capital, determined by the marginal productivity of capital in a technological sense and by certain psychological factors (time-preference) influencing the relative urgency of present and future needs; Professor MARGET calls these doctrines “real capital theories”. (That some writers, chiefly the followers of Böhm-Bawerk, go on to interpret marginal productivity of capital in terms of a lengthening or shortening of the period of production, whilst other writers object to that interpretation, has been mentioned on an earlier occasion.)
- 258It goes without saying that the writers of the group not only admit, but even stress, the fact that the pressure of deflation is intensified and prolonged by all kinds of ill-advised intervention by the State and other public bodies, such as the competitive raising of tariffs, the scramble for gold in order to liquidate existing gold-exchange standards, and all similar measures designed to keep up prices and incomes.
- 259The question of international complications has not been exhaustively and systematically treated by the theorists of the present group; but it is in principle not very difficult to imagine how the cyclical movement in one country must be assumed, from the point of view of the non-monetary over-investment theory, to influence other countries and to be influenced by international trade conditions. What has been said in this respect in connection with the monetary over-investment theory applies also to the non-monetary version of the over-investment school. It has been mentioned already that the opening of investment opportunities in new territories is considered to have been one of the most potent incentives for the revival of investment during the 19th century.
- 260This “common-sense” explanation of the rate of interest, and the more elaborate theory behind it, has been criticised by Mr. KEYNES and other writers. He has replaced it by a purely monetary theory, in which the rate of interest is completely divorced from the demand and supply of saving and explained instead by means of the “liquidity preference schedule” and the quantity of money.
- 261The concept “effective quantity of money” is very complicated. It is not easily defined in theory and is hopelessly difficult to measure statistically. The difficulty comes in principally through the factor “V”. The velocity of circulation meant is not the transaction velocity, nor is it the income velocity. One might perhaps call it trade velocity, the term being understood to cover all transactions which involve an exchange of goods in all stages of production, but to exclude financial transactions (e.g., on the stock exchange). If the quantity and the transaction velocity of money remain constant, but at the same time the requirements of the financial circulation rise, the result will be a decrease in the effective quantity of money as defined above. But these qualifications are not yet sufficient. Allowance must also be made for integration and disintegration of the process of production. If two or more successive stages in a particular line of industry (such as spinning and weaving), which are carried out by independent firms, are integrated by the formation of a vertical trust, the transfer of the intermediate product from the higher to the lower stage, which formerly gave rise to monetary transactions, may in future be effected by mere entries in the books of the new firm. Thus the merger may set free a certain amount of money. The trade velocity of money need not be changed, but the supply of money ought to be restricted; otherwise inflationary consequences will ensue.
- 262The following authors have developed the acceleration principle—Albert AFTALION, BICKERDIKE, Mentor BOUNIATIAN, T. N. CARVER, and MARCO FANNO. In recent years, it has been expounded most fully by J. M. CLARK, SIMON KUZNETS, A. C. PIGOU and R. F. HARROD. W. C. MITCHELL, D. H. ROBERTSON, and A. SPIETHOFF have incorporated it into their account of the cycle as a contributory factor. Mr. HARROD has, without much reference to the previous literature, rechristened the principle as “the Relation”.
- 263Criticising this scheme, Mr. KEYNES rightly points out that the amount saved depends, not only on the rate of interest, but also on the level of income. In fact, most writers agree concerning the manner in which the rate of saving depends on the level of income: the higher the income level of an individual, the higher tends to be the amount saved. It is not so clear, on the other hand, how a rise in interest rates will affect the rate of saving.
- 264The following authors have developed the acceleration principle—Albert AFTALION, BICKERDIKE, Mentor BOUNIATIAN, T. N. CARVER, and MARCO FANNO. In recent years, it has been expounded most fully by J. M. CLARK, SIMON KUZNETS, A. C. PIGOU and R. F. HARROD. W. C. MITCHELL, D. H. ROBERTSON, and A. SPIETHOFF have incorporated it into their account of the cycle as a contributory factor. Mr. HARROD has, without much reference to the previous literature, rechristened the principle as “the Relation”.
- 265The writers of the group under review are, however, well aware of the great danger that the discrepancy between the money rate and the equilibrium rate of interest, which prevailed during the depression, will at once be succeeded by a discrepancy in the opposite direction. In view of the falling prices and the state of pessimism and discouragement, the money rate during the downswing stands above the natural rate. When the fall of prices comes to an end and pessimism gives way to a more optimistic outlook, the current money rates, without being changed, will soon stand below the equilibrium rate. In other words, the equilibrium rate is likely to rise above the money rate. In terms of supply and demand, this can be expressed by saying that the credit demand curve will move to the right or, loosely speaking, that demand will rise. At the same time, the banks will be in a liquid position, and there is every reason to expect that they will liberally comply with the increased demand for credit. The barrier between the money market and the capital market is broken down, and the funds accumulated behind the barrier flow into the investment market.
- 266Take the following—static—situation. The value of the yearly output of (say) shoes is 100. The original and replacement cost of the fixed capital equipment—that is, of durable means of production which we shall call “machines”—required for this output is 500, 10% of which must be replaced each year, because the machinery wears out at that rate. In other words, the lifetime of such a machine is ten years. Under this assumption, new machines at the cost of 50 must be constructed each year for replacement. Now suppose the demand for shoes rises, so that, if it is to be satisfied, production must be increased by 10% to no a year. If there is no excess capacity and if methods of production are not changed, this increase necessitates an increase of 10% in the stock of fixed capital—that is, an additional production of machinery of 50, which brings the total production of machines from 50 to 100. So an increase of 10% in the demand for, and production of, finished goods necessitates an increase of 100% in the annual production of equipment. The absolute magnification of the change in demand is from 10 to 50; an increase in current production of 10 requires new investment of 50.
- 267To return to the dependence of the rate of saving upon the level of income: for each income level, a separate curve showing how much would be saved at different interest rates ought to be drawn. This being agreed upon, the next step in Mr. KEYNES’ criticism follows conclusively: the demand and supply curves of saving are not independent of one another. If, for instance, there appears a new stimulus to investment, if, that is to say, the investment demand curve shifts upward, income will, in general, rise and the supply curve of saving will shift too. Likewise, a shift in the latter will make the demand curve shift.
- 268This process has never been analysed so closely as the process of expansion starting from a position of full employment. But, applying the same type of reasoning, the conclusion seems to be as follows: A disequilibrium between the higher and the lower stages is produced by the fact that the unemployed resources are not distributed among the different stages of production in the way they ought to be if ultimate equilibrium is to emerge. A larger amount is absorbed into the higher stages than can in the long run be employed there with the given rate of voluntary saving. Thus the recovery from the depth of the depression has a wrong twist from the beginning.
- 269The assumption that replacement demand is constant calls for a quantitative qualification to which Professor FRISCH has drawn attention. If capital equipment is being continuously increased by equal amounts per unit of time, the demand for replacement must rise after a while to a new level. In our numerical example, this point would be reached after ten years, when the 50 additional machines of the first year are worn out and must be replaced. If at this point the demand for the finished product ceases to rise, the disappearance of the demand for additional machines will be compensated by the increase in replacement demand. Hence it is not quite correct to say that a decrease in the rate of increase of demand for the finished product must always lead to an actual decrease in the derived demand. It is worthy of note, however, that in each situation (under the conditions assumed) there is one, and only one, state of demand for finished goods—sometimes a rising or falling, sometimes a constant, demand—which will preserve stability in the demand for machines. The exact relationship between the various magnitudes involved could be formulated mathematically. We shall see later that a number of restricting and modifying qualifications must be made: it seems hardly worth while therefore at this point to attempt an absolute precision which cannot in any case be maintained in applying the theorem.
- 270Professor MISES believes, furthermore, that the commercial banks alone without the support of the central bank can never produce a dangerous credit inflation, because they would immediately lose cash and become insolvent. It is only with the backing of the central bank that it is possible to expand credit sufficiently to produce a dangerous boom. The ability of the central banks to increase the circulation is due to the monopoly which they hold of the issue of bank-notes. If the issue of notes were not a monopoly, if competition were restored in this field of the central banks’ activities—that is to say, if every bank had the right to issue notes, convertible into legal tender money (gold)—a dangerous expansion of credit and reduction of the interest rate would be impossible. The unsound banks would quickly be eliminated, and the sound banks would learn by experience that expansion is punished by bankruptcy.
- 271Professor MACHLUP has called attention to one factor which helps to explain the recurrence of the cycle and throws into relief the passive rôle of the banks, at any rate during the first phase of the upswing. It is this. A considerable portion of the payments which have to be made during a given period, say a year, are not evenly distributed, but are concentrated at certain dates, some of them at the end of each month and others at the end of each quarter. Therefore, even with the most elaborate clearing and compensation arrangements, no complete continuous offsetting of the debts and liabilities of each firm is possible. At the critical dates, at the end of the month and of the quarter, there is therefore always a strong demand for short-term credit and a resultant strain on the money market. If the banks were not able and willing to relieve this monthly and quarterly tightness of money by granting temporary credits, individual firms would be compelled to provide for their requirements at the critical dates by accumulating cash during the intervals between them. But, as the banks lend money to overcome these difficulties—credit expansion for such a temporary stringency being generally regarded as perfectly legitimate and safe—it is not necessary to accumulate cash, and the sums involved can be invested instead.
- 272We spoke of changes in “the requirements for capital equipment”. If we want to substitute for this “demand” for, or “production” of, capital goods, we must consider that demand and production cannot become negative. As soon as the production of capital goods falls to zero—the demand for the finished product continuing to decline—excess capacity will develop; and, when demand for the finished product rises again, the production of capital goods will not be resumed until after the accumulated surplus has been absorbed. So long as there is unused capacity (or dealers are overstocked), the acceleration principle of derived demand will not come into play.
- 273In a few cases, however, another definition is given of hoarding—viz.: “the quantity of money minus what is required to satisfy the transaction-motive” —in other words, idle or inactive money, including notes, coins and deposits or whatever is regarded as money. Net hoarding or dishoarding during a given period means, then, an increase or decrease of idle balances. This definition would seem to be roughly equivalent to the general meaning of the term. On some occasions, however, the two concepts are used interchangeably although what holds true of one of these concepts need not and will not be true of the other. In particular, the theory that any attempt of the public to hoard can only push up the interest rate, but cannot increase the aggregate amount hoarded unless the banking system increases the amount of money, is correct only if hoarding is defined in the wider (unusual) sense. If it is defined as an accumulation of idle balances, the public can hoard without any help from the banks. Even if the quantity of money is kept constant, the amount of idle balances can be increased by the public at the expense of active balances.
- 274It is clear that we have here a source of inflation; and the inflation, according to Professor MACHLUP, will not be confined to the single occasion of the first introduction of these “ultimo loans”, but will tend to recur cyclically. “While the utilisation of temporary surplus cash together with (inflationary) bank credit created the possibility of initiating illicitly long processes of production, the depression, after the elimination of the untenable enterprises, will release these sums again” (pages 175 and 176). During the depression, the investment of these sums is impossible, and they accumulate on the money market; but, as soon as the spirit of enterprise revives, they can be utilised for financing the boom for a long time without any, or with very little, additional bank credit.
- 275Any improvement in the balance of payments—that is to say, any increase in the demand for the means of payment of a given country in terms of the money of other countries—will have an expansionist influence. This improvement may be due to a great variety of circumstances—changes in the demand for particular commodities, crop changes, capital movements, etc. The erection of new tariff walls by an individual country, if not followed by compensatory action on the part of other countries, will have a favourable influence on the international monetary situation of the country which has raised its tariffs. In other words, it will enable the latter to expand its circulation without a deterioration of its exchange rate. Thus, the immediate influence of protectionist measures may be a stimulation of prosperity or an alleviation of depression. But the conditions in which this is true must be borne in mind. If many countries pursue this policy at the same time, the stimulating influence is lost. In the long run, the raising of tariff walls impairs the national dividends of all the countries involved. Indirect effects (e.g., on capital movements) may prevent even the immediate stimulation afforded by protectionist measures. Finally, an improvement in the balance of payments can always be utilised as a means of increasing the gold and foreign-exchange reserve in lieu of expanding the circulation.
- 276In arguing on the basis of the over-investment theory, special attention must be paid to international capital movements. They not only affect the purely monetary situation by stimulating or retarding the expansion or contraction of credit: they have also a bearing on the structure of production. An individual country may finance a boom, wholly or partly, by capital imports from other countries instead of by an internal expansion of credit and forced saving. So long as this is possible, the reaction which the theory under review holds responsible for the breakdown—namely, a corresponding rise in the demand for consumers’ goods—may be staved off. Thus, in so far as a particular country is concerned, the boom may be prolonged. On the other hand, international capital movements are subject to risks and disturbances which are absent in the case of an internal expansion.
- 277In this less ambitious sense, its validity can hardly be doubted. It should, however, be noted that this does not preclude the possibility of (a) there being causal connections between the production of consumers’ goods and investment of a different sort than the one postulated by our principle and even operating in the opposite direction in certain cases, and (b) the production of capital goods (investment) being influenced, not only by changes in the demand for consumers’ goods, but by other factors as well. It may perhaps be said that any investment, directly or indirectly, is looking forward to, and is made in the expectation of, a future demand for consumers’ goods. But, as Professor HANSEN has pointed out, there are types of investment which look forward for their utilisation to a very distant future—e.g., the opening up of a new region by the construction of a railroad. In such cases, the connection between the investment and the present state and recent movement of the demand for consumers’ goods is very slender. Long-run expectations determine investment decisions of this sort, and the influence of the current output of finished goods on these expectations can hardly be assumed to follow a uniformly defined quantitative pattern.
- 278The most valuable and original contributions of the monetary over-investment theory are (1) the analysis of the maladjustment in the structure of production brought about by the credit expansion during the prosperity phase of the cycle and (2) the explanation of the breakdown as consequent on that maladjustment. But our analysis has also shown that the theory is not in all respects complete. The claim to exclusive validity is open to doubt. It is a little difficult, for example, to understand why the transition to a more roundabout process of production should be associated with prosperity and the return to a less roundabout process a synonym for depression. Why should not the original inflationary expansion of investment cause as much dislocation in the production of consumers’ goods as the subsequent rise in consumers’ demand is said to cause in the production of investment goods?
- 279It has sometimes been assumed that, in order to utilise the acceleration principle for the explanation of the general business cycle, one has to presuppose a cyclical alternation of expansion and contraction in consumers’ demand. The acceleration principle then serves to explain the larger fluctuations in the capital-goods industries. The situation is, however, much more involved, because consumers’ demand and capital production (investment) interact on one another.
- 280Mr. KEYNES holds that the rate of interest, contrary to the traditional view, according to which it is “the reward of not spending” (on consumption), is “the reward of not hoarding”, “the reward for parting with liquidity for a specified period”. It “is a measure of the unwillingness of those who possess money to part with their liquid control over it. The rate of interest is not the ‘price’ which brings into equilibrium the demand for resources to invest with the readiness to abstain from present consumption. It is the ‘price’ which equilibrates the desire to hold wealth in the form of cash with the available quantity of cash.”
- 281Mr. KEYNES holds that the rate of interest, contrary to the traditional view, according to which it is “the reward of not spending” (on consumption), is “the reward of not hoarding”, “the reward for parting with liquidity for a specified period”. It “is a measure of the unwillingness of those who possess money to part with their liquid control over it. The rate of interest is not the ‘price’ which brings into equilibrium the demand for resources to invest with the readiness to abstain from present consumption. It is the ‘price’ which equilibrates the desire to hold wealth in the form of cash with the available quantity of cash.”
- 282The most prominent writers in this group are Professors A. SPIETHOFF and G. CASSEL. In the writings of these two authors (of SPIETHOFF especially), we find the culmination of a very important line of thought which can be traced back to MARX. Spiethoff’s immediate forerunner was the well-known Russian author TUGAN-BARANOWSKI. Both SPIETHOFF and CASSEL have had a great influence on business cycle theory, particularly in Germany, but also in the Scandinavian and Anglo-Saxon countries. WICKSELL himself adopted SPIETHOFF’S explanation of the cycle.
- 283Crises and Cycles, page 110.
- 284About the definition of the rate of interest, there is no real difference of opinion. Everybody means the same by “rate of interest” (at least, by the “explicit” rate of interest)—viz., “the price of debt” or of a loan which is evidently the same as a debt. Disagreement arises only when it comes to explaining the factors which determine the level of and fluctuations in the rate of interest.
- 285With regard to Professor CASSEL, it must be remarked that we are here dealing primarily with the theory as expounded in the earlier editions of his Theory of Social Economy. In his later books and especially in his popular writings, he has more or less accepted a purely monetary explanation, at least so far as the 1929-1936 depression is concerned.
- 286It is not clear whether he has visualised the theoretical possibility of replacement demand’s stepping into the shoes of new investment in such wise as to bring about a smooth transition to a stationary equilibrium.
- 287At first sight, this theory seems indeed revolutionary and to run counter to many well-established doctrines. This impression is strengthened by Mr. KEYNES’ apparent denials that an increase in the rate of saving, ceteris paribus, tends to lower the rate of interest; that a rise in the marginal efficiency of capital (demand for loanable funds) resulting, say, from a new invention or from a turn of the general sentiment towards optimism tends, ceteris paribus, to raise the rate of interest. He seems to imply, furthermore, that any increase in the quantity of money, ceteris paribus, tends to depress the interest rate (at least in the first instance, notwithstanding indirect and psychological repercussions).
- 288Both Professors SPIETHOFF and CASSEL emphatically assert that the business cycle is characterised by changes in the production of capital goods, especially of fixed capital equipment. The production of consumers’ goods does not exhibit the same regularity of change during the business cycle. Professor SPIETHOFF makes the point that upswings have occurred during which consumption has actually fallen. This was the case, according to him, in Germany in the years 1845-1847/48, when the economic situation of the working classes positively deteriorated because of rising food prices due to a series of crop failures. But, even if no account is taken of changes in agricultural production, which are only remotely connected with the ups and downs of industrial production, “the production of consumption goods shows no marked dependence on trade cycles. This means that the alternation between periods of boom and slump is fundamentally a variation in the production of fixed capital, but has no direct connection with the rest of production.”
- 289Mr. KEYNES distinguishes three motives for holding money: (i) the transactions-motive, (ii) the precautionary-motive and (iii) the speculative-motive. The transactions-motive is defined as “the need of cash for the current transactions of personal and business exchanges” and is split up into the “income-motive and business-motive”. “One reason for holding money is to bridge the interval between the receipt of income and its disbursement . . . and, similarly, the interval between the time of incurring business costs and that of the receipt of sales proceeds.” In other words, a certain amount of money is required to “handle” a certain income and a certain volume of transactions. How much money is needed depends on the velocity of circulation of money and is determined by the habits of payment and other factors which have been touched upon in an earlier chapter, where references to the relevant literature are to be found.
- 290Mr. KEYNES distinguishes three motives for holding money: (i) the transactions-motive, (ii) the precautionary-motive and (iii) the speculative-motive. The transactions-motive is defined as “the need of cash for the current transactions of personal and business exchanges” and is split up into the “income-motive and business-motive”. “One reason for holding money is to bridge the interval between the receipt of income and its disbursement . . . and, similarly, the interval between the time of incurring business costs and that of the receipt of sales proceeds.” In other words, a certain amount of money is required to “handle” a certain income and a certain volume of transactions. How much money is needed depends on the velocity of circulation of money and is determined by the habits of payment and other factors which have been touched upon in an earlier chapter, where references to the relevant literature are to be found.
- 291If we have correctly interpreted Professor SPIETHOFFS’ theory, his diagnosis of the disequilibrium at the end of the boom is substantially the same as that given by the monetary over-investment school. The allocation of factors of production to the various stages of production does not correspond to the flow of money. The lower stages in the structure of production are under-developed; the higher stages which produce capital goods are over-developed.
- 292By the speculative-motive, Mr. KEYNES means the inducement to hold money for the purpose “of securing profit from knowing better than the market what the future will bring forth”. If, for instance, one expects the price of debt (e.g., of bonds) to go down—that is, the rate of interest to rise—one will try to change from debt to money, to sell bonds and hold money. Mr. KEYNES believes that “general experience indicates that the aggregate demand for money to satisfy the speculative-motive usually shows a continuous response to gradual changes in the rate of interest—i.e., there is a continuous curve relating to changes in the demand for money to satisfy the speculative-motive and changes in the rate of interest as given by changes in the price of bonds and debts of various maturities”.
- 293By the speculative-motive, Mr. KEYNES means the inducement to hold money for the purpose “of securing profit from knowing better than the market what the future will bring forth”. If, for instance, one expects the price of debt (e.g., of bonds) to go down—that is, the rate of interest to rise—one will try to change from debt to money, to sell bonds and hold money. Mr. KEYNES believes that “general experience indicates that the aggregate demand for money to satisfy the speculative-motive usually shows a continuous response to gradual changes in the rate of interest—i.e., there is a continuous curve relating to changes in the demand for money to satisfy the speculative-motive and changes in the rate of interest as given by changes in the price of bonds and debts of various maturities”.
- 294Mr. KEYNES believes, furthermore, that it is roughly true that the total amount of money, M, can be divided into two parts, M1 and M2, of which the first part, M1, is held to satisfy the transactions and precautionary-motives and the second part, M2, to satisfy the speculative-motive. M1 may thus be called active or circulating money, whilst M2 is hoarded or idle or inactive money. M1 varies with the level of income or, rather, with the volume of transactions. M2 depends on the interest rate in such wise that it rises when the interest rate falls and falls when the interest rate rises.
- 295Such a situation is clearly possible, although it looks superficially paradoxical. The phenomenon (alleged to be frequent) of consumers’ goods industries feeling the setback of the depression much later than the capital-goods industry is regarded as a verification of the theory. Another question, which will be raised in connection with the discussion of rival theories, is whether this is the only possible outcome of the boom, or whether there is not another cause of the breakdown just as conceivable as a shortage of capital in the sense of a relative over-development of producers’ goods industries, which is again equivalent to under-saving or over-consumption.
- 296This would seem to be the most important new relationship introduced by Mr. KEYNES; new, not in the sense that it has never been suggested in the literature, but in the sense that it has never been carried through consistently. We may formulate this theorem also by saying that hoarding tends to be stimulated by a fall, and checked by a rise, in interest rates. Hoarding becomes cheaper when interest rates fall, and costly when they rise. In still other words, we may say that the velocity of circulation of money is positively correlated to the rate of interest.
- 297It will be convenient in the following analysis to distinguish sharply between liquidity preference in the wider sense and in the narrower sense. By the former, we mean the demand for money for all purposes, inclusive of the transaction purpose (M1 + M2); by the latter, demand for idle balances, M2, alone. The narrower definition corresponds better to the everyday meaning of the term “liquidity preference”. We shall therefore call it “liquidity preference proper” If somebody sells an asset against money and keeps the proceeds idle or if he refrains from spending all his money receipts as usual, we may describe that as an increase in his liquidity preference. Suppose, on the other hand, that wages rise but interest rates remain constant because the banks increase the money supply; then the average cash holdings of the working population will rise, and we have to describe that in Mr. KEYNES’ terminology as a rise in liquidity preference in the wider sense: more money is held for transaction purposes.
- 298In the first phase of the upswing, he says, the increase in production runs parallel to, or is even caused and encouraged by, a corresponding shift in the flow of money. That is to say, there is a strong tendency towards an acceleration of the formation of capital—i.e., an increase in the flow of savings. In the later phases, capital accumulation in this sense slows down, while the production of fixed capital equipment increases. The discrepancy between the flow of money and the trend of production eventually brings about the crisis. “The typical modern trade boom does not mean over-production, or an over-estimate of the demands of the consumers or the needs of the community for the services of fixed capital, but an over-estimate of the supply of capital, or of the amount of savings available for taking over the real capital produced. What is really over-estimated is the capacity of the capitalists to provide savings in sufficient quantity.”
- 299Many further details can be, and have been, added to the picture. Psychological and sociological factors can be adduced which may play a rôle in bringing about an acceleration or retardation in the response of entrepreneurs to existing opportunities for profitable investment. The psychological factors will be analysed separately. At this point, however, we may mention the explanation which Professor SCHUMPETER has offered for the fact that innovations appear en masse. One must distinguish, he says, between additions to our technological knowledge (that is, inventions which create the possibility of innovations in the productive processes actually employed) on the one hand and the practical introduction of the new methods on the other hand. What matters is not the discovery in the laboratory of a new process but the actual application of a new technique—it may be, a technique the feasibility of which was discovered a long time ago. There is no reason why inventions should not be distributed more or less evenly in time; but there are good reasons for believing that, in practice, new methods come into use in a mass. Only a few business-men have the imaginative power and energy successfully to introduce innovations such as new productive processes for the production of goods already on the market or the introduction of new types of goods, opening-up of new markets, improved methods of marketing and the like. But, while only a few are able to take the lead, many can follow. Once someone has gone ahead and demonstrated the profitability of a “new combination of the factors of production” (as Professor SCHUMPETER puts it), others can easily imitate him. Thus, whenever a few successful innovations appear, immediately a host of others follow them. (While Professor SCHUMPETER’S account of the revival and the description of the cumulative process of expansion fits in perfectly well with Professor SPIETHOFF’S theory, his story of the upper turning-point is quite different and will be considered later.)
- 300In Mr. KEYNES’ terminology, case (b) would have to be construed as a decrease in the liquidity preference of those who are “willing to release cash” which cancels the increase in the liquidity preference of the entrepreneurs and thus leaves the interest rate constant.
- 301In a recent contribution, “The ‘Ex-Ante’ Theory of the Rate of Interest”, Mr. KEYNES has modified, and elucidated, his theory in a way which makes its similarity with the loanable fund theory still clearer. In his General Theory, he explained that the demand for money depended on the rate of interest (determining the demand for idle balances) and on the actual level of activity (determining the demand for circulating balances). This, it is now admitted, was an incomplete statement. “The additional factor, previously overlooked, to which Professor OHLIN’S emphasis on the ex-ante character of investment decisions has directed attention, is the following.” There is a third factor affecting the demand for money—viz., the necessity of providing what Mr. KEYNES proposes to call “finance” for planned investment. Before activity has actually gone up, funds for the intended outlay must be secured. “During the interregnum—and during that period only—between the date when the entrepreneur arranges his finance and the date when he actually makes his investment, there is an additional demand for liquidity without, as yet, any additional supply of it necessarily arising” (page 665). The adherents of the loanable-fund theory would merely substitute “credits” for the word “liquidity” in this sentence.
- 302We may well start the discussion of this section with a famous metaphor from Professor SPIETHOFF’S forerunner—Michael TUGAN-BARANOWSKI. TUGAN-BARANOWSKI likens the working of the business-cycle mechanism to that of a steam-engine. “The accumulation of free, loanable capital plays the role of the steam in the cylinder; when the pressure of the steam on the piston attains a certain force, the resistance of the piston is overcome, the piston is set in motion and moves to the end of the cylinder; an opening appears for the steam and the piston recedes to its old position. In the same manner the accumulating free loan capital, after having attained a certain pressure, forces its way into industry, which it sets in motion; it is spent and industry returns to its earlier position.”
- 303The state of depression is interrupted (a) because it creates automatically a situation favourable to the revival of investment, (b) because pessimism disappears with the lapse of time, and (c) because of the introduction of stimuli from outside. Professor SPIETHOFF would probably subscribe to Professor PIGOU’S theory of the mutual generation of errors of optimism and pessimism (which will be discussed later on).
- 304One point regarding Mr. KEYNES’ theory of “finance” has given rise to an interesting discussion which throws much light on the whole issue. It is Mr. KEYNES’ insistence that “finance is essentially a revolving fund . . . . As soon as it is ‘used’ in the sense of being expended, the lack of liquidity is automatically made good and the readiness to become temporarily unliquid is available to be used over again.”
- 305Professor ROBERTSON objected that finance funds which have been spent can be made available for new financing only if they are saved (in Professor Robertson’S sense) by one of the successive recipients. Mr. KEYNES’ reply clearly indicated that there is no disagreement except a terminological one, due to the different definition of the concept of saving. Mr. KEYNES explains: “The demand for cash falls away unless the completed activity (associated with the expenditure of the finance funds) is being succeeded by a new activity.” It would appear that this condition might well be accepted by Professor ROBERTSON: for the primary activity will be succeded by a new one, if the money is again spent on consumption; if it is saved, the “chain of activities” is interrupted, the demand for cash falls away unless the saving leads to a fall in interest rates which stimulates investment, or unless the marginal efficiency of capital rises—changes which are excluded by Mr. KEYNES’ ceteris-paribus assumption.
- 306There is, however, an idea vaguely indicated at various points in Professor SPIETHOFF’S writings which can be used for the explanation of the regular recurrence of cycles of prosperity and depression. I mean the idea that the massing of the construction of fixed capital equipment at certain dates or during certain short periods of time gives rise to the recurrence of such outbursts of investment, or rather re-investment, in the future, owing to the fact that machinery and other durable equipment installed around a certain date will come up for replacement massed, although probably less densely, around a certain date in the future. This idea that, given an initial boom in capital construction, replacement tends to assume a cyclical pattern, that re-investment moves in cycles, can be traced back to Karl MARX. It has been fully elaborated with all necessary qualifications by Dr. Johan EINARSEN, who has also written its history and has applied the principle to a concrete case with the help of modern statistical devices in his admirable study, Reinvestment Cycles and their Manifestation in the Norwegian Shipping Industry.
- 307Some misunderstanding seems to have arisen in this connection from different interpretations of the ceteris-paribus clause. The classical writers, when they are not dealing with money and the business cycles, are in the habit of taking total monetary outlay as constant; it is included in the cetera that remain the same. Then a decrease in one division (consumption spending) implies an increase in the other (investment). Assuming the marginal efficiency of capital to be constant, this implies a fall in the interest rate. Mr. KEYNES, on the other hand, includes liquidity preference among the other things that remain unchanged; then, since M has remained unchanged, the rate of interest cannot fall.
- 308Now the loanable-fund theorists would not deny that this might happen, but they would describe it differently: people may hoard the money which they fail to spend. In Mr. KEYNES’ theory, this has to be described as a rise in liquidity preference proper; demand for money for “speculative purposes”, M2, has risen. This implies a decrease in M1, which is connected with the fall in activity. Thus total demand for money and the quantity of money remaining unchanged, the rate of interest remains unchanged too.
- 309The following authors have developed the acceleration principle—Albert AFTALION, BICKERDIKE, Mentor BOUNIATIAN, T. N. CARVER, and MARCO FANNO. In recent years, it has been expounded most fully by J. M. CLARK, SIMON KUZNETS, A. C. PIGOU and R. F. HARROD. W. C. MITCHELL, D. H. ROBERTSON, and A. SPIETHOFF have incorporated it into their account of the cycle as a contributory factor. Mr. HARROD has, without much reference to the previous literature, rechristened the principle as “the Relation”.
- 310It would appear from the foregoing discussion that Mr. KEYNES’ views on the question of how the rate of interest is influenced by changes in the propensity to consume (save) are not so radically different from the views of other authors as may at first sight appear. In a very recent exposition of his theory, Mr. KEYNES has himself suggested this. “The analysis which I gave in my General Theory of Employment is the same as the ‘general theory’ by Dr. LANGE on page 18 of his article.” On this page, Dr. LANGE states that “the traditional statement that the rate of interest . . . moves in the opposite direction to the propensity to save holds fully in our generalised theory”.
- 311It would appear from the foregoing discussion that Mr. KEYNES’ views on the question of how the rate of interest is influenced by changes in the propensity to consume (save) are not so radically different from the views of other authors as may at first sight appear. In a very recent exposition of his theory, Mr. KEYNES has himself suggested this. “The analysis which I gave in my General Theory of Employment is the same as the ‘general theory’ by Dr. LANGE on page 18 of his article.” On this page, Dr. LANGE states that “the traditional statement that the rate of interest . . . moves in the opposite direction to the propensity to save holds fully in our generalised theory”.
- 312It would appear from the foregoing discussion that Mr. KEYNES’ views on the question of how the rate of interest is influenced by changes in the propensity to consume (save) are not so radically different from the views of other authors as may at first sight appear. In a very recent exposition of his theory, Mr. KEYNES has himself suggested this. “The analysis which I gave in my General Theory of Employment is the same as the ‘general theory’ by Dr. LANGE on page 18 of his article.” On this page, Dr. LANGE states that “the traditional statement that the rate of interest . . . moves in the opposite direction to the propensity to save holds fully in our generalised theory”.
- 313Take the following—static—situation. The value of the yearly output of (say) shoes is 100. The original and replacement cost of the fixed capital equipment—that is, of durable means of production which we shall call “machines”—required for this output is 500, 10% of which must be replaced each year, because the machinery wears out at that rate. In other words, the lifetime of such a machine is ten years. Under this assumption, new machines at the cost of 50 must be constructed each year for replacement. Now suppose the demand for shoes rises, so that, if it is to be satisfied, production must be increased by 10% to no a year. If there is no excess capacity and if methods of production are not changed, this increase necessitates an increase of 10% in the stock of fixed capital—that is, an additional production of machinery of 50, which brings the total production of machines from 50 to 100. So an increase of 10% in the demand for, and production of, finished goods necessitates an increase of 100% in the annual production of equipment. The absolute magnification of the change in demand is from 10 to 50; an increase in current production of 10 requires new investment of 50.
- 314“The new level of income, however [Mr. KEYNES elaborates], will not continue sufficiently high for the requirements of M1 to absorb the whole of the increase in M; and some portion of the money will seek an outlet in buying securities or other assets until the rate of interest has fallen so as to bring about an increase in the magnitude of M2 and, at the same time, to stimulate a rise in Y to such an extent that the new money is absorbed either in M2 or in the M1 which corresponds to the rise in Y caused by the fall in the interest rate. Thus at one remove this case comes to the same thing as the alternative case where the new money can only be issued in the first instance by a relaxation of the conditions of credit by the banking system”, and thus automatically entails a fall in the interest rate.
- 315The assumption that replacement demand is constant calls for a quantitative qualification to which Professor FRISCH has drawn attention. If capital equipment is being continuously increased by equal amounts per unit of time, the demand for replacement must rise after a while to a new level. In our numerical example, this point would be reached after ten years, when the 50 additional machines of the first year are worn out and must be replaced. If at this point the demand for the finished product ceases to rise, the disappearance of the demand for additional machines will be compensated by the increase in replacement demand. Hence it is not quite correct to say that a decrease in the rate of increase of demand for the finished product must always lead to an actual decrease in the derived demand. It is worthy of note, however, that in each situation (under the conditions assumed) there is one, and only one, state of demand for finished goods—sometimes a rising or falling, sometimes a constant, demand—which will preserve stability in the demand for machines. The exact relationship between the various magnitudes involved could be formulated mathematically. We shall see later that a number of restricting and modifying qualifications must be made: it seems hardly worth while therefore at this point to attempt an absolute precision which cannot in any case be maintained in applying the theorem.
- 316Apart from terminological innovations, the real contribution brought by Mr. KEYNES’ General Theory of Interest would seem to consist, as we have seen, of the proposition that hoarding is a function of the rate of interest. This does not of course mean that factors other than the rate of interest may not also exert an influence as strong as that of the interest rate on the amount of inactive balances. In other words, even in the short run, shifts of the liquidity-preference schedule may be at least as important as movements along the curve.
- 317We spoke of changes in “the requirements for capital equipment”. If we want to substitute for this “demand” for, or “production” of, capital goods, we must consider that demand and production cannot become negative. As soon as the production of capital goods falls to zero—the demand for the finished product continuing to decline—excess capacity will develop; and, when demand for the finished product rises again, the production of capital goods will not be resumed until after the accumulated surplus has been absorbed. So long as there is unused capacity (or dealers are overstocked), the acceleration principle of derived demand will not come into play.
- 318If such a situation exists,—i.e., if the demand for money-to-hoard (liquidity preference curve proper) is perfectly elastic— “a rise in the schedule of the marginal efficiency of capital only increases employment, and does not raise the interest rate at all”. Likewise, a rise in the rate of saving (propensity to consume) decreases employment without decreasing the rate of interest. The idea that such a situation might arise is original and is of considerable theoretical interest.
- 319In this less ambitious sense, its validity can hardly be doubted. It should, however, be noted that this does not preclude the possibility of (a) there being causal connections between the production of consumers’ goods and investment of a different sort than the one postulated by our principle and even operating in the opposite direction in certain cases, and (b) the production of capital goods (investment) being influenced, not only by changes in the demand for consumers’ goods, but by other factors as well. It may perhaps be said that any investment, directly or indirectly, is looking forward to, and is made in the expectation of, a future demand for consumers’ goods. But, as Professor HANSEN has pointed out, there are types of investment which look forward for their utilisation to a very distant future—e.g., the opening up of a new region by the construction of a railroad. In such cases, the connection between the investment and the present state and recent movement of the demand for consumers’ goods is very slender. Long-run expectations determine investment decisions of this sort, and the influence of the current output of finished goods on these expectations can hardly be assumed to follow a uniformly defined quantitative pattern.
- 320The reason for the existence of a minimum, below which the rate of interest cannot possibly fall, we may paraphrase in the words of Dr. HICKS: “If the costs of holding money can be neglected, it will always be profitable to hold money rather than lend it out, if the rate of interest is not greater than zero. Consequently, the rate of interest must always be positive. In an extreme case, the shortest short-term rate may perhaps be nearly zero. But if so, the long-term rate must lie above it, for the long rate has to allow for the risk that the short rate may rise during the currency of the loan, and it should be observed that the short rate can only rise, it cannot fall. This does not only mean that the long rate must be a sort of average of the probable short rates over its duration, and that this average must lie above the current short rate. There is also the more important risk to be considered—that the lender on long term [e.g., bondholder] may desire to have cash before the agreed date of repayment, and then, if the short rate has risen meanwhile, he may be involved in a substantial capital loss.” Thus, in the words of Mr. KEYNES, “the rate of interest is a highly conventional phenomenon. For its actual value is largely governed by the prevailing view as to what its value is expected to be.” The argument is perhaps more intelligible when put in terms of asset prices (e.g., bond prices) instead of interest rates. If asset prices are expected to fall (long-term rates to rise), asset prices cannot remain at a level much higher than the expected price, because people would prefer, to keep their resources in cash, in spite of very low short rates.
- 321The reason for the existence of a minimum, below which the rate of interest cannot possibly fall, we may paraphrase in the words of Dr. HICKS: “If the costs of holding money can be neglected, it will always be profitable to hold money rather than lend it out, if the rate of interest is not greater than zero. Consequently, the rate of interest must always be positive. In an extreme case, the shortest short-term rate may perhaps be nearly zero. But if so, the long-term rate must lie above it, for the long rate has to allow for the risk that the short rate may rise during the currency of the loan, and it should be observed that the short rate can only rise, it cannot fall. This does not only mean that the long rate must be a sort of average of the probable short rates over its duration, and that this average must lie above the current short rate. There is also the more important risk to be considered—that the lender on long term [e.g., bondholder] may desire to have cash before the agreed date of repayment, and then, if the short rate has risen meanwhile, he may be involved in a substantial capital loss.” Thus, in the words of Mr. KEYNES, “the rate of interest is a highly conventional phenomenon. For its actual value is largely governed by the prevailing view as to what its value is expected to be.” The argument is perhaps more intelligible when put in terms of asset prices (e.g., bond prices) instead of interest rates. If asset prices are expected to fall (long-term rates to rise), asset prices cannot remain at a level much higher than the expected price, because people would prefer, to keep their resources in cash, in spite of very low short rates.
- 322Weighty arguments against the assumption that the expected rate of long-term interest (asset prices) is likely to persist unchanged for any length of time, in spite of a fall in the current short-term rate, have been brought forward by Mr. HAWTREY. We need however, not go into this matter more thoroughly, because Mr. KEYNES himself (quite rightly, it would seem) believes that this contingency of an “absolute liquidity-preference” is a theoretical possibility which has actually not yet arisen. “But whilst this limiting case”, in which “the monetary authority would have lost effective control over the rate of interest” (and in which, we may add, no fall in wages and prices could depress the rate of interest by releasing money from the transaction sphere), “might become practically important in future, I know of no example of it hitherto. Indeed, owing to the unwillingness of most monetary authorities to deal boldly in debts of long term, there has not been much opportunity for a test.” Nor, we may add, has the alternative to a policy of increasing the quantity of money—viz., a sustained fall of all prices and wages—been put to a real test.
- 323In this less ambitious sense, its validity can hardly be doubted. It should, however, be noted that this does not preclude the possibility of (a) there being causal connections between the production of consumers’ goods and investment of a different sort than the one postulated by our principle and even operating in the opposite direction in certain cases, and (b) the production of capital goods (investment) being influenced, not only by changes in the demand for consumers’ goods, but by other factors as well. It may perhaps be said that any investment, directly or indirectly, is looking forward to, and is made in the expectation of, a future demand for consumers’ goods. But, as Professor HANSEN has pointed out, there are types of investment which look forward for their utilisation to a very distant future—e.g., the opening up of a new region by the construction of a railroad. In such cases, the connection between the investment and the present state and recent movement of the demand for consumers’ goods is very slender. Long-run expectations determine investment decisions of this sort, and the influence of the current output of finished goods on these expectations can hardly be assumed to follow a uniformly defined quantitative pattern.
- 324Weighty arguments against the assumption that the expected rate of long-term interest (asset prices) is likely to persist unchanged for any length of time, in spite of a fall in the current short-term rate, have been brought forward by Mr. HAWTREY. We need however, not go into this matter more thoroughly, because Mr. KEYNES himself (quite rightly, it would seem) believes that this contingency of an “absolute liquidity-preference” is a theoretical possibility which has actually not yet arisen. “But whilst this limiting case”, in which “the monetary authority would have lost effective control over the rate of interest” (and in which, we may add, no fall in wages and prices could depress the rate of interest by releasing money from the transaction sphere), “might become practically important in future, I know of no example of it hitherto. Indeed, owing to the unwillingness of most monetary authorities to deal boldly in debts of long term, there has not been much opportunity for a test.” Nor, we may add, has the alternative to a policy of increasing the quantity of money—viz., a sustained fall of all prices and wages—been put to a real test.
- 325An almost perfectly elastic demand for idle balances up to a very considerable amount may occasionally occur, and has occurred temporarily (Mr. HAWTREY’S temporary credit deadlock), but the hypothesis that it may exist indefinitely has not yet been put to the test of fact.
- 326But, even if the proportion of fixed to working capital and the durability of the former is the same for A and B, it is quite possible that the shift in demand from A to B will create a net increase in demand for fixed capital (provided the machinery producing A is such that it cannot be used for the production of B). The principle of acceleration of derived demand works in both directions, as we know. But, in the downward direction, its operation is limited by the fact that production cannot fall below zero. If, therefore, in the case of a shift of demand from A to B, the demand for machinery producing A falls to zero, this loss may very well be more than compensated by an increase in the demand for new equipment producing B.
- 327“Three fundamental psychological factors—namely, the psychological propensity to consume, the psychological attitude to liquidity and the psychological expectation of future yield from capital assets”(which govern, together with “the given factors” capital equipment, etc., the marginal efficiency of capital or demand for capital)—constitute the skeleton of Mr. KEYNES’ theoretical system which “determines the national income and the quantity of employment.” Mr. KEYNES is careful to explain that these psychological propensities (together with some non-psychological factors such as the wage unit and the quantity of money) can only “sometimes” be regarded as the “ultimate independent variables” (page 246). He recognises that they are “themselves complex and that each is capable of being affected by prospective changes in the others” and, presumably, a fortiori, by actual changes in the others. (Thus we have seen that the liquidity preference is influenced by actual and prospective changes in the marginal efficiency of capital.)
- 328Crises and Cycles (1936), pages 102 et seq. See also his article “Socialism, Planning and the Business Cycle” in Journal of Political Economy, Vol. 44, June 1936. A similar analysis is to be found in R. G. Harrod, The Trade Cycle, Oxford (1936), page 165 and passim.
- 329Crises and Cycles, page 102.
- 330It should be kept in mind that the terms “propensity to consume (save)” and “marginal propensity to consume (save)” are usually used in the schedule sense—that is to say, they usually denote the whole schedule, showing what proportion of different hypothetical incomes or increments to income an individual or society as a whole would consume (save). Sometimes, however, when speaking of the propensity to consume, reference is made to a particular point (mainly the point actually realised) on the schedule of alternatives. Although it will usually be clear from the context in what sense the word is used, it would be better to speak, when not referring to the schedule as a whole, of “the rate of consumption (saving)” or, better still, of “the proportion of income consumed (saved)
- 331It will be well to keep in mind the logical nature of the “pure theory of the multiplier” which is clearly revealed by the foregoing discussion. The theory is not intended by Mr. KEYNES as a statement about a relationship in the real world between two distinguishable phenomena; there are not two facts, the marginal propensity to consume on the one hand, and the multiplier on the other, of which the former influences and governs the latter. The logical theory of the multiplier establishes a terminological rule for the use of the two terms “marginal propensity to consume” and “multiplier” and nothing more.
- 332The practical problem to the solution of which the theory of the multiplier and the attempts at a statistical measurement of its magnitude are directed is the determination, if possible in advance, of the indirect effects of Government expenditure on public works and the like. The underlying idea is that, if the Government spends several hundred million dollars on public investment and thereby creates additional employment, the first recipients of the money will spend at least a part of their income on consumption; the consumption industries will be stimulated; the money will be spent again and again; and a whole series of successive income- and employment-creating expenditure will emanate from the first investment. The question is, how big will be the secondary, tertiary, etc., effects flowing from the primary investment of a given magnitude? For the reasons given below, the pure theory of the multiplier cannot provide a final answer to that question.
- 333Some of these factors have been discussed by Mr. KEYNES (General Theory, pages 119 to 121), Mr. KAHN (loc. cit.), and by other writers in the considerable recent literature on expansionist policies in general and public works in particular.
- 334(2) Mr. KEYNES speaks only of “adverse reactions on investment” of a public works policy, but it may have favourable reactions too. Indeed, it is generally considered as a condition of success of a “pump priming policy” that it should stimulate private investment. Public investment may stimulate private investment either directly or by first stimulating consumption. All this is now well known and has been thoroughly discussed, but it all lies outside the pure theory of the multiplier.
- 335(3) But the theory of the multiplier needs to be expanded and qualified in other ways. By expressing the multiplier in terms of the marginal propensity to consume, the impression is conveyed that it is possible to base the analysis on a fairly stable psychological magnitude. People’s habits as to saving and spending are regarded as fairly constant, and this constancy and stability is transmitted by definition to the multiplier. A closer examination reveals, however, that this stability may be exaggerated. Mr. KEYNES speaks frequently of “the fundamental psychological law, upon which we are entitled to depend with great confidence both a priori from our knowledge of human nature and from the detailed facts of experience”; this law is to the effect that “men are disposed . . . to increase their consumption as their income increases, but not by as much as the increase in their income”. He refers to the consumer, and sometimes to society as a whole. But the marginal propensity to consume of society as a whole (which corresponds to the multiplier) cannot be identified with a psychological law about the behaviour of the individual consumer, for many other factors besides the consumers’ behaviour determine the marginal propensity to consume of the society.
- 336(a) As has been pointed out above (page 198), in the short run, the psychological traits of the individual in respect to saving and spending cannot safely be regarded as constant.
- 337(b) As Dr. STAEHLE has shown, changes in the distribution of income are very important for the propensity to consume of society as a whole, even from the short-run point of view. Since the propensities for different people or groups of people are different, a change in the distribution may give an unexpected turn to the marginal propensity to consume of society as a whole (contrary to the fundamental psychological law), even if the propensity of each individual is constant and conforms to “the fundamental psychological law”, to which Mr. KEYNES appeals. For this reason, in using the concept of the multiplier, allowance must be made for the changes in the distribution of income which are likely to be associated with a change in the level of incomes.
- 338Moreover, with respect to public expenditure, the distinction between consumption and investment is in many cases very arbitrary. Expenditure connected with the construction of battleships, river-dams and the like will be classified as investment. Dole payments to unemployed and expenditure for war veterans’ bonus will be counted as consumption expenditure and, if the Government borrows to meet this expenditure, as dissaving. But how are we to classify money paid to unemployed workers to perform “public works” of very doubtful value? Suppose these works consist of digging holes in the ground and filling them up again. Or suppose a road is built at a cost which far exceeds its value to the community. Evidently, the classification, and still more the estimate of the value of investment involved in such cases, is highly arbitrary and conventional. But the magnitude of the multiplier will be influenced by such arbitrary decisions. The fewer are the doubtful cases regarded as investment and the lower is the investment value assumed in each case, the greater will be the multiplier—that is, the marginal propensity to consume of society as a whole. Hence the value of the latter will pro tanto depend upon these arbitrary classifications and not on the psychological propensities of the consumer.
- 339Moreover, with respect to public expenditure, the distinction between consumption and investment is in many cases very arbitrary. Expenditure connected with the construction of battleships, river-dams and the like will be classified as investment. Dole payments to unemployed and expenditure for war veterans’ bonus will be counted as consumption expenditure and, if the Government borrows to meet this expenditure, as dissaving. But how are we to classify money paid to unemployed workers to perform “public works” of very doubtful value? Suppose these works consist of digging holes in the ground and filling them up again. Or suppose a road is built at a cost which far exceeds its value to the community. Evidently, the classification, and still more the estimate of the value of investment involved in such cases, is highly arbitrary and conventional. But the magnitude of the multiplier will be influenced by such arbitrary decisions. The fewer are the doubtful cases regarded as investment and the lower is the investment value assumed in each case, the greater will be the multiplier—that is, the marginal propensity to consume of society as a whole. Hence the value of the latter will pro tanto depend upon these arbitrary classifications and not on the psychological propensities of the consumer.
- 340(d) Mr. KEYNES expresses the view that, in the short run, the marginal propensity to consume (multiplier) may deviate from its “normal” value, but he assumes that it will gradually return to it. Such a deviation will occur if producers of consumers’ goods do not foresee the increase in demand resulting from an expansion in the capital-goods industries. Then, momentarily, prices of consumers’ goods will rise or stocks be depleted. The same is true when full employment is reached or bottle-necks prevent consumers’ goods industries from expanding. All these factors, which cannot be said to be governed by a psychological law, must be taken into account in order to determine the marginal propensity to consume of the community (multiplier).
- 341(e) Certain difficulties arise when we consider the relation between the multiplier and the income velocity of circulation of money. Suppose the psychological marginal propensity to consume of those who receive money from the Government through public works is unity; that is, they save nothing, but spend the whole amount they receive on consumption. This is a conceivable situation, even if it is deemed unlikely. For reasons which will be discussed at some length in the second part of this book (Chapter 10, § 6), we should normally expect the secondary effects of a public works policy to be greater in that case than if the marginal propensity to consume was smaller than 1. But we should not expect to find an infinite rise in demand for consumption goods. This is, however, what follows from the assumption that Mr. KEYNES’ marginal propensity to consume for society as a whole is unity; for this latter implies, as we have seen, that the multiplier is infinite. As Mr. KEYNES’ says, “the logical theory of the multiplier . . . holds good continuously, without time-lag, at all moments of time”. Hence, as there will, in fact, be some time-lag between the receipt of money and its expenditure, and since this time-lag will prevent an increase in investment from causing an immediate rise in consumption to infinity, we must say, in Mr. KEYNES’ language, that there is a temporary distortion of the propensity to consume, and that consumption will only gradually tend to increase to infinity if the net increase in investment expenditure is permanently maintained. Hence, to determine the secondary effects, in time, of new public expenditure, we need, in addition to the information about the marginal propensity to consume of the various individuals, also information about the income velocity of money. This point has been well discussed by Professor J. M. CLARK (op. cit.).
- 342We are now in a position to sum up the conclusions of our discussion. The pure theory of the multiplier shows the definitional relation between the “propensity to consume” and the multiplier. Many problems which are frequently discussed under the heading “multiplier” lie outside the pure theory of the multiplier. They can be divided into two groups, those relating to (a) the determination of the amount of net investment associated with a given amount of spending under varying circumstances and (b) the determination of the numerical value of the multiplier. The marginal propensity to consume of the individual to which Mr. KEYNES’ fundamental psychological law refers, is only one of many factors which are causally important for the determination of the marginal propensity to consume (multiplier) of society as a whole. For this reason, care must be taken not to exaggerate the stability of the multiplier, which cannot be treated as a datum, but must be included among the variables (quaesita) of the theoretical system.
- 343Mr. KEYNES’ theory does not furnish a readymade answer to the riddle of the business cycle, but is intended to supply tools for the analysis of all sorts of problems concerning short-term fluctuations as well as long-run conditions. “The object of our analysis is . . . to provide ourselves with an organised and orderly method of thinking out particular problems; and, after we have reached a provisional conclusion by isolating the complicating factors one by one, we then have to go back on ourselves and allow, as well as we can, for the probable interaction of the factors amongst themselves. This is the nature of economic thinking.”
- 344The analysis of the preceding pages should have made it abundantly clear that Mr. KEYNES’ theoretical apparatus is not incompatible with any one of the theories of the cycle, or particular phases thereof, which have been reviewed earlier in this book. All these theories can be expressed in Keynesian language. Mr. KEYNES’ own application of his theoretical apparatus to the typical business cycles, as contained in his “Notes on the Trade Cycle”, have been briefly reviewed above in connection with the psychological theories (Chapter 6).
- 345Let us now consider the interrelation of the last two schedules—the liquidity-preference schedule, the quantity of money and hence the interest rate being given and remaining unchanged. In wealthy communities, the propensity to save (consume) is great (small). Therefore much investment is needed to “fill the gap” between total output and that part of it which the “community chooses” to consume. There is no guarantee that at full employment there are enough opportunities to invest (at the given rate of interest) to maintain full employment. If, as frequently happens, not enough investment is forthcoming, the level of employment and income must fall. This fall will induce people to save less of their income; some may even draw on accumulated resources and consume more than their income—i.e., may dissave. Likewise, “the Government will be liable, willingly or unwillingly, to run into a budgetary deficit”, in order to provide for relief, etc., which is equivalent to a strengthening of the propensity to consume of society as a whole. Thus a new equilibrium will be reached when saving has fallen sufficiently for investment to fill the gap between ouput and consumption. It is not difficult to introduce here the liquidity-preference schedule: when income falls, money is liberated from the transaction sphere, M1 falls, M2 rises, the interest rate falls, and equilibrium can be reached at a higher level than if interest rates had not fallen.
- 346The three schedules, together with the quantity of money and some other data such as the available factors of production (labour, equipment, etc.) and the wage-unit, determine the level of employment and unemployment. Hence it is impossible to blame any one of the three “psychological factors” (schedules) above for the absence of full employment. Or, if one chooses, one may attribute the existing unemployment to either one alternatively, if all the other data are given: other things being given, employment would be greater (smaller), if the propensity to consume was greater (smaller) than it actually is. Or: other things being given, employment would rise, if the liquidity-preference were to fall; or if the marginal efficiency of capital were greater, etc.
- 347It is now easy to see that any one of the various hypotheses concerning the causes of the downturn or the upturn of the business cycle which we have reviewed in the earlier chapters is compatible with, and can be expressed in terms of, Mr. KEYNES’ theoretical apparatus. Employment may start to fall, (a) because the propensity to save has become stronger without an offsetting weakening of the liquidity-preference; (b) because, for one reason or the other, the marginal efficiency of capital collapses (that is Mr. KEYNES’ own tentative hypothesis for the crisis in the typical trade cycle); (c) because the liquidity-preference proper becomes stronger (i.e., because M2 increases—i.e., people hoard) or the banks contract the quantity of money.
- 348Similarly, dishoarding by private individuals has to be described as a decrease of liquidity-preference proper (shift to the left of the liquidity-preference curve) coupled with an increase either of the marginal propensity to consume (if the money is spent on consumption) or an increase in the marginal efficiency of capital (if the money is spent on investment goods). In both cases, it tends to stimulate employment.
- 349So far, we have detected a number of terminological differences between Mr. KEYNES’ theory and the traditional views as represented by, say, Professor PIGOU’S Industrial Fluctuations, Professor ROBERTSON’S writings or the synthesis attempted in Part II of the first edition of this book, which is reproduced, with slight changes, in the present edition. In addition, we have suggested (cf. pages 209 and 218 above) that Mr. KEYNES has made an important contribution by his insistence on the relationship between “hoarding” and the rate of interest. Apart from this, we have not as yet discovered any essential differences between Mr. KEYNES’ theory and that of the other recognised authorities. According to Mr. KEYNES, however, there is a fundamental discrepancy between the two, inasmuch as the “classical” theory cannot conceive at all of an equilibrium with less than full employment. “The classical theory is only applicable to the case of full employment.” More precisely, it is involuntary unemployment which is, according to Mr. KEYNES, incompatible with classical equilibrium; voluntary unemployment may, of course, exist in equilibrium; that is to say, if some people prefer not to work at the prevailing wage, they are not counted as unemployed; or “an eight-hour day does not constitute unemployment because it is not beyond human capacity to work ten hours” (page 15).
- 350Involuntary unemployment, which classical theory is accused of having overlooked, or being unable to explain, is defined as follows: “Men are involuntarily unemployed if, in the event of a small rise in the price of wage-goods relatively to the money-wage [we could also say: in the event of a fall in real wages], both the aggregate supply of labour willing to work for the current money-wage and the aggregate demand for it at that wage would be greater than the existing volume of employment”
- 351A difference of opinion can and does exist only in respect of the consequences and desirability of free competition in the labour market, which would ensure a complete flexibility of wages. However, the following two propositions would presumably be accepted both by Mr. KEYNES and by the classical school. First, if there is free competition in the labour market, money-wages will fall continuously, so long as there is unemployment. A situation in which wages fall continuously can hardly be called an equilibrium position. Secondly, in point of fact wages are, and probably have always been, rigid, because of trade-union resistance, unemployment relief, tradition, etc.
- 352There seems to exist, however, a real difference of opinion between Mr. KEYNES and the classical school concerning the influence of a fall in money-wages on employment. Mr. KEYNES expresses the view that, “with a given organisation, equipment and technique”, an increase in output and employment necessitates a fall in real wages. But whilst the “classical theory assumes that it is always open to labour to reduce its real wage by accepting a reduction in the money-wage”, Mr. KEYNES’ contention is that “there may exist no expedient by which labour as a whole can reduce its real wage to a given figure by making revised money bargains with the entrepreneur”; the reason being that “prices change in almost the same proportion, leaving the real wage . . . practically the same as before”. Mr. KEYNES is, however, careful to add that “this argument would . . . contain . . . a large element of truth, though the complete results of a change in money-wages are more complex”. In Chapter 19, “Changes in Money-Wages”, he discusses the question in detail, and introduces many modifications into the original simple argument; but the argument is sometimes presented by economists in its simple unmodified form. A closer analysis of this chapter seems to suggest that there is no fundamental difference between Mr. KEYNES’ results and those reached by those more orthodox writers (such as Professor PIGOU in his Industrial Fluctuations) who pay attention to possible short-period repercussions of wage reductions. Since there is substantial agreement, except in terminology, between Mr. KEYNES’ analysis and the one given in Chapter 11, § 9, of the present book, only a few points will be raised in this connection.
- 353There seems to exist, however, a real difference of opinion between Mr. KEYNES and the classical school concerning the influence of a fall in money-wages on employment. Mr. KEYNES expresses the view that, “with a given organisation, equipment and technique”, an increase in output and employment necessitates a fall in real wages. But whilst the “classical theory assumes that it is always open to labour to reduce its real wage by accepting a reduction in the money-wage”, Mr. KEYNES’ contention is that “there may exist no expedient by which labour as a whole can reduce its real wage to a given figure by making revised money bargains with the entrepreneur”; the reason being that “prices change in almost the same proportion, leaving the real wage . . . practically the same as before”. Mr. KEYNES is, however, careful to add that “this argument would . . . contain . . . a large element of truth, though the complete results of a change in money-wages are more complex”. In Chapter 19, “Changes in Money-Wages”, he discusses the question in detail, and introduces many modifications into the original simple argument; but the argument is sometimes presented by economists in its simple unmodified form. A closer analysis of this chapter seems to suggest that there is no fundamental difference between Mr. KEYNES’ results and those reached by those more orthodox writers (such as Professor PIGOU in his Industrial Fluctuations) who pay attention to possible short-period repercussions of wage reductions. Since there is substantial agreement, except in terminology, between Mr. KEYNES’ analysis and the one given in Chapter 11, § 9, of the present book, only a few points will be raised in this connection.
- 354There seems to exist, however, a real difference of opinion between Mr. KEYNES and the classical school concerning the influence of a fall in money-wages on employment. Mr. KEYNES expresses the view that, “with a given organisation, equipment and technique”, an increase in output and employment necessitates a fall in real wages. But whilst the “classical theory assumes that it is always open to labour to reduce its real wage by accepting a reduction in the money-wage”, Mr. KEYNES’ contention is that “there may exist no expedient by which labour as a whole can reduce its real wage to a given figure by making revised money bargains with the entrepreneur”; the reason being that “prices change in almost the same proportion, leaving the real wage . . . practically the same as before”. Mr. KEYNES is, however, careful to add that “this argument would . . . contain . . . a large element of truth, though the complete results of a change in money-wages are more complex”. In Chapter 19, “Changes in Money-Wages”, he discusses the question in detail, and introduces many modifications into the original simple argument; but the argument is sometimes presented by economists in its simple unmodified form. A closer analysis of this chapter seems to suggest that there is no fundamental difference between Mr. KEYNES’ results and those reached by those more orthodox writers (such as Professor PIGOU in his Industrial Fluctuations) who pay attention to possible short-period repercussions of wage reductions. Since there is substantial agreement, except in terminology, between Mr. KEYNES’ analysis and the one given in Chapter 11, § 9, of the present book, only a few points will be raised in this connection.
- 355There seems to exist, however, a real difference of opinion between Mr. KEYNES and the classical school concerning the influence of a fall in money-wages on employment. Mr. KEYNES expresses the view that, “with a given organisation, equipment and technique”, an increase in output and employment necessitates a fall in real wages. But whilst the “classical theory assumes that it is always open to labour to reduce its real wage by accepting a reduction in the money-wage”, Mr. KEYNES’ contention is that “there may exist no expedient by which labour as a whole can reduce its real wage to a given figure by making revised money bargains with the entrepreneur”; the reason being that “prices change in almost the same proportion, leaving the real wage . . . practically the same as before”. Mr. KEYNES is, however, careful to add that “this argument would . . . contain . . . a large element of truth, though the complete results of a change in money-wages are more complex”. In Chapter 19, “Changes in Money-Wages”, he discusses the question in detail, and introduces many modifications into the original simple argument; but the argument is sometimes presented by economists in its simple unmodified form. A closer analysis of this chapter seems to suggest that there is no fundamental difference between Mr. KEYNES’ results and those reached by those more orthodox writers (such as Professor PIGOU in his Industrial Fluctuations) who pay attention to possible short-period repercussions of wage reductions. Since there is substantial agreement, except in terminology, between Mr. KEYNES’ analysis and the one given in Chapter 11, § 9, of the present book, only a few points will be raised in this connection.
- 356The following authors have developed the acceleration principle—Albert AFTALION, BICKERDIKE, Mentor BOUNIATIAN, T. N. CARVER, and MARCO FANNO. In recent years, it has been expounded most fully by J. M. CLARK, SIMON KUZNETS, A. C. PIGOU and R. F. HARROD. W. C. MITCHELL, D. H. ROBERTSON, and A. SPIETHOFF have incorporated it into their account of the cycle as a contributory factor. Mr. HARROD has, without much reference to the previous literature, rechristened the principle as “the Relation”.
- 357There seems to exist, however, a real difference of opinion between Mr. KEYNES and the classical school concerning the influence of a fall in money-wages on employment. Mr. KEYNES expresses the view that, “with a given organisation, equipment and technique”, an increase in output and employment necessitates a fall in real wages. But whilst the “classical theory assumes that it is always open to labour to reduce its real wage by accepting a reduction in the money-wage”, Mr. KEYNES’ contention is that “there may exist no expedient by which labour as a whole can reduce its real wage to a given figure by making revised money bargains with the entrepreneur”; the reason being that “prices change in almost the same proportion, leaving the real wage . . . practically the same as before”. Mr. KEYNES is, however, careful to add that “this argument would . . . contain . . . a large element of truth, though the complete results of a change in money-wages are more complex”. In Chapter 19, “Changes in Money-Wages”, he discusses the question in detail, and introduces many modifications into the original simple argument; but the argument is sometimes presented by economists in its simple unmodified form. A closer analysis of this chapter seems to suggest that there is no fundamental difference between Mr. KEYNES’ results and those reached by those more orthodox writers (such as Professor PIGOU in his Industrial Fluctuations) who pay attention to possible short-period repercussions of wage reductions. Since there is substantial agreement, except in terminology, between Mr. KEYNES’ analysis and the one given in Chapter 11, § 9, of the present book, only a few points will be raised in this connection.
- 358According to Mr. KEYNES, the “accepted explanation” of the consequences of a reduction of money-wages starts from the assumption that aggregate effective demand remains unchanged; then, naturally, employment will rise. Mr. KEYNES points out (as was observed in the first edition of this book) that this assumption assumes away almost the whole problem. It may be legitimate in a rigid equilibrium theory which deliberately argues under the simplifying assumption of constant aggregate demand; but it is certainly illegitimate in business-cycle theory, and it is usually not made there.
- 359In his view, a “reduction in money-wages will have no lasting tendency to increase employment except by virtue of its repercussions either on the propensity to consume for the community as a whole, or on the schedule of marginal efficiencies of capital, or on the rate of interest”. This is true, because the three terms are so defined that any change in output and employment resulting from a fall in money-wages must be describable in terms of one or the other, or a combination of the three magnitudes mentioned. If investment output rises, the rate of interest and consumption having remained unchanged, the marginal efficiency of capital schedule is said to have shifted; if consumption rises without an increase in investment and without a change in the interest rate, the propensity to consume of the community as a whole is said to have increased, etc.
- 360Mr. KEYNES, however, characterises such influences of wage reductions on employment as “roundabout repercussions”, and suggests that the classical theory erroneously supposes that there is a direct route by which wage reductions may affect output and employment without affecting the propensity to consume, the marginal efficiency of capital or the rate of interest. But, in fact, the repercussion may be quite direct, even though it can always be expressed in Mr. KEYNES’ terminology if one desires to do so. Let us take the most straightforward case. Suppose wages in a pure consumption trade, say, of domestic servants, are reduced and the elasticity of demand for these services is unity. Then the consumption of these services and employment will rise. The effect of the wage reduction on employment is obviously direct; but in Mr. KEYNES’ terms we must describe it as an influence via an increase in the propensity to consume.
- 361We conclude once more that, according to Mr. KEYNES’ theory, his equilibrium with unemployment can exist only if money-wages are rigid in the downward direction. This seems quite inescapable; and if Mr. KEYNES never quite admits it, at one point he comes very near to doing so: if there were “competition between unemployed workers”, “there might be no position of stable equilibrium except in conditions consistent with full employment, since the wage-unit might have to fall without limit until it reached a point where the effect of the abundance of money in terms of the wage-unit on the rate of interest was sufficient to restore a level of full employment. At no other point could there be a resting-place.”
- 362From this statement, with which all adherents of the classical school would agree, it does not, however, follow that very flexible wages (absolutely perfect competition in the labour market) are necessarily the best policy to get rid of unemployment. One may still hold with KEYNES that, under such conditions, prices may become very unstable, which may make business calculations difficult and affect unfavourably the marginal efficiency of capital. The problem is a pressing one which has not yet been solved satisfactorily. Is absolute flexibility or is a certain degree of rigidity of prices and money-wages more conducive to stability of real income? There is one section where competition has been strong and prices have been very flexible—viz., agriculture. During the last depression, for instance, prices of agricultural products fell drastically, but output and employment were maintained. In industry (especially in capital-goods and durable-goods industries), prices were better maintained, but output shrank. It goes without saying that, for the farming population, that is a very unfavourable situation. But many people would argue that, if industry behaved like agriculture, prices would fall all around, but production would be well maintained. This may be so, but it must be said that it has not yet been rigorously proven. It may well be, as KEYNES says, that violent fluctuations of prices, and in particular reductions of prices, would create great uncertainty and very unfavourably affect the demand for capital and the willingness to invest. Thus the result may be that unemployment could be eliminated and the labour market cleared by a very drastic cut in wages, but at the price of a fall of real wages to a very low level. (Thus Mr. KEYNES’ assertion that prices would fall pari passu with a fall in wages—which has been carried to extreme lengths by Mr. LERNER, loc. cit.—may be unduly optimistic.) In other words, if owing to rapid price changes entrepreneurs became very pessimistic, or at least very uncertain about the future, the demand for labour might become very inelastic.
- 363Hence, although the classical theory is right in saying that an equilibrium with unemployment is incompatible with competition in the labour market, it does not necessarily follow that plasticity of wages would eliminate depressions. (Compare the cautious and well-balanced treatment of this problem in Professor PIGOU’S Industrial Fluctuations, Chapter XX, “The Part played by Rigidity in Wage Rates”).
- 364At the beginning of this section (see page 233 above), it was stated that the depression theory most frequently associated with Mr. KEYNES’ theoretical system is an under-consumption or over-saving theory. This statement may not seem to have been borne out by the detailed analysis of Mr. KEYNES’ pure theory in the preceding pages. It is nevertheless true in the sense that Mr. KEYNES, in many places, emphasises the low propensity to consume prevailing in rich countries as the main source of troubles. “But worse still. Not only is the marginal propensity to consume weaker in a wealthy country, but, owing to its accumulation of capital being already larger, the opportunities for further investment are less attractive” (page 31). Moreover, in various places, the spectre is raised of a lower limit to a fall in the rate of interest “which in present circumstances may perhaps be as high as 2% or 2½% on long term. If this should prove correct, the awkward possibility of an increasing stock of wealth, in conditions where the rate of interest can fall no further under laissez-faire, may soon be realised in actual experience.” “The post-war experiences of Great Britain and the United States are, indeed, actual examples of how an accumulation of wealth, so large that its marginal efficiency has fallen more rapidly than the rate of interest can fall in the face of the prevailing institutional and psychological factors, can interfere, in conditions mainly of laissez-faire, with a reasonable level of employment and with the standard of life which the technical conditions of production are capable of furnishing” (page 219). “I should guess that a properly run community equipped with modern technical resources, of which the population is not increasing rapidly, ought to be able to bring down the marginal efficiency of capital in equilibrium approximately to zero within a single generation” (page 220). Mr. KEYNES believes “it to be comparatively easy to make capital goods so abundant that the marginal efficiency of capital is zero” (page 221).
- 365However, the clear realisation of all the necessary qualifications of these theories cannot definitely disprove their validity, although it may reduce their persuasiveness. Only the careful scrutiny of a mass of experience and the study of historical processes can make the hypothesis more or less probable.
- 366Mr. KEYNES’ system is conceived in terms of macro-economic concepts, inasmuch as its fundamental data consist of complex magnitudes which relate to society as a whole, such as national income, savings, investment, volume of production of producers’ or consumers’ goods, effective aggregate demand, price levels, etc. Its macroscopic nature Mr. KEYNES’ theory has in common with most business-cycle theories. If a theory which aims at representing the economic process as a whole is to be manageable, it cannot avoid using broad averages and aggregates of a collective nature. It is very well to preach a microscopic approach and to urge the investigator to go back to the individual units (households and firms). It is true, of course, that direct and indirect observations of individual behaviour and happenings are the only source of information about the magnitude and behaviour of collective phenomena. But the final statements at which the theory aims (as distinguished from the methods by which they are reached) must practically always run in terms of aggregates and averages.
- 367Mr. KEYNES’ system is conceived in terms of macro-economic concepts, inasmuch as its fundamental data consist of complex magnitudes which relate to society as a whole, such as national income, savings, investment, volume of production of producers’ or consumers’ goods, effective aggregate demand, price levels, etc. Its macroscopic nature Mr. KEYNES’ theory has in common with most business-cycle theories. If a theory which aims at representing the economic process as a whole is to be manageable, it cannot avoid using broad averages and aggregates of a collective nature. It is very well to preach a microscopic approach and to urge the investigator to go back to the individual units (households and firms). It is true, of course, that direct and indirect observations of individual behaviour and happenings are the only source of information about the magnitude and behaviour of collective phenomena. But the final statements at which the theory aims (as distinguished from the methods by which they are reached) must practically always run in terms of aggregates and averages.
- 368Mr. KEYNES’ theory has still another characteristic which distinguishes it from all business-cycle theories: it is essentially static. By a static theory, we mean a theory where all the variables (magnitudes to be explained) relating to a certain point or period of time are explained by data relating to the same point or period of time. Such a theory can never explain a movement in time. It can only answer the question: Given certain data at a certain moment, what will be the result at that moment? True, if the data change in time, then the results will also change. But a change in data cannot be explained. (If it could, then the data would cease to be data and become variables.) They must be given (or assumed) anew for each successive point in time. This method of dealing with economic change is frequently called “comparative statics”.
- 369Mr. KEYNES’ theory has still another characteristic which distinguishes it from all business-cycle theories: it is essentially static. By a static theory, we mean a theory where all the variables (magnitudes to be explained) relating to a certain point or period of time are explained by data relating to the same point or period of time. Such a theory can never explain a movement in time. It can only answer the question: Given certain data at a certain moment, what will be the result at that moment? True, if the data change in time, then the results will also change. But a change in data cannot be explained. (If it could, then the data would cease to be data and become variables.) They must be given (or assumed) anew for each successive point in time. This method of dealing with economic change is frequently called “comparative statics”.
- 370By a dynamic theory, we mean “a theory that explains how one situation grows out of the foregoing. In this type of analysis, we consider not only a set of magnitudes in a given point of time and study the interrelations between them, but we consider the magnitudes of certain variables in different points of time, and we introduce certain equations which embrace at the same time several of these magnitudes belonging to different instants.” We may also say that a theory is dynamic, if a magnitude is explained by another relating to an earlier (or, more generally, to another) point of time. In still other words: if there are lags in the causal nexus. If we say, for instance, that the volume of production (of a particular commodity or of commodities in general) is governed by the relation of cost and prices, we obviously must allow for a certain lag: cost and prices to-day govern production to-morrow. The acceleration principle is a dynamic relationship: investment is explained by a previous change in demand for the product. The “multiplier relationship” may be formulated dynamically, by allowing a time-lag between investment and the resulting increase in consumption demand. (In Mr. KEYNES’ system, it will be recalled, it is a timeless terminological rule; only incidentally are some remarks made about the probable change of the value of the multiplier, or of the marginal propensity to consume, over time.
- 371By a dynamic theory, we mean “a theory that explains how one situation grows out of the foregoing. In this type of analysis, we consider not only a set of magnitudes in a given point of time and study the interrelations between them, but we consider the magnitudes of certain variables in different points of time, and we introduce certain equations which embrace at the same time several of these magnitudes belonging to different instants.” We may also say that a theory is dynamic, if a magnitude is explained by another relating to an earlier (or, more generally, to another) point of time. In still other words: if there are lags in the causal nexus. If we say, for instance, that the volume of production (of a particular commodity or of commodities in general) is governed by the relation of cost and prices, we obviously must allow for a certain lag: cost and prices to-day govern production to-morrow. The acceleration principle is a dynamic relationship: investment is explained by a previous change in demand for the product. The “multiplier relationship” may be formulated dynamically, by allowing a time-lag between investment and the resulting increase in consumption demand. (In Mr. KEYNES’ system, it will be recalled, it is a timeless terminological rule; only incidentally are some remarks made about the probable change of the value of the multiplier, or of the marginal propensity to consume, over time.
- 372Such a dynamic theory is endogenous in character. The determinants at any moment of time cease to be simply assumed. Today’s determinant data are yesterday’s variables (and are thus explained), and to-day’s variables become to-morrow’s data. The successive situations (short-run equilibria) are interconnected like the links of a chain. Hence, in order to explain a movement (cyclical or otherwise), we need not assume a corresponding change in the data; we need be given only the first position or an initial change in data, at the beginning of the process.
- 373The skeleton of Mr. KEYNES’ theory, as it is represented precisely in diagrammatic form by Professor LANGE, is essentially static. There are no time-lags, and all the data and variables relate to the same point of time. There are, however, many allusions to dynamic relationships in incidental remarks and illustrative observations which are thrown out in great number all over the book. Moreover, dynamic theories can be grafted upon (or, as it is more correct to say, may be expressed in terms of) Mr. KEYNES’ system. This has been done, for example, by Mr. HARROD, who introduced the dynamic acceleration principle (and seems to interpret the multiplier dynamically). Another example is Mr. M. KALECKI’S theory, which introduces a lag between investment decisions as determined by the current situation and the actual volume of investment.
- 374The skeleton of Mr. KEYNES’ theory, as it is represented precisely in diagrammatic form by Professor LANGE, is essentially static. There are no time-lags, and all the data and variables relate to the same point of time. There are, however, many allusions to dynamic relationships in incidental remarks and illustrative observations which are thrown out in great number all over the book. Moreover, dynamic theories can be grafted upon (or, as it is more correct to say, may be expressed in terms of) Mr. KEYNES’ system. This has been done, for example, by Mr. HARROD, who introduced the dynamic acceleration principle (and seems to interpret the multiplier dynamically). Another example is Mr. M. KALECKI’S theory, which introduces a lag between investment decisions as determined by the current situation and the actual volume of investment.
- 375The skeleton of Mr. KEYNES’ theory, as it is represented precisely in diagrammatic form by Professor LANGE, is essentially static. There are no time-lags, and all the data and variables relate to the same point of time. There are, however, many allusions to dynamic relationships in incidental remarks and illustrative observations which are thrown out in great number all over the book. Moreover, dynamic theories can be grafted upon (or, as it is more correct to say, may be expressed in terms of) Mr. KEYNES’ system. This has been done, for example, by Mr. HARROD, who introduced the dynamic acceleration principle (and seems to interpret the multiplier dynamically). Another example is Mr. M. KALECKI’S theory, which introduces a lag between investment decisions as determined by the current situation and the actual volume of investment.
- 376The following authors have developed the acceleration principle—Albert AFTALION, BICKERDIKE, Mentor BOUNIATIAN, T. N. CARVER, and MARCO FANNO. In recent years, it has been expounded most fully by J. M. CLARK, SIMON KUZNETS, A. C. PIGOU and R. F. HARROD. W. C. MITCHELL, D. H. ROBERTSON, and A. SPIETHOFF have incorporated it into their account of the cycle as a contributory factor. Mr. HARROD has, without much reference to the previous literature, rechristened the principle as “the Relation”.
- 377There is, however, one feature about Mr. KEYNES’ system which has given the impression to many readers that the General Theory of Employment is a dynamic theory—namely, the fact that, following the lead of Swedish writers such as MYRDAL and LINDAHL, it runs in terms of expectations. Almost every concept is defined in terms of expectations: “aggregate demand function”, “supply function”, “effective demand”, “marginal efficiency of capital”, etc., are defined with the help of such concepts as “the prospective yield of capital”, “proceeds which entrepreneurs expect to receive”, etc. Now, in a sense it is true that the explicit introduction of expectations tends to make a theory truly dynamic. In the sense, namely, that the introduction of expectations into the causal nexus is essentially an incomplete idea which requires, in order to become at all useful, a complement which makes the theory dynamic: if we confine ourselves to saying that it is not actual (current) prices, costs, profits, etc., but expected prices, costs, profits which induce an entrepreneur to produce and to invest, we do not say very much, unless we give some hint as to how these expectations are determined.
- 378A theory which takes the expectations as given at any point of time, and does not say anything on how they grow out of past experience, is of very little value; for such a theory would still be static, and it is almost impossible to determine expectations as such. Only if it is possible to give some hypotheses about how expectations are formed on the basis of past experience (prices, state of demand, costs, profits, etc.) can a really useful and verifiable theory be evolved. And such a theory is evidently dynamic in the sense explained above, for it links the past with the present: past prices, costs and profits via the state of expectation with present production, consumption and investment.
- 379A theory which takes the expectations as given at any point of time, and does not say anything on how they grow out of past experience, is of very little value; for such a theory would still be static, and it is almost impossible to determine expectations as such. Only if it is possible to give some hypotheses about how expectations are formed on the basis of past experience (prices, state of demand, costs, profits, etc.) can a really useful and verifiable theory be evolved. And such a theory is evidently dynamic in the sense explained above, for it links the past with the present: past prices, costs and profits via the state of expectation with present production, consumption and investment.
- 380Professor ROBERTSON’S “period analysis”, on the other hand, is a clear step in the right direction of a truly dynamic analysis, Similarly, a number of Swedish writers, especially Dr. Eric LUNDBERG in his Studies in the Theory of Economic Expansion, have visualised the problem clearly. Dr. LUNDBERG characterises the method as “sequence analysis” and has constructed a number of macroscopic dynamic models—“model sequences” as he calls them.
- 381Professor ROBERTSON’S “period analysis”, on the other hand, is a clear step in the right direction of a truly dynamic analysis, Similarly, a number of Swedish writers, especially Dr. Eric LUNDBERG in his Studies in the Theory of Economic Expansion, have visualised the problem clearly. Dr. LUNDBERG characterises the method as “sequence analysis” and has constructed a number of macroscopic dynamic models—“model sequences” as he calls them.
- 382Dr. LUNDBERG’S models are theoretical—that is to say, the figures are assumed (not found statistically); the relationships postulated, although assumed and selected so as to be not impossible on a priori grounds, are too simple and too few in number to give an adequate picture of the enormous complexity of real life. Professor TINBERGEN, on the other hand, in a number of pioneering studies, has tried to evaluate statistically a great number of dynamic relations for particular countries and to construct concrete models which give at least a rough quantitative approximation of the principal economic magnitudes and of the dynamic laws by which they are interrelated.
- 383Dr. LUNDBERG’S models are theoretical—that is to say, the figures are assumed (not found statistically); the relationships postulated, although assumed and selected so as to be not impossible on a priori grounds, are too simple and too few in number to give an adequate picture of the enormous complexity of real life. Professor TINBERGEN, on the other hand, in a number of pioneering studies, has tried to evaluate statistically a great number of dynamic relations for particular countries and to construct concrete models which give at least a rough quantitative approximation of the principal economic magnitudes and of the dynamic laws by which they are interrelated.
- 384A dynamic theory of the business cycle, if fully elaborated in precise terms, so as to do some justice to the enormous complexity of the real world, requires a highly complicated mathematical technique and presents formidable problems from the purely formal logical point of view.

