
An Austrian Perspective on the History of Economic Thought
11. Mercantilism and freedom in England from the Civil War to 1750
11.1 The Pettyites: Davenant, King, and ‘the law of demand’
11.2 Liberty and property: the Levellers and Locke
11.3 Child, Locke, the rate of interest, and the coinage
11.4 The North brothers, deductions from axioms, and Tory laissez-faire
11.5 The inflationists
11.6 The hard-money response
11.7 Laissez-faire by mid-century: Tucker and Townshend
11.8 Notes
11.1 The Pettyites: Davenant, King and ‘the law of demand’
Jonathan Swift’s A Modest Proposal should have provided the last word on political arithmetic, except that an epilogue has been furnished by the quantophrenic and metromanic folly of modern historians of economic thought, who have resurrected a Baconian or Pettyite ‘quantitative law’ expounded in the 1690s as if it were a veritable marvel of anticipation of modern econometrics.
Charles Davenant (1656–1714), son of a poet laureate and dramatist, was an attorney who spent his life scrambling for the main chance. To supplement his meagre income from law practice, he managed to obtain the appointment of commissioner of excise in 1678. By the mid-1680s, Davenant was making a handsome salary as commissioner and was also an MP. His comfortable and placid existence, however, was grievously disrupted by the Revolution of 1688, which lost Davenant his high post; moreover, substantial loans of his to the Crown of Charles II remained unrepaid.
A Tory confronting a Whig regime, Davenant now began to turn his attention to writing economic tracts on the problems of the day. All his publications centred around special pleading for his own political interests, a quest for subsidy or for resuming his high post in the government. Davenant’s first tract, An Essay upon the Ways and Means of supplying the War was published in 1694, after five years of war with the Dutch, and after the same number of years of Davenant’s trying unsuccessfully to get back his old post as commissioner of excise. The burden of the tract was denouncing the government for financing any part of the war by public debt, and urging instead that it rely almost totally on the excise, coincidentally Davenant’s own area of expertise. After again denouncing the government that stubbornly refused to see his own virtues, Davenant turned to another area of self-interest.
Davenant has been termed inconsistent and confused on the free trade issue, sometimes appearing to favour free trade and other times favouring protection. But these inconsistencies magically clear up if we realize that Davenant, in an attempt to get on the East India Company bandwagon, revived the by now grand seventeenth century tradition of arguing about the rights and wrongs of the East India trade. Davenant unsurprisingly took the standard Munian line of supporting an overall, or general, ‘favourable’ balance of trade, but pointed out the absurdity of trying to balance trade with each country, and defending the East India Company’s deficit with the Far East. Davenant’s pro-East India trade position was expressed in his 1696 tract, Essay on the East India Trade. The following year, Davenant urged the East India Company to send him to India; failing that, Davenant continued to curry favour with the company by publishing two Discourses on the Publick Revenues and on the Trade of England (1697–98), and another Essay upon... the Balance of Trade in 1699, continuing his Munian foreign trade analysis.
By 1698, indeed Charles Davenant’s fortune had changed; he was now a Tory MP and the East India Company agreed to send him to India. From then on, Davenant’s writings were mainly strictly political, and in 1703 he finally achieved his objective of regaining a high government post, inspector-general of exports and imports. Davenant was in and out of trouble, however, his writings changing radically from ‘moderation’ to ‘extremism’ and back with each change of the political winds, or from Tory to Whig, until he ended his career generally scorned and trusted by none, in financial difficulties and living on the largesse of his old friend James Brydges, the Duke of Chandos. All in all, his biographer Professor Waddell does not seem too severe when he concludes that:
Davenant’s career was thus not much of a success. He lacked the force of personality and obvious integrity necessary for the role... he... tried to play – that of a partisan pamphleteer who was yet a man of independent judgment and not a mere hack. He was on the losing side in nearly every controversy he joined.... He proved incapable of managing his own affairs and became a burden on his friends.... He was neither an original thinker, nor a practical man of affairs, but merely a competent publicist. The relationship between his writings and his personal circumstances suggests that his enemies had some excuse for regarding him as a purely self-seeking and mercenary time-server.1
It is intriguing that Davenant, as a devoted follower of political arithmetic, would try to justify his self-seeking wavering by employing political arithmetic as a kind of cost–benefit analysis, in which the statesman, possessing ‘a computing head’, arrives at a balance of advantages, ‘by summing up the difficulties on either side, and by computing upon the whole. In that way, he shall be able to form a sound judgment and to give right advice; and this is what we mean by Political Arithmetic’.2
Davenant would be a forgotten and no-account minor mercantilist writer, except for the extravagant praise lavished by modern quantophrenic historians of thought upon a previously unknown and alleged ‘economic law’ discovered by Davenant and by his quiet political arithmetical and political ally, the accountant Gregory King (1648–1712). This ‘law of demand’ is now hailed as the origin of econometrics, predating Bernoulli’s alleged law of the diminishing utility of money of 1738 (see below). Embarrassing adulation has been heaped upon this absurd ‘law’ by modern economists zealously trying to find prefigurements of econometric ‘science’. There has been much confusion on the precise credit for authorship of this alleged law, how attribution should be shared between King and Davenant, and even, solemnly, whether it should be called the ‘Davenant–King’ or the ‘King–Davenant’ law, as valueless a piece of scholarly disputation as has appeared in many a moon. The law first appeared in Davenant’s Essay upon... the Balance of Trade of 1699, citing an unpublished manuscript by King, the Natural and Political Observations... written in 1696.3 The ‘law’ states baldly, and without evidence, that the following will happen when the supply of the harvest of corn (wheat) is reduced below the usual amount: not simply, as has been known since the scholastics, that a lower supply of a product will tend to raise the price, but that the effect will be a definite quantitative relation, as follows:
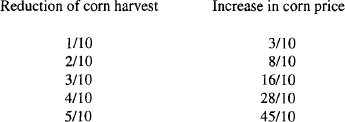
Modern economists have generally, pace Alfred Marshall, grievously misinterpreted this quantitative statement as a ‘demand schedule’, or tabular basis for a demand curve, and as a pioneering attempt to ‘measure’ the elasticity of such a curve. But the grave fallacy here is that this quantitative relation has nothing whatever to do with the consumer demand schedule that plays such a deservedly important part in modern economics. The genuine demand schedule is hypothetical, subjective, and instantaneous: all it says is that at a given moment, at price x, consumers would purchase a certain quantity y of the product. And the point of this schedule is precisely that we don’t know and can’t know this subjective relation, that there is no way to find out, and that the only point of the demand schedule is to show that, at any given time, the demand curve is ‘falling’, that is, as the price falls the quantity demanded increases, and vice versa. Properly, the law is qualitative and never quantitative, and there is never any way to establish such quantities.
What the pro-Davenant ‘law’ economists fail to realize, then, is that even if this Davenant table were based on historical fact, all it would establish is not a demand schedule or curve, but only the factual ‘equilibrium’ points each year, that is, each year’s price and quantity produced. These points have nothing to do with any genuine demand schedule or ‘law of demand’, which is strictly qualitative and subjective to the minds of consumers.
Second, even if these historical data were correct, they would only establish a relation for the particular years and particular markets in question; they would in no sense establish any sort of ‘law’ for the same continuing quantitative relationship between supply and price in any other year or place.
But finally, there is no evidence that this table is based on any factual evidence at all! Thus, despite the solemn repetition of this table from the late nineteenth century onwards, and despite its alleged pioneering of econometric science, this Davenant–King table has no value whatever either as factual data, as statistics, as econometrics, or as economic theory. It is testimony only to the quantophrenic folly of modern economics.4
And yet economists, striving desperately to maintain that the Davenant– King ‘law’ must have clothes, have taken one of two contradictory directions in presuming the importance of the law, and sometimes have taken both stances at once. Thus Jevons (1871), without any evidence at all, simply assumed that the Davenant–King table was ‘accurate’ and pronounced it a scandal that economists and statisticians hadn’t yet matched these numbers in accuracy. On the other hand, William Whewell, an odd combination of expert Cambridge mathematician and arch-empiricist in the philosophy of science and economics had, two decades earlier (1850), sensed that the Davenant table was really the mere working out of a mathematical formula, and yet he still assumed that it must have been based on empirical observations. Similarly, in his recent careful study, Professor Creedy has convincingly shown that the King–Davenant numbers were the working out of the mathematical formula of ‘factoral expansion of a polynomial’, a method first discovered by the English mathematician James Gregory and then used by Isaac Newton for his great work in physics. But, after usefully pointing out how King could have rapidly discovered and used the new Gregory–Newton method Creedy, instead of concluding sensibly that the statistical or econometric soundness of the Davenant–King ‘law’ lies in ruins, blithely proceeds to save the theory by simply asserting that it ‘was quite possible’ that the polynomial formula ‘was fitted to actual observations’. ‘Quite possible’, but there is no evidence whatever, and, since this ‘law’ was never replicated, and was even changed by King, it is far more likely that, enchanted with the new maths as Creedy himself concedes, ‘hypothetical values of coefficients were used with an arbitrarily chosen polynomial in order to generate the basic “data”’; in other words, that King and/or Davenant made it all up, as part of their ‘new science’.5
11.2 Liberty and property: the Levellers and Locke
The turmoil of the English Civil War in the 1640s and 1650s generated political and institutional upheaval, and stimulated radical thinking about politics. Since the Civil War was fought over religion and politics, much of the new thinking was grounded in, or inspired by, religious principles and visions. Thus, as we shall see further in the chapter on ‘The roots of Marxism’ (Chapter 9 in Volume II), millennial communist sects popped up again, for the first time since the Anabaptist frenzy of the early sixteenth century in Germany and Holland. Particularly prominent in the frenzy of the Civil War Left were the Diggers, the Ranters, and the Fifth Monarchists.6
At the opposite pole of new thought generated by the Civil War was the prominence, in the midst of the forces of the mainstream republican Left, of the world’s first self-consciously libertarian mass movement: the Levellers. In a series of notable debates within the Republican Army – notably between the Cromwellians and the Levellers – the Levellers, led by John Lilburne, Richard Overton and William Walwyn, worked out a remarkably consistent libertarian doctrine, upholding the rights of ‘self-ownership’, private property, religious freedom for the individual, and minimal government interference in society. The rights of each individual to his person and property, furthermore, were ‘natural’, that is, they were derived from the nature of man and the universe, and therefore were not dependent on, nor could they be abrogated by, government. And while the economy was scarcely a primary focus of the Levellers, their adherence to a free market economy was a simple derivation from their stress on liberty and the rights of private property.
For a while it seemed that the Levellers would triumph in the Civil War, but Cromwell decided to resolve the army debates by the use of force, and he established his coercive dictatorship and radical puritan theocracy by placing the Leveller leadership in jail. The victory of Cromwell and his Puritans over the Levellers proved fateful for the course of English history. For it meant that ‘republicanism’, in the eyes of the English, would be forever associated with the bloody rule of Cromwell’s saints, the reign of religious fanaticism, and the sacking of the great English cathedrals. Hence the death of Cromwell led swiftly to the restoration of the Stuarts, and the permanent discrediting of the republican cause. It is likely, on the contrary, that a Leveller rule of freedom, religious toleration and minimal government might have proved roughly acceptable to the English people, and might have ensured a far more libertarian English polity than actually evolved after the Restoration and the Whig Settlement.7
Historiographical discussion of the great libertarian political theorist John Locke (1632–1704), who emerged to prominence after the Civil War, and particularly in the 1680s, has been mired in a welter of conflicting interpretations. Was Locke a radically individualistic political thinker or a conservative Protestant scholastic? An individualist or a majoritarian? A pure philosopher or a revolutionary intriguer? A radical harbinger of modernity or one who harked back to the medieval or to classical virtue?
Most of these interpretations are, oddly enough, not really contradictory. By this point, we should realize that the scholastics may have dominated medieval and post-medieval traditions, but that despite this fact, they were pioneers and elaborators of the natural law and natural rights traditions. The pitting of ‘tradition’ vs ‘modernity’ is largely an artificial antithesis. ‘Moderns’ like Locke or perhaps even Hobbes may have been individualists and ‘right-thinkers’, but they were also steeped in scholasticism and natural law. Locke may have been and indeed was an ardent Protestant, but he was also a Protestant scholastic, heavily influenced by the founder of Protestant scholasticism, the Dutchman Hugo Grotius, who in turn was heavily influenced by the late Spanish Catholic scholastics. As we have already seen, such great late sixteenth century Spanish Jesuit scholastics as Suarez and Mariana were contractual natural rights thinkers, with Mariana being positively ‘pre-Lockean’ in his insistence on the right of the people to resume the rights of sovereignty they had previously delegated to the king. While Locke developed libertarian natural rights thought more fully than his predecessors, it was still squarely embedded in the scholastic natural law tradition.8
Neither are John Pocock and his followers convincing in trying to posit an artificial distinction and clash between the libertarian concerns of Locke or his later followers on the one hand, and devotion to ‘classical virtue’ on the other. In this view eighteenth century Lockean libertarians from ‘Cato’ to Jefferson become magically transmuted from radical individualists and free marketeers into nostalgic reactionaries harking back to ancient or renaissance ‘classical virtue’. Followers of such virtue somehow become old-fashioned communitarians rather than modern individualists. And yet, why can’t libertarians and opposers of government intervention also oppose government ‘corruption’ and extravagance? Indeed, the two generally go together. As soon as we realize that, generally, and certainly until Bentham, devotees of liberty, property and free markets have generally been moralists as well as adherents of a free market economy, the Pocockian antitheses begin to fall apart. To seventeenth and eighteenth century libertarians, indeed to libertarians in most times and places, attacks on government intervention and on government moral corruption go happily hand in hand.9
There are still anomalies in John Locke’s career and thought, but they can be cleared up by the explicit discussion and implications of the impressive work by Richard Ashcraft.10 Essentially Ashcraft demonstrates that Locke’s career can be divided into two parts. Locke’s father, a country lawyer and son of minor puritan country gentry, fought in Cromwell’s army and was able to use the political pull of his mentor Colonel Alexander Popham, MP, to get John into the prominent Westminster School. At Westminster, and then at Christ Church, Oxford, Locke obtained a BA and then an MA in 1658, then become a lecturer at the college in Greek and rhetoric in 1662, and became a medical student and then a physician in order to stay at Oxford without having to take holy orders.
Despite or perhaps because of Locke’s puritan background and patronage, he clearly came under the influence of the Baconian scientists at Oxford, notably including Robert Boyle, and hence he tended to adopt the ‘scientific’, empiricist, low-key absolutist viewpoint of his friends and mentors. While at Oxford, Locke and his colleagues enthusiastically welcomed the restoration of Charles II, and indeed the king himself ordered Oxford University to keep Locke as medical student without having to take holy orders. While at Oxford, Locke adopted the empiricist methodology and sensate philosophy of the Baconians, leading to his later Essay Concerning Human Understanding. Moreover, in 1661, Locke, this later champion of religious toleration, wrote two tracts denouncing religious tolerance, and favouring the absolute state enforcing religious orthodoxy. In 1668, Locke was elected to the Royal Society, joining his fellow Baconian scientists.
Something happened to John Locke in the year 1666, however, when he became a physician and in the following year when he became personal secretary, advisor, writer, theoretician, and close friend of the great Lord Ashley (Anthony Ashley Cooper), who in 1672 was named the first Earl Shaftesbury. It was due to Shaftesbury that Locke, from then on, was to plunge into political and economic philosophy, and into public service as well as revolutionary intrigue. Locke adopted from Shaftesbury the entire classical liberal Whig outlook, and it was Shaftesbury who converted Locke into a firm and lifelong champion of religious toleration and into a libertarian exponent of self-ownership, property rights, and a free market economy. It was Shaftesbury who made Locke into a libertarian and who stimulated the development of Locke’s libertarian system.
John Locke, in short, quickly became a Shaftesburyite, and thereby a classical liberal and libertarian. All his life and even after Shaftesbury’s death in 1683, Locke only had words of adulation for his friend and mentor. Locke’s epitaph for Shaftesbury declared that the latter was ‘a vigorous and indefatigable champion of civil and ecclesiastical liberty’. The editor of the definitive edition of Locke’s Two Treatises of Government justly writes that ‘Without Shaftesbury, Locke would not have been Locke at all’. This truth has been hidden all too often by historians who have had an absurdly monastic horror of how political theory and philosophy often develop: in the heat of political and ideological battle. Instead, many felt they had to hide this relationship in order to construct an idealized image of Locke the pure and detached philosopher, separate from the grubby and mundane political concerns of the real world.”11
Professor Ashcraft also shows how Locke and Shaftesbury began to build up, even consciously, a neo-Leveller movement, elaborating doctrines very similar to those of the Levellers. Locke’s entire structure of thought in his Two Treatises of Government, written in 1681–82 as a schema for justifying the forthcoming Whig revolution against the Stuarts, was an elaboration and creative development of Leveller doctrine: the beginnings in self-ownership or self-propriety, the deduced right to property and free exchange, the justification of government as a device to protect such rights, and the right of overturning a government that violates, or becomes destructive of, those ends. One of the former Leveller leaders, Major John Wildman, was even close to the Locke–Shaftesbury set during the 1680s.
The deep affinity between Locke and scholastic thought has been obscured by the undeniable fact that to Locke, Shaftesbury and the Whigs, the real enemy of civil and religious liberty, the great advocate of monarchical absolutism, during the late seventeenth century and into the eighteenth century, was the Catholic Church. For by the mid-seventeenth century, Catholicism, or ‘popery’, was identified not with the natural rights and the checks on royal despotism as of yore, but with the absolutism of Louis XIV of France, the leading absolutist state in Europe, and earlier with absolutist Spain. For the Reformation, after a century, had succeeded in taking the wraps off monarchical tyranny in the Catholic as well as Protestant countries. Ever since the turn of the seventeenth century, indeed, the Catholic Church in France, Jansenist and royalist in spirit, had been more a creature of royal absolutism than a check on its excesses. In fact, by the seventeenth century, the case could be made that the most prosperous country in Europe which was also the freest – in economics, in civil liberties, in a decentralized polity and in abstinence from imperial adventures – was Protestant Holland.12
Thus it was easy for the English Whigs and classical liberals to identify the absolutism, the arbitrary taxes, the controls, and the incessant wars of the Stuarts with the Catholicism towards which the Stuarts were not so secretly moving, as well as with the spectre of Louis XIV, towards whom the Stuarts were moving as well. As a result, the English and American colonial tradition, even the libertarian tradition, became imbued with a fanatical anti-Catholicism; the idea of including evil Catholics in the rubric of religious toleration was rarely entertained.
One common confusion about Locke’s systematic theory of property needs to be cleared up: Locke’s theory of labour. Locke grounded his theory of natural property rights in each individual’s right of self-ownership, of a ‘propriety’ in his own person. What then establishes anyone’s original right of material, or landed or natural resource property, apart from his own person? In Locke’s brilliant and very sensible theory, property is brought out of the commons, or out of non-property, into one’s private ownership, in the same way that a man brings non-used property into use: that is, by ‘mixing his self-owned labour’, his personal energy, with a previously unused and unowned natural resource, thereby bringing that resource into productive use and hence into his private property. Private property of a material resource is established by first use. These two axioms: self-ownership of each person, and the first use, or ‘homesteading’, of natural resources, establishes the ‘naturalness’, the morality, and the property rights underlying the entire free market economy. For if a man justly owns material property he has settled in and worked on, he has the deduced right to exchange those property titles for the property someone else has settled in and worked on with his labour. For if someone owns property, he has a right to exchange it for someone else’s property, or to give that property away to a willing recipient. This chain of deduction establishes the right of free exchange and free contract, and the right of bequest, and hence the entire property rights structure of the market economy.
Many historians, especially Marxists, have taken glee in claiming that John Locke is thereby the founder of the Marxian ‘labour theory of value’ (which Marx in turn acquired from Smith and especially Ricardo). But Locke’s is a labour theory of property, that is, how material property justly comes into ownership by means of labour exertion or ‘mixing’. This theory has absolutely nothing to do with what determines the value or price of goods or services on the market, and therefore has nothing to do with the later ‘labour theory of value’.
11.3 Child, Locke, the rate of interest, and the coinage
One of the most prominent economic writers of the latter half of the seventeenth century in England was the eminent Sir Josiah Child (1630–99). He was a wealthy merchant who was usually affiliated with the powerful East India Company and indeed rose to be its governor, and the central concern in his economic writings was the by now traditional apologetics for the East India interests. That is: no one need worry about balance of trade from one specific country to another; a broader look at a nation’s balance should be taken; and therefore the East India Company’s notorious gold and silver exports to, or deficits with, the Far East are justified if we consider the company’s re-exports to, and hence surpluses with, other countries. Because of this broader emphasis on the overall balance of trade, later economists often associated Child with a free trade, laissez-faire approach.
Unwary historians were also entrapped by many of Child’s fulminations against monopolies and monopolistic privileges granted by the state to cities, guilds or trading companies. Again, they assume that Child was an advocate of laissez-faire; what they overlooked was that Child was always careful to defend, as a special exception, the monopoly granted to the East India Company.13
Child never attained the genuine laissez-faire view that even the overall balance of trade was unimportant; on the contrary, he insisted that gold and silver bullion could only be exported freely if the overall effect of such export would be a net import of specie, in other words, an overall favourable balance of trade.14
Unfortunately, Child’s work was interpreted as solid laissez-faire doctrine in the eighteenth century, and particularly by the mid-eighteenth century devotee of laissez-faire, Viscount de Gournay, who translated Child into French as part of his programme of spreading laissez-faire doctrine in France. As a result, Child’s work achieved undeserving fame in the following century.
One of Josiah Child’s main deviations from free market and laissez-faire doctrine was to agitate for one of the favourite programmes of the mercantilists: to push the legal maximum rate of interest ever lower. Formerly discredited ‘usury laws’ were making a comeback on faulty economic rather than natural law or theological grounds.
From the early decades of the seventeenth century, English mercantilists were bitter at the superior prosperity and economic growth enjoyed by the Dutch. Observing that the rate of interest was lower in Holland than in England, they chose to leap to the causal analysis that the cause of the superior Dutch prosperity was Holland’s low rate of interest, and that therefore it was the task of the English government to force the maximum rate of interest down until the interest rate was lower than in Holland. The first prominent mercantilist tract calling for lowering the interest rate was that of the country gentleman Sir Thomas Culpeper, in his brief Tract Against the High Rate of Usury (1621). Culpeper declared that Dutch prosperity was caused by their low rate of interest; that the English high interest rate crippled trade; and therefore that the government should force maximum interest rates down to outcompete the Dutch. Culpeper’s pamphlet played a role in Parliament’s lowering the maximum usury rate from 10 to 8 per cent. Culpeper’s tract was reprinted several times, and Parliament duly pushed the maximum rate in later years down to 8 and then 6 per cent.
Each time, however, resistance increased, especially as government intervention forced down the maximum rate repeatedly. Finally, in 1668, the mercantilists tried for their most important conquest: a lowering of the maximum interest rate from 6 to 4 per cent, which would presumably result in rates below the Dutch. As a propaganda accompaniment to this bill, Culpeper’s son, Sir Thomas Culpeper, in 1668 reprinted his father’s tract, along with one of his own, whose title says it all: A Discourse showing the many Advantages which will accrue to this Kingdom by the Abatement of Usury together with the Absolute Necessity of Reducing Interest of Money to the lowest Rate it bears in other Countreys.
Culpeper Senior’s pamphlet was published along with the influential contribution by the already eminent merchant and man of affairs, Josiah Child, in his first pamphlet, Brief Observations concerning trade, and interest of money. Child was a prominent member of the king’s council of trade, established in 1668 to advise him on economic matters. Child treated lowering the maximum rate of interest to 4 per cent as virtually a panacea for all economic ills. A lower rate of interest would vivify trade, and raise the price of land; it would even cure drunkenness.
Josiah Child’s pamphlet and his testimony before Parliament were centrepieces of the debate swirling around the proposal. Child’s critics pointed out effectively that low interest in a country is the effect of plentiful savings and of prosperity, and not their cause. Thus, Edward Waller, during the House of Commons debate, pointed out that ‘it is with money as it is with other commodities, when they are most plentiful then they are cheapest, so make money [savings] plentiful and the interest will be low’. Colonel Silius Titus pressed on to demonstrate that, since low interest is the consequence and not the cause of wealth, any maximum usury law would be counterproductive: for by outlawing currently legal loans, ‘its effect would be to make usurers call in their loans. Traders would be ruined, and mortgages foreclosed; gentlemen who needed to borrow would be forced to break the law....’15
Child feebly replied to his critics that usurers would never not lend their money, that they were forced to take the legal maximum or lump it. On the idea that low interest was an effect not a cause, Child merely recited the previous times that English government had forced interest lower, from 10 to 8 to 6 per cent. Why not then a step further? Child, of course, did not deign to take the scenario further and ask why the state did not have the power to force the interest rate down to zero.
Child’s critics raised another telling point: how is it that the Dutch were able to get their interest rates low purely by economic means; how come the Dutch did not need a usury statute? Child’s absurd rejoinder was that the Dutch would have pushed their interest rate down by statute if their market rate had not fallen low by itself.
It should be noted that this low interest deviation from laissez-faire accorded with Josiah Child’s personal economic interest. As a leading East India merchant, Child and his colleagues were great borrowers not lenders, and so were interested in cheap credit. Even more revealing was Child’s reply to the charge of the author of Interest of Money Mistaken that Child was trying to ‘engross all trade into the hands of a few rich merchants who have money enough of their own to trade with, to the excluding of all young men that want it’. Child replied to that shrewd thrust that, on the contrary, his East India Company was not in need of a low rate since it could borrow as much money as it pleased at 4 per cent. But that of course is precisely the point. Sir Josiah Child and his ilk were eager to push down the rate of interest below the free market level in order to create a shortage of credit, and thereby to ration credit to the prime borrowers – to large firms who could afford to pay 4 per cent or less and away from more speculative borrowers. It was precisely because Child knew full well that a forced lowering of interest rates would indeed ‘engross all trade into the hands of a few rich merchants’ that Child and his colleagues were so eager to put this mercantilist measure into effect.16
When the House of Lords’ committee held hearings on the interest-lowering bill during 1668–69, it decided to hold testimony from members of the king’s council of trade, of whom Josiah Child was a central figure. But another important figure was a very different member of the council of trade, and also a member of the Lords’ committee, the great Lord Ashley, John Locke’s new and powerful patron. As a classical liberal, Ashley opposed the bill, and at his behest, Locke wrote his first work on economic matters, the influential though as yet unpublished manuscript, ‘Some of the Consequences that are like to follow upon Lessening of Interest to Four Percent’ (1668). Locke made clear in this early work his profound insight, as well as thoroughgoing commitment, to a free market economy, as well as to his later structure of property rights theory.
Locke displayed straightaway his skill at polemics; the essay was basically a critique of Child’s influential work. First, Locke cut through the holistic rhetoric; of course, he pointed out, the borrowing merchant will be happy to pay only 4 per cent interest; but this gain to the borrower is not a gain for the national or general good, since the lender loses by the same amount. Not only would a forced lowering of interest be at best redistributive, but, Locke added, the measure would restrict the supply of savings and credit, thereby making the economy worse off. It would be better, he concluded, if the legal rate of interest were set at the ‘natural rate’, that is the free market rate ‘which the present scarcity [of funds] makes it naturally at...’. In short, the best interest rate is the free market, or the ‘natural’ interest rate, set by the workings of free man under natural law, i.e. the rate determined by the supply of and demand for money loans at any given time.
Whether or not Locke or Ashley proved decisive, the House of Lords finally killed the 4 per cent bill in 1669. Three years later, Ashley became chancellor of the Exchequer as Earl Shaftesbury, and the following year Locke became secretary to the council for trade and plantations, which replaced the old council of trade. At the end of 1674, however, Shaftesbury was fired, the council of trade and plantations was disbanded, and Locke followed his mentor into political opposition, revolutionary intrigues, and exile in Holland.
John Locke finally returned to London with the overthrow of the Stuarts and the Revolution of 1688, returning in triumph on the same ship as Queen Mary. Locke returned to England to find the old East India crowd up to their old tricks. England was in dire financial straits, Charles II having ruined public credit with his Stop of the Exchequer, and the East India people had once again introduced a bill in 1690 for the compulsory lowering of interest to 4 per cent. At the same time, Sir Josiah Child was brought back to expand his pamphlet into a Discourse About Trade (1690), an anonymous book reprinted three years later as A New Discourse of Trade, with Child’s name blazoned on the title page. It was the New Discourse that was to make such an excessive impression on eighteenth century thinkers. In addition to the renewed arguments for lower interest, the Discourse and the New Discourse added more apologetics for the East India line on trade and on monopolies.
In response, John Locke’s new political patron, now that Shaftesbury had died, Sir John Somers, MP, apparently asked Locke to expand his 1668 paper to refute Child’s and other proponents of the 4 per cent bill. Locke responded the following year with his expanded book, Some Considerations of the Consequences of the Lowering of Interest and Raising the Value of Money (1692) which brought Locke’s previously unpublished arguments into public debate. Locke’s work may have been influential in the 4 per cent bill once again being killed in the House of Lords.
The latter part of Locke’s Considerations was devoted to the great recoinage controversy, into which England had been plunged since 1690. In that year, England’s basic money stock of silver coins had deteriorated so far, due to erosion and coin-clipping, and the contrast of these inferior ‘hammered’ coins to the newer, uneroded and unclipped ‘milled’ coins was so great, that Gresham’s law began to operate intensely. People either circulated the overvalued eroded coins and hoarded the better ones, or else passed the poor coins at their lower weight rather than at their face value. By 1690 the older hammered coins had lost approximately one-third of their worth compared to their face value.
It was increasingly clear that the Mint had to offer recoinage into the new superior coins. But at what rate? Mercantilists, who tended to be inflationist, clamoured for debasement, that is, recoinage at the lighter weight, devaluating silver coin and increasing the supply of money. In the meanwhile, the monetary problem was aggravated by a burst of bank credit inflation created by the new Bank of England, founded in 1694 to inflate the money supply and finance the government’s deficit. As the coinage problem came to a head in that same year, William Lowndes (1652–1724), secretary of the treasury and the government’s main monetary expert, issued a ‘Report on the Amendment of Silver Coin’ in 1695 calling for accepting the extant debasement, and for officially debasing the coinage by 25 per cent, lightening the currency name by a 25 per cent lower weight of silver. In his Considerations, Locke had denounced debasement as deceitful and illusionist: what determined the real value of a coin, he declared, was the amount of silver in the coin, and not the name granted to it by the authorities. Debasement, Locke warned in his magnificently hard-money discussion, is illusory and inflationist: if coins, for example, are devalued by one-twentieth, ‘when men go to market to buy any other commodities with their new, but lighter money, they will find 20s of their new money will buy no more than 19 would before’. Debasement merely dilutes the real value, the purchasing power, of each currency unit.
Threatened by the Lowndes report, Locke’s patron John Somers, who had been made Lord Keeper of the Great Seal in a new Whig ministry in 1694, asked Locke to rebut Lowndes’s position before the Privy Council. Locke published his rebuttal later in the year 1695, Further Considerations Concerning Raising the Value of Money. This publication was so well received that it went into three editions within a year. Locke superbly put his finger on the supposed function of the Mint: to maintain the currency as purely a definition, or standard of weight of silver; any debasement, any change of standards, would be as arbitrary, fraudulent, and unjust as the government’s changing the definition of a foot or a yard. Locke put it dramatically: ‘one may as rationally hope to lengthen a foot by dividing it into fifteen parts instead of twelve, and calling them inches...’.
Furthermore, government, the supported guarantor of contracts, thereby leads in contract-breaking:
The reason why it should not be changed is this: because the public authority is guarantee for the performance of all legal contracts. But men are absolved from the performance of their legal contracts, if the quantity of silver under settled and legal denominations be altered... the landlord here and creditor are each defrauded of twenty percent of what they contracted for and is their due...17
One of Locke’s opponents both on coinage and on interest was the prominent builder, fire insurance magnate and land bank projector, Nicholas Barbon (1637–98). Barbon, son of the fanatic London Anabaptist preacher and leather merchant and MP Praisegod Barbon,18 studied medicine and became an MD in Holland, moving to London and going into business in the early 1660s. In the same year as Child’s Discourse About Trade, Barbon, who had just been elected to Parliament, published the similarly titled Discourse of Trade (1690), again timed to push for the 4 per cent interest bill in Parliament. An inveterate debtor and projector, Barbon of course would have liked to push down his interest costs.
In 1696, Barbon returned to the lists in a bitter attack on Locke’s Further Considerations on the coinage. Arguing against Locke’s market commodity, or ‘metallist’, view of money, Barbon, urging devaluation of silver, countered with the nominalist and statist view that money is not the market commodity but whatever government says it is. Wrote Barbon: ‘Money is the instrument and measure of commerce and not silver. It is the instrument of commerce from the authority of that government where it is coined...’19
Fortunately, Locke’s view triumphed, and the recoinage was decided and carried out in 1696 on Lockean lines: the integrity of the weight of the silver denomination of currency was preserved. In the same year, Locke became the dominant commissioner of the newly constituted board of trade. Locke was appointed by his champion Sir John Somers who had become chief minister from 1697 to 1700. When the Somers regime fell in 1700, Locke was ousted from the board of trade, to retire until his death four years later. The Lockean recoinage was assisted by Locke’s old friend, the great physicist Sir Isaac Newton (1642–1727) who, while still a professor of mathematics at Cambridge from 1669 on, also became warden of the Mint in 1696, and rose to master of the Mint three years later, continuing in that post until his death in 1727. Newton agreed with Locke’s hard-money views of recoinage.
Barbon and Locke set the trend for two contrasting strands in eighteenth century monetary thought: Locke, the Protestant scholastic, was essentially in the hard-money, metallist, anti-inflationist tradition of the scholastics; Barbon, on the other hand, helped set the tone for the inflationist schemers and projectors of the next century.20
11.4 The North brothers, deductions from axioms, and Tory laissez-faire
Weighing in on the side of John Locke, not only on interest rates but also in a general and comprehensive vision of economic laissez-faire that even surpassed Locke, were two brothers, Dudley and Roger North, who came from a distinguished Tory family. Here was a fascinating convergence of views of a radical Whig, and high Tories and zealous subjects of Charles and James II. This juncture presaged a later meeting of minds of ‘extreme Left’ and ‘extreme Right’ during the eighteenth century, when the imperialist–Whig–mercantilist one-party Establishment, from 1715 to the 1750s, was opposed on the Left by radical libertarian Commonwealthmen and on the Right by the anti-imperialist, Catholic or proto-Catholic opposition, all agreeing on denunciations of the mercantilistic, high tax, high public debt, central banking state.21
Dudley and Roger North were sons of the fourth Baron North. Showing little aptitude for schooling, Dudley (1641–91), went to Turkey and became a prominent trader, as well as a director of both the Levant Company, which had been granted a monopoly of English trade with the Middle East, and the African Company, which enjoyed a monopoly of trade with that continent. Dudley North returned to London from Turkey in 1681, just in time to aid King Charles and his elder brother, Francis, Lord Guilford (1637–85), in the patriotic cause of trying to indict John Locke’s patron, Lord Shaftesbury, on the charge of treason. Francis, a distinguished jurist, had risen swiftly from solicitor-general to attorney-general, to Lord Chief Justice of the Common Pleas, and finally, in 1682 at the age of 45, to Lord Keeper of the Great Seal, the highest law office in England. Indictments for treason had to be handed down by grand juries appointed by sheriffs of London, and so Dudley North, in a famous and irregular election, ran for and was elected sheriff, after which he and his juries became scourges of the Whig party.
At the end of the year, Dudley North was knighted by the king for his services, and soon rose in appointive office, becoming commissioner of the customs, MP and manager for King James II of all revenue matters in Parliament.
Toward the end of his brief but distinguished term in government service, Sir Dudley was inspired to think deeply about the two main monetary and financial questions agitating Parliament: the 1690 law to push down the rate of interest, and the recoinage question. Dudley wrote two Discourses upon Trade in 1691, one on interest and one on coinage, along with a postscript, that was scheduled for publication as a pamphlet when Dudley North died unexpectedly on December 31. His younger brother Roger (1653–1734), who was helping Dudley edit the booklet, then revised the draft, added a preface, and published it anonymously in early 1692. Despite the booklet’s brilliance, and its systematic devotion to laissez-faire and hard-money views, the tract sank without a trace, and was not at all influential in the development of eighteenth century economic thought or in monetary or financial policy.
Roger North was not only the youngest of the brothers, he outlived them all by decades. Himself a queen’s attorney-general, he spent much of his life defending his brothers’ reputations. He wrote voluminously in his lifetime on music, accounting, law, the English constitution, and on numerous philosophic and scientific subjects, but natural reticence led him to keep all these writings unpublished. A decade after Roger’s death, his biographies, or Lives, of three of his eminent brothers were published, in two volumes, in 1742 and 1744.22
Even the publication of these two well-written volumes, however, made no dent in the history of economic thought until resurrected and praised by James Mill and by John Ramsay McCulloch in the early nineteenth century.23
Roger North, who in his preface explained the groundwork and methodology of his brother and made his conclusions more consistent, pointed out the innovation in Dudley’s method of economic analysis. For Dudley pioneered, at least in the history of English thought, the method which would later be adopted by Cantillon and Say and Senior, and which Ludwig von Mises would, in the twentieth century, call ‘praxeology’. Praxeology is economic theory resting on a few broad, self-evident axioms grounded in apprehension of reality, then logically deducing the implications of these emphatically true axioms. But if A implies B, C, etc., and A is definitely true, the deductions can be accepted as truths as well.
Roger wrote of Dudley’s method in his preface: ‘I find trade here treated at another rate than usually has been; I mean philosophically; for... he begins at the quick, from principles indisputably true....24 The older method of reasoning, Roger North added, ‘dealt in abstracts more than truths’, in ‘forming hypotheses to fit abundance of precarious and insensible principles’. In contrast, the new method, which North attributed to Descartes, builds knowledge ‘upon clear and evident truths’.
In addressing trade and its problems, Dudley North began in his first discourse by setting forth the clear and simple general axiom or principle: ‘Trade is nothing else but a commutation of superfluities’. In other words, as Buridan and the scholastics had emphasized but the world had forgotten: men only ‘commute’ or exchange goods or services because each benefits more from the good he receives than from the good he gives up in exchange (his ‘superfluity’). Trade, therefore, whether intranational or international, benefits both parties; trade is not a Montaigne–mercantilist form of warfare where one party or nation exploits, or benefits at the expense of the other trader. Wealth and riches, then, are the goods that people are able to produce and accumulate, and not the money, the gold or silver, that enables them to buy those goods. Dudley North concludes that ‘he who is most diligent, and raises most fruits or makes most of manufactory, will abound most in what others make or raise, and consequently be free from want and enjoy most conveniences, which is truly to be rich, although there were no such thing as gold, silver or the like...’.
There is no magic, then, to gold or silver; they are simply commodities selected by the market for their special qualities to be monies; as Dudley North says, gold and silver, in contrast to other market metals, are ‘by nature very fine, and more scarce than others’, and ‘imperishable, as well as convenient for easy storage...’.
Proceeding from there, North rediscovers the scholastic analysis of money. If gold and silver are commodities, their value is determined, as are all other commodities on the market, by supply and demand.
Having laid the groundwork in systematic and general analysis, Dudley North proceeds to the vexed question of the rate of interest. In the market, North points out, some people, in consequence of hard work and judgement, are able to accumulate property. If the property is accumulated in the form of land, the landowners will rent out some of the land to those who wish to cultivate it. Similarly, those who accumulate property in terms of money will ‘rent out’ their money, charging a rate of interest. And just as the rental price of land on the market will be determined by the supply and demand of land, so the interest rate – the price of loans – will be determined by the supply and demand for credit.
Since interest is a market price, government control will have consequences as injurious as the control of any price. Interest is low because the supply of capital is high; low interest itself does not create abundance of capital. As Letwin paraphrases North: ‘Nothing can lower interest rates except an increased supply of capital and as no law can by fiat increase the community’s supply of capital, the proposed law is futile and injurious’.25 Furthermore, North pointed out: usury laws will reduce the supply of savings and capital and thereby raise instead of lower the market rate of interest; and the quantity of trade will diminish. Moreover, intervention to reduce interest rates is unjust, because all prices should be treated alike, and be equally free.
In his discourse on coinage, North did not really deal with the recoinage question, but he anticipated Smith, Ricardo and the classical economists in his keen and principled hard-money analysis. Everyone cries about a ‘shortage of money’, North noted, but what they really want is more goods, or, in the case of merchants, what they really mean is that the prices for their goods are not satisfactory. Analysing the components of the demand for money and its supply, North traced transactions and emergency demands, as well the different aspects of money supply. Unfortunately, he faltered when discussing how much money a nation really needed, failing to realize that any supply on the market is optimal; he believed that an increase in trade required an increase in the supply of money, not understanding that an increased demand for money could simply raise the market value of money (i.e. lowering prices), thereby increasing the value of each unit of currency.
Despite this failure, however, North ended up in the right laissez-faire place, for he pioneered breaking down the supply of money into coin and bullion. He demonstrated that coin, being more suitable for exchange, would tend to command a market premium over bullion. However, the coin premium is regulated by the respective supplies and demands for coin and bullion. Thus, if there is an increase in the stock of coin, the premium over bullion would fall, and coin would tend to be melted down into bullion. If, on the other hand, there is a shortage of coin, the coin premium would rise, and more people would mint bullion into coin. In this way, coin and bullion would tend to be kept in equilibrium. North likened the process to two ‘buckets’: ‘Thus the buckets work alternately; when money is scarce, bullion is coined; when bullion is scarce money is melted’.
So although Dudley North never reached the point of saying that the supply of money, compared to trade, is always optimal, he arrived at a similar laissez-faire, or market-equilibrating, conclusion by saying that no one has to worry about the supply of coin, which will always be kept optimal on the market.
As a result of his systematic, praxeological analysis, Dudley North arrived at firm, principled laissez-faire conclusions across the board. He opposed any usury laws: ‘It will be found best for the nation to leave the borrower and the lender to make their own bargains’. He opposed any sumptuary laws; he denounced laws trying to keep gold and silver inside a country as doomed to failure. Government laws and decrees could only diminish, and never promote human energy, thrift and ingenuity.
But it was Dudley’s brother Roger who took the final step, not only in explaining his brother’s methodology, but also in expounding consistent laissez-faire conclusions. Attacking government intervention across the board, Roger North declared:
There can be no trade unprofitable to the public, for if it prove so, men leave off; and wherever the trades thrive, the public, of which they are part, thrives also. No law can set prices in trade, the rates of which must and will make themselves. But when such laws do happen to lay any hold, it is so much impediment to trade... All favour to one trade or interest against another is an abuse...
Therefore, concluded Roger, ‘Laws to hamper trade, whether foreign or domestic, relating to money or other merchandises, are not the ingredients to make a people rich...’
What can government do for a prosperous economy? ‘If peace be procured, easy justice maintained, the navigation not clogged, the industrious encouraged...’ in short, wrote North: ‘It is peace, industry and freedom that brings trade and wealth, and nothing else’.26
11.5 The inflationists
It is not surprising that mercantilists, with their concentration on greater revenues and power to the state, should fasten on inflationist schemes of creating bank paper and credit, as well as government paper money. Such proposals and schemes, however, had to wait for the discovery of printing in the fifteenth century, for the development of bank paper and fractional reserves in sixteenth century Italy, and finally, for the invention of government paper money and central banking, both dubious innovations of Britain in the 1690s.
The first English inflationist was William Potter, whose most famous tract was The Key of Wealth (1650). It was Potter whose theories and proposed schemes set the stage for more famous inflationist followers, such as the Scotsman John Law. Potter, who worked in the government land office, began with the generally agreed axiom that a greater amount of money is beneficial to society. But with impeccable logic, Potter asked: if more money is good, why shouldn’t a perpetual and greater increase of money be even better? Why indeed? Why not an increasing supply of money leading to infinity?
Potter offered a plethora of money-creating schemes, in which paper money would be secured, not by specie, which is inconveniently scarce, but by the ‘nation’s land’. More relevantly, of course, paper notes can actually be redeemed in physical gold or silver coin, whereas redemption of notes ‘in land’ would prove a chimera. How are you supposed to carry around a few acres of land with you to make exchanges? But that of course is the idea of a ‘land bank’: money seemingly and in the eyes of the deluded public backed by the land of the nation, but actually not backed at all.
William Potter saw other wonders emerging from a land bank. Thus, increasing the money supply would increase land values, and thereby increase the ‘value of the backing’ of the money: a sort of magical perpetual motion machine! Actually, of course, the increased land values simply reflect the increasing prices and values caused by the manufacture of more money.
Since Potter was anxious to inflate money and land values, he was almost frantically opposed to ‘hoarding’, since he realized that if the new money were ‘hoarded’, that is piled up in cash balances and not spent, the supposed benefits of inflation would not accrue. Indeed, one reason Potter greatly preferred paper money to specie is that paper is far less likely to be ‘hoarded’; this means, of course, that paper money is far more likely to depreciate sharply in value as people try to get rid of it rather than add to their cash holdings.
William Potter, however, was cagey about prices rising as a result of his proposed monetary inflation. He believed, instead, that the increased money supply would greatly expand the ‘volume of trade’ and therefore the amount of production of goods, and that wealth would therefore accumulate. Potter preferred to believe that all the increased money supply would be absorbed in increased production, so that prices would not rise at all; but even if prices rose, everyone would be better off. Rising prices, of course, is the Achilles heel of inflationists’ schemes, so that all of them deprecate the extent of subsequent price inflation and currency depreciation. They did not recognize, of course, that the ‘volume of trade’ may increase in money terms, but that this gain, like the alleged rise in land values, would simply reflect the increase in all monetary terms and values as more money supply is created and spreads throughout the system.
The argument of the alleged increase of trade and production largely rested on a flimsy analogy to the physical sciences. The Englishman William Harvey had only recently, in 1628, discovered the circulation of the blood within the human body. And Potter launched the very popular analogy between blood in the human body and money in the body economic. Just as people depend on the circulation of their blood, so the economy needs the circulation of money. But the inflationist notion of the more money the better can scarcely be supported by this feeble analogy; after all, who advocates the more blood the better in the human body, or the faster the circulation the better?27
In his bold moments, William Potter actually maintained that monetary inflation would cause prices to fall(!). Trade would be vivified and production would increase so greatly that supply would rise, and prices would fall.
William Potter, however, proved to be only preparation for the locus classicus of inflationism, the prince of proto-Keynesian money cranks, both theorist and activist, John Law of Lauriston (1671–1729). Son of James Law, a wealthy Scottish goldsmith and banker, John was born and grew up in Edinburgh, proceeding to squander his father’s substantial inheritance on gambling and fast living. Convicted of killing a love rival in a duel in London in 1694, Law bribed his way out of prison and escaped to the Continent. After a decade in Europe pondering monetary problems, Law returned in 1703 to Scotland, where he was not subject to arrest. There, Law concentrated on developing and publishing his monetary theory cum scheme, which he presented to the Scottish Parliament in 1705, publishing the memorandum the same year in his famous or infamous tract, Money and Trade Considered, with a Proposal for Supplying the Nation with Money (Edinburgh, 1705). The Scottish Parliament considered but turned down his scheme; the following year, the advent of the union of Scotland with England forced Law to flee to the Continent once more, since he was still wanted by English law under the old murder charge.
Karl Marx, in a sense, should have been proud of the way John Law ‘unified theory and practice’ in his proposal. On the one hand, Law was the theorist, arguing for a central land bank to issue inconvertible paper money, or rather, paper money ‘backed’ mystically by the land of the nation. As a crucial part of his proposal, the grateful nation – in this case Scotland – was supposed to appoint Law himself, the expert and theoretician, in charge of putting this inflationist central bank scheme into effect.
John Law, as his subtitle states, proposed to ‘supply the nation’ with a sufficiency of money. The increased money was supposed to vivify trade, increase employment and production – the ‘employment’ motif providing a nice proto-Keynesian touch. Law stressed, in opposition to the scholastic hard-money tradition, that money is a mere government creation, that it has no intrinsic value as a metal. Its only function is to be a medium of exchange, and not any store of value for the future.
Even more than William Potter, John Law assured the nation that the increased money supply and bank credit would not raise prices, especially under Law’s own wise aegis. On the contrary, Law anticipated Irving Fisher and the monetarists by assuring that his paper money inflation would lead to ‘stability of value’, presumably stability of the price of labour, or the purchasing power of money.
Law also anticipated Adam Smith in the latter part of the eighteenth century in his fallacious justification for fractional-reserve banking that it would provide a costless ‘highway in the air’ – furnishing a money supply without spending resources on the mining of gold or silver. In the same way, of course, any expenditure of resource can be considered a ‘waste’ if we supply our own assumptions that are not held by people on the free market. Thus, as Professor Walter Block has pointed out, if there were no crime, all expenditure on locks, fences, guards, alarm systems, etc. could be denounced as ‘wasted resources’ by external observers criticizing these expenditures. Similarly, if there were no such thing as governmental inflation, market expenditure on gold or silver could be considered ‘wasteful’ by observers.
If domestic price rises constitute the Achilles heel of monetary inflation, another worry has been the outflow of gold and silver from the country, in short, an ‘unfavourable balance of trade’ or of ‘payment’. But John Law dismissed this problem too. On the contrary, he declared that an increase in the money supply would expand employment and output and ‘therefore’ increase exports, thus causing a favourable balance of payment, with gold and silver flowing into the country. Note that there is no analysis of why an increase in the money supply should increase output or employment, let alone drag exports along with it in this seemingly universal expansion.
Interestingly enough, one of Law’s talking points about the need for more money was, as in the case of low interest, based on a striking misinterpretation of the reasons for the prosperity of the Dutch, whom all other nations envied in the seventeenth century. We have seen that everyone saw that the Dutch had low interest rates, leading English mercantilists to put the cart before the horse and attribute Dutch prosperity to low interest rates, instead of realizing that high savings and higher standards of living had brought about these low interest rates. Hence the mercantilists suggested that England force the maximum usury rate still lower.
Similarly, John Law saw that prosperous Holland enjoyed a plenty of metallic money; he attributed the prosperity to the abundance of money, and proposed to supply paper money instead. Again, he overlooked the point that it was Dutch property and high production and export that brought a plenitude of coin into the country. The export surplus and abundant coin was a reflection of Dutch prosperity, not its cause.28
Not that John Law neglected the low interest argument for Dutch prosperity. But instead of direct usury laws, Law proposed to arrive at low interest rates in what would become the standard inflationist manner: expanding bank credit and bank money and thereby pushing down the rate of interest. Indeed, Law worked out a proto-Keynesian mechanism: increasing the quantity of money would lower interest rates, thereby expanding investment and capital accumulation and assuring general prosperity.
To Law, as to Potter before him and Keynes after him, the main enemy of his scheme was the menace of ‘hoarding’, a practice which would defeat the purpose of greater spending; instead, lower spending would diminish trade and create unemployment. As in the case of the late nineteenth century German money crank Silvio Gesell, Law proposed a statute that would prohibit the hoarding of money.29
It took John Law another decade to find a ruler of a country gullible enough to fall for his scheme. Law found his ‘mark’ in the regent of France, a country that had been thrown into confusion and turmoil upon the death of its seemingly eternal ruler, Louis XIV, in 1715. The regent, the duke of Orleans, set Law up as head of the Banque Générale in 1716, a central bank with a grant of the monopoly of the issue of bank notes in France. Soon the banque became the Banque Royale. Originally, banque notes were receivable in French taxes and were redeemable in silver; soon, however, silver redeemability was ended. Quickly, by 1717, John Law had all monetary and financial power in the realm placed into his hands. To his old scheme he added the financing of the massive government debt. He was made the head of the new Mississippi Company, as well as director-general of French finances; the notes of the Mississippi Company were allegedly ‘backed’ by the vast, undeveloped land which the French government owned in the Louisiana territory in North America. Law’s bank created the notorious hyperinflationary ‘Mississippi bubble’; notes, bank credit, prices and monetary values skyrocketed from 1717 to 1720. One aristocratic observer in Paris noted that for the first time the world ‘millionaire’ had become prevalent, as suddenly many people seemed to possess millions. Finally, in 1720, the bubble collapsed, Law ended a pauper heavily in debt, and he was forced once again to flee the country. As before, he roamed Europe, making a precarious living as a gambler, and trying to find another country that would adopt his scheme. He died in 1729, in Naples, trying to persuade the Neapolitan government to make him its inflationary central banker.30
The cataclysm of John Law’s experiment and his Mississippi bubble provided a warning lesson to all reflective writers and theorists on money throughout the eighteenth century. As we shall see below, hard-money doctrines prevailed easily throughout the century, from Law’s former partner and outwitter Richard Cantillon down to the founding fathers of the American Republic. But there were some who refused to learn any lessons from the Law failure, and whose outlook was heavily influenced by John Law.31
Perhaps the most prominent of the post-Law inflationists in the eighteenth century was the eminent Anglo-Irish idealist philosopher, Bishop George Berkeley (1685–1753). Berkeley studied at Trinity College, Dublin, the intellectual centre of the Anglo-Irish Establishment, and his great philosophical works were all written in his 20s, while he was a fellow at Trinity. Berkeley then spent several years in the late 1720s vainly trying to establish a Christian college in Newport, Rhode Island. After that, Berkeley was appointed dean of Derry and then bishop of Cloyne.
Berkeley’s major pronouncements on economic questions came in his pamphlet, The Querist (1735–37), published in three instalments. The Querist was highly influential, ten editions being published in Berkeley’s lifetime. It was written solely as a series of 900 loaded questions, by which Berkeley hoped to influence public opinion through sheer rhetoric without having to engage in reasoning. Berkeley’s monetary views were heavily influenced by John Law. A typical example of one of Berkeley’s loaded queries is ‘whether the public is not more benefited by a shilling that circulates than a pound that lies dead?’ Money, for Berkeley, was a mere ticket, and the centrepiece of The Querist was the advocation of a Law-type central bank that would expand money and credit, lower interest rates (as Berkeley put it, ‘put an end to usury’), and expand employment and prosperity.
Berkeley was shrewd enough to recognize that he had to answer objections based on John Law’s egregious flop, and so he hastened to put some distance between his own schemes and the ‘madness of France’. Like Law before him, Berkeley promised that his proposed bank notes would only be injected into the economy ‘by slow degrees’, and that he or his surrogates would take pains to keep the expansion of bank credit ‘proportional’ to the ‘multiplication of trade and business’. In that way, prices would supposedly not rise. But of course Berkeley embodied the usual inflationist failure to see that ‘the multiplication of trade and business’ in money terms would precisely be the result of the monetary inflation and the consequent inflation of all prices and monetary values. (Berkeley’s manipulative query on this theme is: ‘Whether therefore bank bills should at any time be multiplied, but as trade and business were also multiplied?’)
11.6 The hard-money response
The bulk of the eighteenth century response to the doctrines and failures of John Law, however, was understandably to return to and redouble devotion to the original continental tradition of hard money, a tradition now challenged by the new institutions of central banking and fractional-reserve banking. One of the earliest and most brilliant responses, which cannot be limited to the term ‘hard money’, was that of Law’s former partner and sceptic in the Mississippi bubble, Richard Cantillon, who virtually founded modern economics in his remarkable Essay written about 1730. (On Cantillon, see Chapter 12.)
The most immediate hard-money reaction to Law in England was also one of the most remarkable. Isaac Gervaise (d. 1739) was born in Paris of a French Protestant father who owned a firm manufacturing and trading in silk. Gervaise senior moved to London, where his son Isaac was employed in the family firm. In 1720, Gervaise published a brief but extraordinary pamphlet of less than 30 pages, The System or Theory of the Trade of the World.32 In the course of attacking Law’s doctrine of bank credit and monetary expansion, Gervaise arrived, before Cantillon and Hume, at the process towards international monetary equilibrium, or the specie-flow-price ‘mechanism’. Without artificial bank credit expansion, Gervaise pointed out, the supply of money in each country would tend to be proportionate to its production or volume of trade. Each nation’s consumption and production, and its imports and exports, would tend to be in balance. If this equilibrium should be disturbed, and, for example, ‘excessive’ gold or silver flow into a particular country, then this excess would be spent on imports, the balance of trade would tilt and imports exceed exports, and this excess would have to be paid for by an outflow of specie. This outflow, in turn, would reduce the excess of money and return the country to a monetary and foreign trade balance.
But, Gervaise charged, schemes such as John Law’s upset this balance: bank credit, serving as substitute money, artificially and unnaturally increases the money supply, expanding consumption including imports, raising domestic prices and lowering exports, so that the increased bank credit will cause an outflow of specie. The artificial credit can bring no lasting gain. There is also a strong hint in Gervaise that the credit expansion will only manage to divert investment and production from those ‘natural’ fields serving consumers efficiently into those areas that will prove to be wasteful and uneconomic.33
Gervaise’s analysis of the effects of monetary expansion was also significant in being more akin to Cantillon, by stressing the expansion of money inducing people to spend more, than to Hume, who confined his analysis to the increased money supply causing rising prices – neglecting the outflow of specie caused by greater monetary spending, on imports as well as on domestic products.34
From his analysis of natural law, trade, self-equilibration on the market and their disruptions by government, Isaac Gervaise proceeded to a strong recommendation of all-out free trade, free of any distortions or restrictions by government. Gervaise’s uncompromising free trade conclusion was all the more remarkable because his own firm enjoyed monopoly privileges conferred on it by the English Parliament. But Gervaise courageously concluded that ‘trade is never in a better condition, than when it’s natural and free; and forcing it either by laws, or taxes being always dangerous; because though the intended benefit or advantage be perceived, it is difficult to perceive its contrecoup; which ever is at least in full proportion to the benefit’. Here Gervaise anticipated the keen insights of the nineteenth century French laissez-faire economist Frédéric Bastiat, who stressed that government intervention stemmed from the fact that the benefits of subsidies or privileges are often direct and immediate, whereas the greater unfortunate consequences are more remote and indirect. The former are ‘seen’ whereas the latter are ‘unseen’, and therefore the seeming benefits get all the attention. Gervaise concluded with a plea for freedom and natural law that would anticipate Turgot and other French laissez-faire thinkers of his century: ‘Man naturally seeks, and finds, the most easy and natural means of attaining his ends, and cannot be diverted from those means, but by force, and against his will’.35
Isaac Gervaise wrote no more on economic questions, but he did become a distinguished Anglican clergyman, which makes it all the more puzzling that his exceptional and innovating pamphlet exerted no influence whatever on English opinion. It was lost to the world until resurrected by historians in the twentieth century.
Another hard-money advocate who developed a theory of international monetary equilibrium was a timber merchant of Dutch extraction, Jacob Vanderlint (d. 1740), in his tract, Money Answers All Things (1734). Despite the title, Vanderlint’s theme was that money is distributed properly and optimally on the free market. There is a tendency on the market for all nations’ prices to be equal, and if one country should acquire more money, its higher price level would soon draw the money out of the country until prices are back in equilibrium. It doesn’t matter, then, how much specie a nation may have, since prices would adjust. Thus, if a nation had little specie, its prices would be low and it would outcompete other nations, with gold and silver consequently flowing into the country. Indeed, so concerned was Vanderlint to keep prices low and competitive with other nations that he unknowingly replicated Cantillon’s advice for rulers or other worthies to hoard their gold and silver so as to keep national prices low.36
Vanderlint consistently carried over his hard-money analysis to the problem of expanding bank credit. Bank credit, Vanderlint pointed out, expands the money supply, and so, ‘as the Price of things will hence be rais’d, it must and will make us the Market, to receive the Commodities of every Country whose Prices of Things are cheaper than ours... [and hence] turn the Balance of Trade against us...’.37
Vanderlint, like Gervaise, was thus a severe critic of inflation and fractional-reserve banking, as well as an analyst of the international harmonies of money, prices and the balance of trade on the free market. Like Gervaise, Vanderlint was also an advocate of unrestricted free trade, concluding ‘In general, there should never be any restraints of any kind on trade, nor any greater taxes than are unavoidable’. Attempts to fix the price of gold and silver or to prohibit the export of coin are also futile: ‘it’s no less absurd for the government to fix the price they will give for gold and silver brought to be coined, than it would be to make a law to fix and ascertain the prices of every other commodity’. Vanderlint also deplored the rise, during the eighteenth century, of the war-making state, and of the high taxes and public debts which war brings in its wake. Indeed, for Vanderlint, free trade and free markets, and international peace, go hand in hand, while war is the enemy of freedom. War, warned Vanderlint, is ‘one of the greatest calamities to which mankind can be subjected; the end of which none can well foresee, and the burdens of which (i.e. public debts and taxes) are seldom discharged in one generation...’. Eloquently, Vanderlint concluded that ‘it’s monstrous to imagine, the author of this world hath constituted things so as to make it any ways necessary for mankind to murder and destroy each other’.38
The culminating hard-money theorist in eighteenth century England was Joseph Harris (1702–64), who published a massive two-volume Essays Upon Money and Coins (1757–58). Harris began life as a country blacksmith, but then went to London, where he became a prominent writer on navigation, mathematics and astronomy. He was an employee at the Mint, and was made assay master of the Mint in 1748.
Harris was a hard-money critic of debasement or fractional-reserve banking and bank credit expansion. He was an explicit follower of Cantillon’s analysis of money flows. Thus he saw, with Cantillon, that international monetary matters tended towards an equilibrium, but he also saw, with Cantillon, that inflows or increases of the money supply did not simply raise prices; they also necessarily affected the distribution of money, benefiting some people at the expense of others. Hence the flows of money, though self-adjusting, would cause economic harm, especially during the adjustment process. As Hutchison sums up Harris’s view: ‘Inflows of money enrich some at the expense of others, and such processes may for a time cause distress’. Sudden fluctuations of money, therefore, whether flowing in or out, ‘would be pernicious while it lasted and for some time afterwards’.39
As a result of his analysis, Harris was determinedly opposed to any alteration whatever of the monometallic monetary standard of a country (Harris favoured silver over gold as being more stable). As Harris emphatically warned: ‘The established standard of money should not be violated or altered, under any pretence whatsoever’.40
11.7 Laissez-faire by mid-century: Tucker and Townshend
If a hard-money stance had been pretty well established in English thought by the middle of the eighteenth century, so too had a corresponding if not fully consistent commitment to free markets and freedom of international trade. The Vanderlint-Cantillon–Harris analysis of international trade and money flows lent powerful arguments in the direction of freedom of trade. And, as we shall see in later chapters, the Scottish views of Carmichael, Hutchison and Hume were leading in the same direction in the northern part of Great Britain.
Josiah Tucker (1713–99), Anglican clergyman and dean of Gloucester from 1758 on,41 was a celebrated eighteenth century writer on religion, politics and economics who was extravagantly hailed in his day as a free trader by such men as the great laissez-faire statesman and economist A.R.J. Turgot, who translated two of Tucker’s works into French.42 But Tucker’s devotion to freedom of trade was only moderate, and marred by inconsistencies and contradictions. Thus Tucker favoured absolute prohibition on the export of raw materials, tariffs on manufactures, protective tariffs for infant industries, government compulsion – under severe penalties – of landlords to set aside 20 out of every 400 acres for timber, and heavy taxes on consumption of sports, recreation and luxuries. In general, even though he anticipated Adam Smith in praising the consequences of self-interest and ‘self-love’, he also believed in the importance of government directing and guiding the activities based on self-interest. He was also a characteristic mercantilist in urging the government to encourage ever greater population. It is true, however, that Tucker attacked the restrictionism of the navigation acts and the usury laws, both areas in which he was closer to a free trade position than that of the chronically over-praised Adam Smith.
On one free market point, moreover, Tucker was consistent and determined: opposition to war and conquest. In a letter to Lord Kames, during the Seven Years’ War with France, Tucker wrote: ‘War, conquests and colonies are our present system and mine is just the opposite’. Interestingly enough, however, Tucker was not at all moved by sympathy for the American cause. On the contrary, he believed that Britain had the full right to tax the colonies. But Tucker’s opposition to war triumphed, including a war to keep the colonies; to Tucker America ‘ever was a millstone hanging about the neck of this country, to weigh it down; and as we ourselves had not the wisdom to cut the rope and to let the burden off, the Americans have kindly done it for us’.43
Actually, Josiah Tucker’s main historical contribution was to highlight the views of a far sounder laissez-faire economist who has been shamefully neglected by virtually all historians of economic thought. Charles, the third Viscount Townshend (1700–64), has been virtually unknown, and often confused with his son of the same name who was infamously responsible for the fateful Townshend taxes on tea and other imports into the American colonies.
Our Lord Townshend was a scion of one of the great agricultural estates in England, son of the well-known diplomat and scientific farmer ‘Turnip’ Townshend, and husband of the glamorous socialite Audrey. Lord Townshend’s first published pamphlet cut against his own personal economic interest by denouncing the policy of large subsidies on the export of corn. The pamphlet, National Thoughts (1751), was signed ‘By a Landowner” to emphasize this point of arguing against his own subsidy.44
Dean Tucker struck up a correspondence with Townshend, in defence of the export bounty on corn. But soon Tucker was converted on the issue. Thus Townshend pointed out the folly of the British government subsidizing foreigners by allowing them to buy cheaper corn than the British themselves had to pay. Tucker was especially admiring of Townshend’s uniqueness in arguing particular cases from general principles instead of the other way round, and specifically the general interest in favouring free competition as against grants of monopoly by government. Thus, Tucker writes to Townshend that
I am mightily pleased with your Lordship’s... manner of accounting for People’s frequent and gross Mistakes in the Affairs of Commerce... by arguing from Particulars to Generals; whereas in this case a Man should form to himself a General Plan drawn from the Properties of Commerce, and then descend to Particulars and Individuals, and observe whether they are cooperating with the general Interest: Unless he doth this, he studies Trade only as a Monopolist, and doth more Hurt than Good to the Community.45
Tucker declared himself convinced that ‘bounties cannot be of any national service to a manufacture which is passed its infancy’.
A bit later in this correspondence, Lord Townshend demonstrated his adherence to free market principles by criticizing the inconsistencies of Sir Matthew Decker, a director of the East India Company. Decker (1679–1749), a Dutch immigrant, had also attacked the corn bounty, but Townshend was sharply critical because ‘Notwithstanding this sound Doctrine he [Decker] proposes to form [monopoly] Companies and to erect [governmental] Magazines of Corn in every County.... A most surprising absurdity and inconsistency’.46 Of course, the inconsistency is not so surprising if we realize that Decker was a director of the greatest monopoly company of them all. Townshend then goes on to point out that if, as he advocates, ‘Trade and Industry and all our Ports were thrown open and all Duties, Prohibitions, Bounties, and Monopolies of every kind whatever were taken off and destroyed’, then ‘private Traders here would erect Warehouses for Corn as they have done for other manufactures and we should then have them on a regular and natural footing and this Island would then be, as Holland has been, the great market of Europe for Corn. But as long as the Bounty remains this cannot be...’.
In National Thoughts Lord Townshend was worried about the poor, and paternalistically advocated removing the enforceability in court of small amounts of debt in order to help their condition. In later letters, however, Townshend introduced a bill in Parliament which would, instead, increase the mobility of the labouring poor by removing ‘certain Disabilities and Restraints’ upon them. Professor Rashid speculates that the change in stance came about because, ‘having accepted the validity of laissez-faire, Townshend came to believe that the poor could not be helped more than by making them free to help themselves’.47
So eager was Lord Townshend to spread the principles of free markets and free trade that in 1756 he sponsored prizes at Cambridge for essays on economic topics. Essay contests after the first year were discontinued because Townshend and the university could not agree on essay questions. Thus Cambridge turned down Townshend’s suggested topic: ‘What influence has Trade on the Morals of a Nation?’ Lord Townshend was indignant at Cambridge University’s implicit denial of any connection between trade and morality, and he replied indignantly and with keen perception: ‘There is not any moral Duty which is not of a Commercial nature. Freedom of Trade is nothing more than a freedom to be moral Agents’. This latter sentence expresses the crucial libertarian insight of the unity between free moral agency and freedom to act, produce, and exchange property.
Other questions suggested by Lord Townshend also put the libertarian rhetorical case very well:
- ‘Has a free trade or a free Government the greater effect in promoting the wealth and strength of a Nation?’
- ‘Can any restraints be laid on trade or industry without lessening the advantages of them? And if there can, what are they?’
- ‘Is there any method of raising taxes without prejudice to Trade? And if there is what is it?’48
Despite his neglect by historians, Lord Townshend’s views seem to have had substantial influence in his day. The prominent Monthly Review guessed the identity of ‘the Landowner’ author of National Thoughts immediately upon publication, and the pamphlet was quoted in another tract on the corn bounty the following year. Lord Townshend had a prominent connection with the important periodical, The Gazetteer. And in 1768, four years after Lord Townshend’s death, an anonymous pamphlet on Considerations on the Utility and Equity of the East India Trade argued, once again, for breaking the East India Company monopoly, and lamented the death of Lord Townshend, so sound and knowledgeable on commercial questions.
Clearly, Lord Townshend was far more influential in mid-eighteenth century England than later historians would know. Moreover, he was both an example and an embodiment of a rising tide of laissez-faire sentiment in the Britain of that era.
11.8 Notes
Hutchison, op. cit., note 2, p. 387.
One of the best brief summaries of Leveller doctrine is in C.B. Macpherson, The Political Theory of Possessive Individualism: Hobbes to Locke (Oxford: Clarendon Press, 1962), pp. 137–59.
On Locke’s clearly scholastic-influenced view of the just price as the market price, as expressed in his book Venditio (1695), see Karen I. Vaughn, John Locke: Economist and Social Scientist (Chicago: University of Chicago Press, 1980), pp. 123–31.
In our time, Hutchison suffers from excessive admiration of Tucker. His intemperate remark that Jacob Viner’s calling Tucker a ‘mercantilist’ is a ‘kind of reductio ad absurdum of that problematic term’ is uncalled-for; Viner’s treatment of Tucker is judicious and well-balanced. Hutchison, op. cit., note 2, p. 238; Viner, op. cit., note 27, p. 64, 71–2, 87, 98–100.
Rashid points out that several leading scholarly libraries have erroneously attributed authorship of this pamphlet to Townshend’s son. Rashid, op. cit., p. 73.
- 1 D.A.G. Waddell, ‘Charles Davenant (1656–1714) – A Biographical Sketch’, Economic History Review, ser. 2, 11 (1958), p. 288.
- 2 W. Letwin, The Origins of Scientific Economics (Garden City, NY: Doubleday, 1965), p, 122. Also see T.W. Hutchison, Before Adam Smith: The Emergence of Political Economy, 1662–1776 (Oxford: Basil Blackwell, 1988), p. 51. Professor Hutchison, however, takes Davenant’s scientific posturing all too seriously.
- 3 King’s manuscript remained unpublished for over a century, when it was published in 1802, by George Chalmers. King was an antiquarian clerk and accountant who wrote several unpublished tracts on statistics and political arithmetic. The Natural and Political Observations was published, along with another previously unpublished tract by King, in George E. Barnett (ed.), Two Tracts by Gregory King (Baltimore: Johns Hopkins University Press, 1936).
- 4 The shakiness of both the factual data and the ‘law’ can be seen by the fact that, in a slightly later tract. King presented a totally different quantitative ‘law’, amounting to:
- 5 John Creedy, ‘On the King–Davenant Law of Demand’, Scottish Journal of Political Economy, 33 (August 1986), pp. 208–10, and ibid., pp. 193–212. Also see the presentation in John Creedy, Demand and Exchange in Economic Analysis (Aldershot, Hants: Edward Elgar, 1992), pp. 7–23, a similar account with slightly different wording.
- 6 There was a direct filtration of ideas from Thomas Müntzer and the communist Anabaptists into England. One of Müntzer’s collaborators, Henry Niclaes, survived the smashing of Anabaptism to found familism, a pantheistic creed claiming that man is God, and calling for the establishment of the Kingdom of (man) God on earth, as the only place such a kingdom could ever exist. Familist ideas were carried to England by a disciple of Niclaes, Christopher Vittels, a Dutch joiner, and familism spread in England during the late sixteenth century. A centre of familism in early seventeenth century England was in Grindleton, in Yorkshire. There, in the decade after 1615, ‘the Grindletonians’ were led by Grindleton’s Anglican curate, the Rev. Roger Brearly. Part of the attraction of familism was its antinomianism, the view that truly godly persons, such as themselves, could never commit a sin, by definition, and therefore antinomians usually flaunted behaviour generally considered sinful in order to demonstrate to one and all their godly and ‘sin-free’ status.
- 7 The Levellers have acquired a left-wing colouration because of their label, and because they have been admired by Marxist historians, enthusiastic about their radicalism, and as the most consistent figures in the ‘bourgeois revolution’ of the seventeenth and later centuries. The Levellers, however, were in no sense egalitarians, except in the laissez-faire libertarian sense that they were opposed to special privileges granted by the state. On the Levellers, see especially Don M. Wolfe (ed), Leveller Manifestoes of the Puritan Revolution (1944, New York: Humanities Press, 1967), including the editor’s lengthy introduction; and the latest collection of Leveller tracts in A.L. Morton (ed), Freedom in Arms: A Selection of Leveller Writings (London: Lawrence & Wishart, 1975). Also see the classic H.N. Brailsford, The Levellers and the English Revolution (Stanford, Calif: Stanford University Press, 1961).
- 8 Much mischief has been wrought by the interpretation of Leo Strauss and his followers that Locke was a natural rights-er who (following Hobbes) broke with the wise ancient tradition of natural law. Actually, Locke the natural rights-er developed the scholastic natural law tradition, and was the opposite of Hobbes’s right-wing Grotian apologia for state absolutism. On Hobbes, Locke, and the Tew circle, see Richard Tuck, Natural Rights: Their Origin and Development (Cambridge: Cambridge University Press, 1979). Leo Strauss’s interpretation is in his Natural Right and History (Chicago: University of Chicago Press, 1953). For a critique of Strauss, and insistence that Locke was not a Hobbesian but in the natural law tradition, see Raghuveer Singh, ‘John Locke and the Theory of Natural Law’, Political Studies, 9 (June 1961), pp. 105–18.
- 9 The locus classicus of the Pocockian thesis is J.G.A. Pocock, The Machiavellian Movement (Princeton, NJ: Princeton University Press, 1975). In addition to the contrasting works of Isaac Kramnick and Joyce Appleby, see in particular the scintillating refutation of Pocock’s central example: the alleged ‘classical virtue’ emphasis of the radically Lockean Cato’s Letters, which provided the greatest single libertarian influence on the American revolutionaries. Ronald Hamowy, ’Cato’s Letters: John Locke and the Republican Paradigm’, History of Political Thought, 11 (1990), pp. 273–94.
- 10 Richard Ashcraft, Revolutionary Politics and Locke’s Two Treatises on Government (Princeton, NJ: Princeton University Press, 1986).
- 11 Ibid., pp. 75–82, 370–71.
- 12 A more detailed analysis of seventeenth century Dutch politics would show, however, that the free market, decentralized, pro-peace party was the republicans or Arminians, followers of the Protestant theologian Jacobus Arminius, who was theologically closer to Catholics in believing in free will for salvation. On the other hand, the ‘Calvinist’ party in Holland favoured the Orange monarchy, statism, controlled markets, and a warlike foreign policy.
- 13 As Letwin states, ‘[Child] urged that foreign trade – except that with the East Indies – be opened to anyone who chose to engage in it; and the argument is studded with catchwords suggestive of laissez-faire.... No doubt Child opposed certain mercantilist restrictions, as many other mercantilists did, but he did not oppose them in principle. He objected to those restrictions which embarrassed the branches of industry that concerned him and consistently advocated restrictions which fostered those branches. His position was exactly analogous with that of a textile manufacturer, for instance, who opposes import restrictions or protective duties on the fibers he buys while insisting that heavy duties be placed on foreign finished goods that compete with those he sells...’ Letwin, op. cit., note 2, pp. 46–7.
- 14 Schumpeter’s favourable assessment of Child rests on his assumption that Child was the author of the tract by ‘Philopatris’ that took the laissez-faire view that money was simply another commodity and that therefore it didn’t matter whether it was imported or exported. But for a convincing demonstration that Child was not ‘Philopatris’, see Letwin, op. cit., note 2, pp. 50, 253–5.
- 15 Letwin, op. cit., note 2, p. 8. Also see the critical pamphlets of Thomas Manley, Usury at Six Per Cent Examined (1669), and the anonymous tract with the fully revealing title: Interest of Money Mistaken, Or, A Treatise proving that the abatement of interest is the effect and not the cause of the riches of a nation.... (1668).
- 16 See Henry W. Spiegel, The Growth of Economic Thought (3rd ed., Durham, NC: Duke University Press, 1991), pp. 154–5.
- 17 In Hutchison, op. cit., note 2, p. 67. See in particular, the discussions in Letwin, op. cit., note 2, pp. 69–81, 182–4, 260–70.
- 18 Actually, Praisegod’s real Christian name was highly unwieldy, even if more pious. He was named ‘Unless-Jesus-Christ-Had-Died-For-Thee-Thou-Hadst-Been-Damned’ Barbon.
- 19 In Barbon’s A Discourse Concerning Coining the New Money Lighter, In Answer to Mr. Lock’s Considerations...(1696). See Letwin, op. cit., note 2, pp. 78–9.
- 20 Despite the hostility to Locke’s point of view among modern inflationist and Keynesian historians, it is clear from Letwin’s account, op. cit., note 2, pp. 69–77, 260–70, that the calamitous price contraction that inflationists would have expected from the monetary contraction of the Lockean recoinage did not take place.
- 21 A complicating point is that the Whig Establishment was run at the top by Robert Walpole and the Pelham family, who were really laissez-faire, pro-peace liberals trying to run a Whig Party of totally contrasting principles. Walpole managed this feat in the 1720s through the 1740s, and the Pelhams continued for some years after, largely by brilliant political manipulation and by tactical management of what both Left and Right denounced as ‘corruption’. The main device by which Walpole managed to placate the Whig magnates temporarily was to pass the mercantilist measures in Parliament (e.g. restricting American colonial trade and production) and then simply failing to enforce them. See Murray N. Rothbard, Conceived in Liberty, Vol. II: ‘Salutary Neglect’ (New Rochelle, NY: Arlington House, 1975), Part III.
- 22 The 1742 Life was of Francis, Baron Guilford, and the 1744 Lives were biographies of Dudley, and of Dudley’s younger brother, John (1645–83), who in his brief life became professor of Greek and master of Trinity College, Cambridge. The first and eldest brother, Charles North (1630–90), lived a retired life and little is known of him.
- 23 For an excellent discussion of the contributions of Dudley and Roger North, see Letwin, op. cit., note 2, pp. 196–220, 271–94.
- 24 Letwin, op. cit., note 2, p. 204. Italics added by Letwin.
- 25 Letwin, op. cit., note 2, p. 209.
- 26 Letwin, op. cit., note 2, pp. 215–16.
- 27 The following year, in his famed Leviathan (1651), the authoritarian political philosopher Thomas Hobbes also used the money–blood analogy; after writing on how money ‘goes round about, nourishing (as it passeth) every part thereof [of the commonwealth],’ Hobbes adds that ‘natural blood is in like manner made of the fruits of the earth; and circulating nourisheth by the way, every member of the body of man’. See Jacob Viner, Studies in the Theory of International Trade (New York: Harper & Bros, 1937), p. 37n.
- 28 Charles Rist justly criticized Law that: ‘To infer from the abundance of metallic money in a prosperous country that it is enough to “create” paper money... in a poor country in order to develop industry or natural resources in which it is lacking, is an idea that affronts common sense... Scotland, a country of shepherds and fisherman, mountainous and poor in raw materials... could have increased its currency, but it would have given the country neither industry, nor trade, nor agriculture, nor a prosperous shipping industry. That could be attained only by the labour and frugality of its inhabitants’. Charles Rist, History of Monetary and Credit Theory from John Law to the Present Day (1940, New York: A.M. Kelley, 1966), pp. 47–8.
- 29 See Joseph T Salerno, ‘Two Traditions in Modern Monetary Theory: John Law and A.R.J. Turgot’, Journal des Économistes et des Études Humaines, 2, note 2–3 (June–Sept 1991), pp. 340–41.
- 30 For the relations between Law and Cantillon in this dramatic period, see Chapter 12 on Cantillon. On the interrelationships of Law, Cantillon, and the contemporaneous Mississippi and South Sea bubbles, see Antoin E. Murphy, Richard Cantillon: Entrepreneur and Economist (Oxford: The Clarendon Press, 1986); on the evolution of Law’s doctrines, see Antoin E. Murphy, ‘The Evolution of John Law’s Theories and Policies, 1707–1715’, European Economic Review, 34 (July 1991), pp. 1109–25. For an analysis of Law’s doctrines and his unheralded influence upon modern economics, see Salerno, op. cit., note 29, pp. 337–79. For Law’s influence on Adam Smith, see also Roy Green, Classical Theories of Money, Output and Inflation (New York: St Martin’s Press, 1992), pp. 110–27.
- 31 For example, Sir Humphrey Mackworth ‘plagiarized’ Law and his inflationist arguments in his tract, A Proposal for Payment of the Publick Debts (2nd ed., 1720). See Viner, op. cit., note 27, pp. 44–5.
- 32 The full title of the Gervaise pamphlet reveals its grounding in the denunciation of Lawlike monetary and credit expansion: The System or Theory of the Trade of the World, Treating of the Different Kinds of Value, of the Balances of Trade, of Exchange, of Manufactures, of Companies, and Shewing the Pernicious Consequences of Credit, and That it Destroys the Purpose of National Trade.
- 33 Gervaise wrote: ‘All the profit a nation gains by unnaturally swelling its denominator [its supply of money], consists only in the inhabitants living for a time in proportion to that swelling so as to make a greater figure than the rest of the world, but always at the cost of their coin, or of their store of real and exportable labour... [N]o thing in the world is of any solid or durable worth, but what is the produce of labour; and whatever else bears a denomination of value, is only a shadow without substance, which must either be wrought for, or vanish to its primitive nothing...’ See Hutchison, op. cit., note 2, pp. 127–8.
- 34 Sekine is right in calling this Gervaise–Cantillon analysis ‘the cash-balance effect’ rather than a Keynesian ‘income effect’. Thomas T. Sekine, ‘The Discovery of International Monetary Equilibrium by Vanderlint, Cantillon, Gervaise, and Hume’, Economia Imernazionale, 26 no. 2 (May 1973), pp. 270–74.
- 35 Hutchison, op. cit., note 2, p. 128.
- 36 By hoarding specie, Vanderlint counselled, ‘by thus keeping so much of those Metals out of Trade... it will... prevent our Markets from rising so high, as to hinder the Exportation of our Commodities, or give too great Encouragement to the Importation of Foreign Goods’. See Chi-Yuen Wu, An Outline of International Price Theories (London: George Routledge & Sons, 1939), p. 64.
- 37 Ibid., pp. 64–5.
- 38 Hutchison, op. cit., note 2, p. 132–3.
- 39 The latter quote is from Harris. See Hutchison, op. cit., note 2, p. 244.
- 40 For David Hume’s similar, 100 per cent reserve banking analysis at about the same time in Scotland, see Chapter 15 on the Scottish Enlightenment.
- 41 Tucker was the son of a Welsh farmer and salt officer who went to Oxford and, after graduation, became an Anglican clergyman. His admirers like to repeat the story, apparently true, that Tucker walked back and forth from Wales to Oxford at the beginning and end of each term, leaving his father to use the sole family horse. No doubt admirable for Josiah, although the story does not improve his economic performance.
- 42 Tucker’s first work on economics was his Essay on Trade (1749), which was something of a best-seller, going into four editions by 1764. He then planned to write a comprehensive treatise on economics, but only two fragmentary parts were written, both printed privately for friends and not published: The Elements of Commerce and Theory of Taxes (1755) and Instruction for Travellers (1757).
- 43 Tucker’s view found an echo in other exasperated British Tories. Thus the great John Wesley, founder of Methodism, stated, ‘I say, as Dean Tucker, “Let them drop”... Four-and-thirty millions they have cost us to support them since Queen Anne died. [1715] Let them cost us no more.’ The celebrated Dr Johnson, in his Taxation No Tyranny (1775) observed that ‘The Dean of Gloucester has proposed, and seems to propose it seriously, that we should at once release our claims, declare them masters of themselves, and whistle them down the wind... It is however a little hard, that having so lately fought and conquered for their safety, we should govern them no longer’. Johnson countered with a ‘wild proposal’ of his own: ‘Let us restore to the French what we have taken from them. We shall [then] see our colonists at our feet...’ Tucker, however, would undoubtedly have seriously agreed to Johnson’s attempted reductio ad absurdum. See George Shelton, Dean Tucker and Eighteenth-Century Economic and Political Thought (New York: St Martin’s Press, 1981), pp. 214–5.
- 44 The full title was: National Thoughts, Recommended to the Serious Attention of the Public. With an Appendix, Shewing the Damages Arising from a Bounty on Corn. In Salim Rashid, ‘Lord Townshend and the Influence of Moral Philosophy on Laissez Faire’, The Journal of Libertarian Studies, 8, no. 1 (Winter 1986), pp. 69–74. Rashid is virtually the only historian to resurrect Townshend and demonstrate his importance. But see Shelton, op. cit., note 43, pp. 79, 88.
- 45 Tucker to Townshend, 22 April 1752. Rashid, op. cit., note 44, p. 73.
- 46 It is amusing to contrast Townshend’s critical attitude toward Decker with the laudatory appraisal of T.W. Hutchison, who virtually finds Decker a free trade hero, calling for ‘the abolition of all duties’, and opposing the Navigation Act as well as retaliatory tariffs. Rashid, op. cit., note 44, p. 71; Hutchison, op. cit., note 2, pp. 393–4.
- 47 The Townshend bill was introduced in 1753, but no action was taken on it. Rashid, op. cit., note 44, pp. 71, 73.
- 48 Rashid, op. cit., note 44, p. 72. The libertarian answers, presumably to be elicited by Lord Townshend’s questions, are, respectively: free trade, no, and no.

