
Value, Capital & Rent
II. The New Theory of Capital and its Relations to the Theory of Wages, Ground-Rent and Values of Goods
AND ITS RELATIONS TO THE THEORY OF WAGES,
GROUND-RENT AND VALUES OF GOODS1
1—The concept of capital
It is difficult, if not impossible, to define the concept of capital in a wholly satisfactory way, that is to say, in a way which would combine scientific precision with close adherence to everyday language. In the exact sciences one simply disregards the ordinary use of the language and creates an entirely new terminology; but this is not yet possible in a subject like political economy, which is and must be wholly concerned with practical problems. Considerably more harm than advantage would result from it.
But when we think of the history of the development of the concept of capital it is easy to understand why, in everyday life, the use of language became so very vague just at this point. Originally the word expressed, as we know, simply the main stock of a loan (capitale or capitalis pars debiti) as contrasted with the interest, and therefore an interest-bearing sum of money. All further meanings of the word are now obtained by more or less apt extensions of this root concept.
It was most natural to wish to apply the name capital to all interest-bearing objects of wealth—that is to say, all goods or groups of goods which procure for their possessors an income, without being consumed themselves in this process; and all the more so, in that all sources of income excepting human abilities themselves obtained a money or capital value with the increasing money circulation.
On the other hand, I do not think it permissible to say, with Böhm-Bawerk,2 that the other interest-bearing goods received the name capital because it ‘had become clear that the interest-bearing power of sterile money was, after all, a borrowed one—borrowed from the fruitful power of objects which could be bought for money.’ This was indeed a popular way of explaining the origin of money interest; but if it had been really understood ‘clearly,’ then, properly speaking, money would have had to be excluded from the concept of capital.
But this Böhm-Bawerk himself does not do, and he is right; for the interest-bearing power of money is by no means a ‘borrowed’ one. When, for instance, money serves as a medium of exchange, it really creates the value or increase in value which is later added to it as interest—and even more. It is, however, true that so-called money capital is often money only in name; in reality it merely denotes a sum of goods estimated in money.
This extension of the concept of capital, through which it comes to mean approximately fortune or at least interest-bearing fortune, may be fittingly employed in several respects. It is usually adopted in socialist and other popular writings, so that in these writings capitalists and workers are more or less the same as propertied and unpropertied classes. The ‘capital market,’ in the usual sense of the word, is made up, as we know, of all possible securities which represent interest-bearing fortune.
For most economic considerations, however, a certain limitation of this more general concept proved expedient. A concrete sum of money has obviously its analogue and counterpart not so much in landed property or other natural sources of goods as in the produced goods themselves; it is a type of stored-up wealth. The most important economic difference between landed property and produced goods seems to lie in the fact that the former yields its useful services only successively in a chronological sequence previously determined and unchangeable, but, to compensate for this, in an infinite sequence. Produced goods, on the other hand, can yield only a finite number of useful services, but in an almost optional sequence, much as a sum of money can be spent either all at once or by instalments over a longer period. This distinction, however, is not precise. An ore-mine or coal-pit, for instance, which can be exhausted at very different rates, has, from this point of view, more in common with a produced store of food or clothes than with landed property agriculturally used. On the other hand, a dwelling-house, for instance, which lasts perhaps for centuries, but which can provide accommodation for only a certain number of people at one and the same time, has, from the economic point of view, very much in common with landed property. However, the above-mentioned attribute of most produced goods is important, especially with regard to further production: it can be said of the tools of production that the more they can be used optionally the more they preserve a capitalistic character (in its narrower sense); for instance, machines, which can be made to run quicker or slower, or can stop, without suffering wear and tear, etc. Other arrangements, on the contrary—for instance, certain land improvements—once carried through, become so completely part and parcel of the landed property that they lose the above-mentioned character; that is to say, they are now really rent-goods and no longer capital-goods in the narrower sense of the phrase.
The seemingly paradoxical phenomenon, that consumable goods—that is to say, goods which exhaust or seem to exhaust their whole content of usefulness in a limited series of acts of use—can nevertheless be employed ‘capitalistically,’ so that their entire value remains stored up for the owner, and yet provides him with an income—this perpetuum mobile of the economic mechanism forms, as was said previously, the real pith of the theory of capital, which we shall now consider more closely.3
On the whole, of course, this can only happen through the re-creation by production (in the widest sense of the word, which includes traffic) of the consumable goods or their equivalent in value. Their former existence must, in this case, be a necessary condition of the production, otherwise a part of the produced goods could not possibly fall to the owner of the capital as owner.
But according to the usual conception, other means of acquisition are supposed to exist besides production (in the above-mentioned widest sense), and accordingly a further distinction should be made between ‘private capital’ and ‘national capital’—or as it ought to be called, according to Böhm-Bawerk, ‘social capital’—where the former category comprises all means of acquisition (usually with the exception of landed property), whilst the latter comprises only the real means of production.
I am doubtful whether this distinction is really a scientifically fruitful one. It is, of course, allowable in this as well as in other economic spheres to keep the point of view of private enterprise separate from the social point of view. But I think there is little justification for the attempt to draw up certain categories of goods, some of which are supposed to be capital only from the point of view of private enterprise, whilst others are supposed to be capital from the social point of view as well.
In Böhm-Bawerk’s opinion, dwelling-houses, for instance, can only represent private capital (if they are let to others)—not social capital, because they are only consumption goods, not productive goods. It is true that they yield their useful services spontaneously, without considerable addition of labour. But the same is true to a large extent of meadows, woods, preserves, etc., which, however, cannot be denied the name of capital—in the ‘social’ sense of the word—if one wants to extend this concept to landed property at all. Therefore it seems best to me to put dwelling-houses in the same category as landed property. However, if they are to be regarded as capital at all, it seems clear to me that they must be considered as belonging to social capital.
This would indeed still be contrary to the remark of Adam Smith quoted by Böhm-Bawerk, that the community (as contrasted with a single individual) ‘can only enrich itself by production.’ But the enrichment of the community is a matter of comparative detail. Nor, by the way, is the private capitalist primarily enriched by interest, but lives on it. The chief aim of economic life, for the community as well as for the individual, is obviously to maintain the level of well-being already achieved. And this end is served not only by real production, but by the mere storing-up of durable utility goods regardless of whether these are produced or were the direct gift of Nature. The opinion that durable goods cease to be capital the moment they are consumed by their owner and consequently no longer provide him with a money income, is, as A. Marshall remarks,4 really nothing but a relic of the prejudices of the old mercantile system.
It is not quite clear to me in what way exactly the poor circulating libraries have offended, which, along with articles for hire (e.g. fancy-dresses and the like), must serve as standing examples of things which represent only private, but not social capital. As long as social conditions do not make it possible for everybody to possess an extensive collection of books, public libraries, whether they can be used free of charge or for a fee, are certainly an ingredient, and a not unimportant one, in social capital. The keeping of a lending library is a business, like all the others. If now, with Böhm-Bawerk—and quite correctly, as I see it—one calls ‘the consumption goods in the hands of producers and merchants, stored up as warehouse stock,’ capital and, what is more, social capital,5 then it seems strangely inconsistent to wish to exclude lending libraries simply because it is their purpose to sell reading-matter instead of books.
But more important is the question of what is to be done with the ‘means of subsistence of workers.’ Strange to say, Böhm-Bawerk saw that he was obliged to place this important category of goods called by Jevons, as is well known, the real substance of productive and consequently of social capital, in the mixed collection of exclusively private capital together with ‘rentable houses and lending libraries.’ For to this collection belong, according to him, ‘all those consumption goods which their owner does not use himself but employs by exchange (selling, letting, lending) for the acquisition of other goods’; and amongst them must be included, as he explicitly remarks, the ‘means of subsistence which the entrepreneurs advance to their workers.’6
But again: he himself, a few pages before, has represented the ‘stored-up consumption goods in the hands of producers and merchants’ as social capital, and to money he gives the same name. If now wages, as usual, are paid in money and the workers themselves obtain what they require from the merchants, then these goods, before they pass into the hands of the workers, are social capital according to Böhm-Bawerk’s terminology. But if the entrepreneur buys the same goods for the same money, in order to transfer them subsequently as wages to the workers, then these goods in the hands of the entrepreneurs—and once again before they pass to the workers—would not be social capital any longer, but simply private capital !
That a writer so sagacious and circumspect as Böhm-Bawerk could be led to such strange conclusions, is, if I am not mistaken, due to a circumstance which, in other respects as well, has done great damage in political economy, namely to the vague idea that from the economic point of view it is, practically speaking, of no consequence to whom the goods belong, provided only they are there. As soon as it is a question of deciding whether or not the means of subsistence of workers are social capital, Böhm-Bawerk always reasons as if these means of subsistence were already in the hands of the workers. But since workers are human beings and members of the community—at least according to the modern way of thinking—their means of subsistence must be regarded in the same way as those of the rest of the population. ‘The goods with which the working members of the community feed, warm and clothe themselves, are goods for immediate consumption, not means of production.’7
Economically understood, this is certainly true. It could even be added that these goods, from the technical point of view also, are means of production only in so far as they are really converted into labour, so that only that portion of the means of subsistence which corresponds to about the exact minimum of life would, in fact, (technically) be productive. From the economic point of view, the means of subsistence, as soon as they have passed into the possession of the workers, are no longer means of production at all and no longer capital (either ‘social’ or ‘private’), because their productive equivalent has in this case already been parted with and has entered into the possession of the capitalist.
But if the means of subsistence have not yet passed over into the hands of the workers, but are still (directly or indirectly through money) in the possession of the capitalist, then they are undoubtedly means of production, because they serve for the purchase of labour.8
It will perhaps be best, if we are to find our way in this rather complicated state of affairs, to base our thinking throughout upon the assumption of a stationary community, as the simplest hypothesis. For all productive factors, and consequently capital too, could then be considered as approximately constant magnitudes. Though in this case the forms of the latter change, its total value remains unchanged, since in place of the consumed capital goods new ones of equivalent value enter successively.
But Böhm-Bawerk goes on to remark that if the whole national subsistence fund is called capital, ‘then not only must the means of subsistence of the productive workers be reckoned as capital, but also the subsistence of the capitalists and landowners, as standing in exactly the same indirect relation to the adoption of capitalist methods of production.’9 As far as the landowners are concerned, this is undoubtedly correct. The landowners, too, live during production, which in certain cases takes several years before the products are finished; that is to say, they live on their ground-rents. Therefore, either they are capitalists themselves (at least up to the amount of the ground-rents due after the completion of the production process), or they get their ‘subsistence,’ that is to say their rents, as an advance from the capitalists, who must in consequence successively keep in stock the consumption goods concerned or the money for them. And in so far as these consumption goods in the hands of the capitalists serve for the purchase of the productive services of land, they must certainly be conceived as productive capital. But if they have passed into the possession of the landowners, they no longer serve production and are therefore no longer capital; but then their equivalent, the services of the land, raw materials, etc., is already added to the capital stock of the country.
Lastly, so far as the means of subsistence of capitalists themselves are concerned, one might be tempted to give up calling these capital, and to call them instead just—interest. Consistency requires, however, that they should be thought of all the time as capital until the moment when they find themselves in the possession of the consumers concerned. In other words, capital is regarded in stationary economy as capable of a certain, but on the whole not noticeable, oscillation, since it continuously increases by interest and is in the same way continuously decreased by the consumption of this interest.
The distinction between private and social capital laid down by Adam Smith and even extended by Böhm-Bawerk, does not therefore really exist, in my opinion. Social capital simply consists of the sum of private capitals. One might think that at least in one point a real difference must be made between social and private capital, namely in respect of the consumption loan. But this difficulty disappears at once if, according to the commendable example of Böhm-Bawerk, we reckon as capital only material goods, but not either ‘rights and situations’ (Rechte und Verhältnisse) or personal attributes. A patrimony, dissipated by the heir in advance of his inheriting it, who thus gets into debt, exists afterwards solely in the form of a claim, which at the moment is not counterbalanced by a single material commodity and the like is true of every consumption loan.
But claims can, of course, be reckoned as belonging to capital (as social capital, to be sure), if at the same time debts are admitted into the final sum of social capital as negative items or quantities.
It must, however, be remarked that social capital, so carefully defined by Böhm-Bawerk, plays almost no part in his following investigations. When he speaks about the real problems of the theory of capital interest, the difference, so laboriously demonstrated, between ‘aggregate of the intermediate products’ (social capital) and ‘national subsistence fund’ (also called by him ‘national capital’) is again missing. And rightly so; for if the sphere of ‘intermediate products’ is extended over the entire domain of production in its widest sense, up to the moment of consumption,10 all concepts are, in fact, simply congruent: social or productive capital, national subsistence fund or ‘national capital,’ and finally private capital or simply capital (with the exception of landed property).
To sum up: in the wider sense, all interest-bearing (material) goods are capital; but the different capitals do not all play the same economic role. There is ‘capital in the narrower sense,’ as distinct from ‘capital in the wider sense.’ But it is more difficult to decide where the line of demarcation can best be drawn here—whether, as is usually assumed, it ought simply to separate produced goods from pure natural goods (landed property), or (according to Wieser) must be more closely related to the ‘consumability and mobility,’ and therefore the ready availability and utilization of capital-goods in the narrower sense.
Probably, too, the different economic problems will require a different delimitation of the concept, just as in popular terminology the word capital forms a real Proteus concept.
However, it seems best to me for the purposes of the following investigation to class the different capitals simply according to their durability. In what follows I shall call the highly durable goods rent-goods, whether they are products themselves, or, like virgin soil, goods furnished by nature itself and whether they yield useful services spontaneously or only by the addition of human labour.11 Consumable or quickly exhausted production or consumption goods, so long as the latter are not yet in the hands of consumers, I shall call capital-goods or capital in the narrower sense.12
The boundary line in this case remains to be determined, of course. However, this indeterminateness is of no importance when it is merely a question of explaining the nature of capital interest. On the other hand, as soon as one approaches the problem of ascertaining exactly the reasons which determine the level of interest and the relations between capital-interest, wages and ground-rent (the imputation of the productive factors, according to Wieser’s terminology), it at once appears necessary to unite the different capital-goods, as far as possible, in one sum ; which, of course, assumes a previous, more or less rigorous, demarcation of the sphere of capital. This obviously cannot be done with this or that definition established a priori; on the contrary, it requires an exact exploration of the true functions of these economic forces and also an investigation into how far these forces can really be united in one sum or—to use an analogy from mechanics—in one single resultant. This sum or resultant would then be the capital—within the limits of the problem concerned.
If we wish to interpret the divergent views regarding the concept of capital as a testimonium paupertatis of political economy, we shall not be wholly wrong. Only it must be remembered that strict definitions of concepts always form the keystone rather than the basis of a scientific system ; and it will be a comfort to reflect that even the most exact of the sciences, mathematics, has not yet arrived at satisfactory definitions.
2—Böhm-Bawerk’s theory of interest and the earlier theories
How does interest arise, and in particular, how can consumable goods bear interest; that is to say, at least in appearance yield useful services, without thereby diminishing in value?
I should like to let Böhm-Bawerk speak on this question. No one can have read his two volumes Kapital und Kapitalzins carefully without having gained therefrom a real enrichment of his theoretical knowledge. If we cannot agree with all his conclusions, yet we must gratefully acknowledge that scarcely any other author has penetrated so deeply as he into the real nature of the matter. At any rate, no one has been able to combine profundity and clarity to the extent that he has done.
His one fault, it seems to me, is that he sometimes wants to be too profound. He loves to pile up theoretical difficulties, in order, of course, to remove them later on—for the most part satisfactorily, but in a way which is somewhat confusing to the ordinary reader.
The simple formula in which Böhm-Bawerk wishes to comprehend all phenomena in the realm of capital interest, and by which all earlier theories of interest are to be replaced, runs, as is well known, as follows: Interest is an agio which comes into being when present and future goods are exchanged. It rests solely on the relationship between present and future in human economy and simply expresses the fact that present goods (at least according to the contemporary valuation) are as a rule more valuable than future goods of the same kind and number.
There can be no doubt that this formula governs the problem of interest in its whole extent13—and it is no mere tautology, which simply expresses that A = A, interest is—interest! The clarifying element, newly added, lies in the word exchange: the problem of interest can now be treated as a true problem of exchange. In particular, the consideration of marginal utility will play the same part in the theory of interest as in the theory of ordinary exchange. And this applies to ‘natural interest’ as well as to interest on loans. He who parts with present goods, in order in some way or other to obtain future goods of the same kind, really makes an exchange between two uses of the same commodity. He thus performs the very action which we, at the beginning of our remarks concerning exchange, put forward as its simplest form; and the degree in which he does this is regulated, as there, by the proportion of two marginal utilities (that of the present goods and that of the future goods, according to the contemporary valuation).
Also, the interest on the loan, just like the exchange value in the case of ordinary exchange, will depend on two proportions of marginal utility; that is to say, it will depend first on the proportion between the marginal utility of present and that of future goods for the creditor, and secondly on the proportion between the analogous marginal utilities for the debtor. Usually in this case the marginal utility of present goods for both will prove to be higher than the marginal utility of future goods of the same kind and number; so that the interest almost always turns out to be positive—that is to say, it will be paid by the debtor. The proportion of marginal utility can finally become identical on both sides, but not the proportion of the total utility. This, on the contrary, must always be different, if a loan is to take place at all, and in such a way that the debtor as opposed to the creditor always values present goods relatively higher. The interest which must really be paid will then fall somewhere or other between these two different valuations.14
The passages in which he discusses how and why present goods, according to the existing valuation, almost always possess a higher utility or marginal utility respectively than future goods, belong to the best-known and most important parts of Böhm-Bawerk’s book. These we shall now examine briefly.
The first main ground is stated to be the difference in the circumstances of want and provision at different periods of time.
Whether this can rightly be conceived as a main ground of the phenomenon of interest, is open to question. In a stationary economy (which in my opinion must always be considered first as the simplest case), needs and their satisfaction are to be understood as, on an average, constant magnitudes. In such an economy also, it is true, several persons, or whole age-groups, could expect a more abundant satisfaction in the future than now. But besides these there are other individuals for whom the opposite is true; so that it seems as if, under this assumption, supply of, and demand for, present goods against future goods must equal each other also at par.
Böhm-Bawerk remarks, however, that even where provision for the future will presumably be less plentiful, the present goods must at least be equal in value to the future goods, since they can, if necessary, easily be preserved for use in the future. This is certainly a great exaggeration. Böhm-Bawerk mentions, to be sure, ‘an exception’ to this rule—in respect, that is, of ‘perishable goods, such as ice, fruit, and so forth.’ But this applies in a greater or less degree to all food-stuffs without exception. Why, there are perhaps no goods apart from precious metals or stones, for instance, whose preservation for the future does not require special care and effort, with the additional risk that they may yet be lost in a fire or by some such misfortune.15
In countries with a great future before them, like certain colonial countries, more plentiful provision for the future can admittedly be regarded as a common fact, and undoubtedly contributes to the level of the rate of interest customary there. In countries with a long-established culture, and in the case of a practically stationary economy, the higher valuation of present as against future goods will, on the other hand—if the possibility of a productive application of these is disregarded—occur to a much more limited extent than Böhm-Bawerk seems to think.
However, this would have been the place to discuss a circumstance which Böhm-Bawerk only mentions later in another connexion and only in passing—namely, that the use of present goods for the future, under otherwise similar circumstances, must in itself call forth for the possessor in question a more plentiful provision for the future as distinct from the present, and therefore, in its turn, lead to the higher valuation of present goods.
It is just this circumstance which, in combination with the second main ground, soon to be mentioned, sets bounds to the sacrifice of present pleasures in the interests of the future; that is to say, the formation of capital.
Böhm-Bawerk’s second main ground—the subjective and often incorrect underestimation of future wants resulting from defects of imagination or will—is without doubt of the utmost importance. Not only does it constitute, in combination with the uncertainty of all legal and economic affairs, the chief cause of the feeble formation of capital and the excessively high rate of interest in all primitive economies, but scarcely a day goes by without its effects being traced by each one of us to some extent.
But when Böhm-Bawerk mentions in this connexion the ‘consideration of the shortness and uncertainty of our life,’ and asserts: ‘Payments which become due in 100, 50 or even only 20 years lose value for all . . . receivers in view of the uncertainty of their expectation of life,’ it seems to me open to question whether one can speak here only of subjective underestimation. Our children, grandchildren and great-grandchildren will in general have at their disposal the same means of satisfying their needs as we. Whether we, by denying ourselves now, can give them a corresponding advantage, therefore remains doubtful, especially with regard to the more distant generations of our posterity, whose well-being will depend only to a very limited extent on us. We will not allow ourselves to be held up by this, however, but proceed now to the third and last of the main grounds put forward by Böhm-Bawerk.
This, as the author himself admits, is practically identical with what in former times one used to understand by the phrase ‘productivity of capital.’ Since, however, as is well known, he cannot recognize the ‘productivity theory’ as relevant, he now endeavours to explain independently why present goods are, ‘as a rule, on technical grounds, preferable instruments for the satisfaction of our needs and assure us, therefore, of a higher marginal utility’ than future goods.
According to him the explanation lies in the fact ‘that time-consuming, round-about methods of production are more productive. That is to say, given the same quantity of means of production, the lengthier the productive method employed, the greater the quantity of products that can be obtained.’ The role of capital in production is therefore, as was already emphasized by Jevons, simply this, that it can introduce a shorter or longer interval of time between the beginning and the completion of production, whereas primitive production, carried on without capital, must always live ‘from hand to mouth.’
With a certain sum of primary productive forces—for instance, with one working month which is to-day at our disposal—we shall be able to produce more goods if it is used as the starting-point of a period of production of one year, than if we were to use it for the immediate production of goods of the same kind; and consequently more goods also than could be obtained if one of next year’s working months were used to produce goods straight away. If even lengthier methods of production are adopted, so that, for instance, the goods in question are intended to be ready in two years’ time, the superiority of to-day’s working month over next year’s working month holds good also; for the former could then be employed as the starting-point of a two-year production process, whilst the latter could at best be employed as the starting-point of a one-year production process, and so on. In so far as the above-mentioned fact can be supposed to be generally applicable, the technical superiority of present productive forces (labour or natural forces) over future ones is proved.
This theory is, however, somewhat more amply constructed than the older productivity theory (Thünen’s), which simply refers to the fact that by sacrificing, for instance, a hundred present units of goods, the future production can be increased by more than a hundred units of goods of the same kind.16 Fundamentally, however, both theories are identical, and the agreement even becomes complete when Böhm-Bawerk arrives at the question: Why have present consumption goods, too, an advantage over future consumption goods ?
Here, too, Böhm-Bawerk tries to formulate his explanation slightly differently. He says (Positive Theorie, p. 287): ‘Command over a sum of present consumption goods provides us with the means of subsistence during the current economic period. This leaves the means of production which we have at our disposal for just this period (labour, uses of land, capital-goods) free for the technically more productive service of the future, and gives us the more · abundant product attainable by them in longer methods of production. On the other hand, of course, command over a sum of future consumption goods leaves the present unprovided for, and consequently leaves us under the necessity of directing the means of production that are at our command now, wholly or partially to the service of the present. But this involves curtailment of the production process and a correspondingly diminished product. The difference in the two products is the advantage associated with the possession of present consumption goods.’
But this is immediately clear only when it is a question of the production of consumption goods of precisely the same kind as the ones at our disposal. Otherwise it will always be open to doubt whether, just because of the more abundant future production of the goods (A) in question, their value, as compared with the value of the consumption goods (B) available before, will not be so greatly diminished that finally it will be of no consequence whether this sum of (B) is available now or in future. This difficulty vanishes when it is merely a question of the production of consumption goods of the same kind—but here we find ourselves in the very midst of Thünen’s productivity theory.
Böhm-Bawerk himself, however, did not, or could not, remove the objection which he directed against this theory in the first volume of his book—namely, that it explains at best the physical, but not the value production of capital. For the demand which he there makes of the productivity theorists was, after all, not to explain why present goods are higher in value than future goods of the same number and kind according to the present valuation—this (in so far as the above-mentioned fact is generally true) Thünen’s theory certainly explains as well as his own theory, though in a somewhat more concise manner—but why the product of capital, when it becomes due, should be more valuable than the sacrificed capital commodity itself. But Böhm-Bawerk has not explained this either; and it can after all only be explained if one sets out from the assumption of a nearly stationary position of economy.
Nor has Böhm-Bawerk answered, by his explanation set forth above, his further main objection to the productivity theory: Are the surplus values or surplus products obtained by the use of capital really added to the capital itself, or do they perhaps fall to the share of the other contributing factors of production, labour, landed property, etc.? It may be true that more future products can be produced with a present working month than with a next year’s working month. But will this surplus benefit the possessor of to-day’s working month without more ado? That is not clear in itself (for nothing can be produced at all with working-time alone and without the use of the forces of nature). It is also not generally true, because the share which belongs to the different factors of production depends entirely on the position of the market. This no one has shown more clearly and finely than Böhm-Bawerk himself in the later parts of his work.
But in the discussion of this problem one is always obliged to assume an approximately stationary economy as the simplest and fundamental case, and as soon as this assumption is made, his objections to Thünen’s theory answer themselves.
Another question which requires to be answered is why this stationary condition, or what comes to about the same thing here, a society in which there is only a slow progression, can be assumed as a rule in theory as well as in practice, and why the incomes of capitalists, landowners and workers are on the whole consumed instead of being hoarded and added to the stock of capital. And although this question is closely connected with the problem of interest, it remains nevertheless a question in itself. In my opinion, Böhm-Bawerk must be blamed for having mixed up the two questions of the origin of interest and the origin of interest-bearing capital itself—in his criticism of the older theories of interest as well as in his own positive presentation—instead of separating them in a truly scientific manner.
And finally a word ought to be said about the Use theory. As is well known, this theory sets out from interest on durable goods, conceiving interest as the price for the use of the commodity during a given time. If the commodity is subject to wear and tear, interest is conceived as the price of its net use; since trouble and labour, necessary for the replacement of the wear and tear which has taken place, are subtracted from the utility of the simple use of the commodity. Whether the value of the commodity remains unchanged in this case and whether the commodity really possesses a capital-value which could be compared with the value of the useful services themselves, remains unsettled.17 It is merely assumed that the commodity keeps its substance, so that it can yield identical useful services in the future also. Once we have adopted this terminology, it is, in my opinion, no fiction, but a scientific generalization, if these concepts of use and net use respectively are extended to cover consumable goods as well. In the case of durable goods, too, it is, after all, of no consequence whether the wear and tear amounts to more or less, provided only they are replaced by continuous repairs. But then the wear and tear can, as in the case of consumable goods, finally extend to the whole commodity, provided its use includes the repair or reproduction of the commodity itself or of an identical commodity. If now this use consists precisely in the acquisition of goods of the same kind as the capital commodity concerned, then obviously a rate of interest is hereby already determined (an element in the determination of the average rate of interest), which can lead retrospectively to a higher estimate of the capital-value of durable goods.
This view can be regarded as more or less satisfactory and scientifically fruitful. To explain it as depending merely on delusion seems to me unjustified. And when Böhm-Bawerk18 finds it ridiculous that the Use theory should presuppose the possibility of ‘transferring to someone a little more than the whole of something, that is to say, transferring along with the possession of the loaned object, the right to each and every use which is to be got from the object until it is completely used up, plus a separate fragment of use for which interest can be separately demanded,’ then the answer is simply, that interest is not demanded or given for some ‘separate fragment of use’ but in fact ‘for every scrap of use which is to be got from the article’—use, that is to say, which is only compatible with the repair of the article itself or its replacement by an identical one.19
The mode of explanation of the Use theory (and of the productivity theory) is only excluded in the case of the pure consumption loan. This case is to be understood, rather, from the point of view of an exchange between a present and a future commodity.20
Böhm-Bawerk’s formula is thus undoubtedly the most general of all. It brings out better than the earlier explanations the true essence of the matter, namely the economic significance of time, and it adapts itself quite as well as any other mode of explanation to the different phenomena of interest. This formula consequently represents, in my opinion, an important scientific advance—more, however, in the sense that it supplies what was missing in the older explanations than in the sense that it substitutes for possibly false or meaningless ideas a completely new and altogether true interpretation, as, to be sure, Böhm-Bawerk himself on more than one occasion states.
3—The period of production. Capital-goods and ‘rent-goods’
The main significance of Böhm-Bawerk’s theory lies, however, in my opinion, in the masterly way in which the role of capital in production is discussed there. In the last analysis this role consists, as has already been said, simply and solely in making possible the introduction of a longer period of time between the beginning and the conclusion of the process of production of the commodity concerned and consequently the adoption of a more productive round-about method of production than would be possible if production were less strong in capital or totally devoid of capital. Consequently, free capital, by its very nature, consists of a sum of means of subsistence, i.e. consumption goods which are advanced to the workers and the owners of the forces of nature by the capitalists during production; that is to say, they are exchanged for labour and services of the land. This sum, however, need not, at any rate at the beginning of production, be kept available; it need only become realizable successively. On an average, however, it is consumed some time before the completion of the work (about half-way through the production). If now at any point of time we take, so to speak, a cross-section of the production, this labour which has been done in advance, and these stored-up services of the land, appear in the form of raw materials, tools, half-finished products, and so on, which represent fixed capital. They are an indication of the length of the period of production. In proportion as these and, consequently, the invested capital, are greater, the proportion of workers occupied in the final stage of production decreases. This smaller number, however, produces a larger quantity of finished goods than the larger number at work during a shorter period of production, and still more than the whole number of workers occupied in production for present use which is carried on without capital. The greater the amount of capital that can be used in the production, that is to say, the lengthier the average period of production that can be applied, the greater will be the annual production of finished consumption goods, provided the same number of workers and the same area of the country are involved.
This is not to say, of course, that all technical advances must necessarily lead to the lengthening of the production processes which were usual before. But in so far as they do not lead to this lengthening, they do not make necessary an increase in the existing capital (or only temporarily). Capital can even be freed in this process. They simply operate, therefore, as if human labour or Nature under otherwise unchanged circumstances had become more productive.
In most cases, however, technical advances will necessitate all kinds of preparatory work; they will lead, that is to say, to new round-about methods of production and so make necessary the formation of new capital. There can be no doubt that in our time an incomparably greater accumulation of capital has taken place than at any time in the past.21
Since, therefore, the relatively definite and very simple concept of the lengthening of the process of production replaces the older, vague, and multiform idea of productivity of capital, the theory of capital-interest can be treated in as exact a fashion as the theory of ground-rent before. As I shall try to show later, both of these together constitute the elements which we shall need if we are to lay down the real factors which determine exchange value.
It is assumed in this case that within every single branch of business, the productivity of labour, for instance, the annual production of one worker, is, under otherwise constant circumstances, a function of the length of the production process—a function which increases with the length of this period but more slowly, so that the scale of the surplus returns becomes a decreasing one—an effect which entirely agrees with experience. Even if we assume that the length of the period of production and the productivity of production are continuously variable magnitudes, we shall still be in the sphere of reality. Sometimes, of course, there are inventions, due to which the method of production usual before is transformed so thoroughly that the length of the process as well as its productiveness becomes quite different. In most cases, however, production changes only gradually. The technical possibility of all kinds of ‘improvements’ is very often already present, but the economic possibility is still lacking: the new ‘labour-saving’ machines or processes were invented long ago, but their application is not yet profitable. It is only when an increase in wages or a decrease of capital-interest has taken place, or because of other reasons, that this application becomes just profitable enough to be adopted—a proof of the fact that in similar cases it is only a question of relatively small changes.22
Certain difficulties stand in the way of this interpretation, however. Some of these Böhm-Bawerk has removed, but not, in my opinion, all. The first is the division of labour which has the effect that, in reality, the whole process of production of any one commodity will practically never be completed by one and the same firm. This difficulty is, however, not one of principle. So long as it is only a question of average capital-interest, wages, etc., we can think of all these partial businesses, in so far as they contribute to the production of the same final product, as being united in one single business. But if we pursue this thought, it soon becomes clear that very often several different businesses meet in one and the same business, either retrospectively or in a future view, or, which is the same, one single business branches out into several. For instance, one and the same factory delivers machines which later will serve for the production of goods of various kinds. It will be difficult or even impossible always to determine exactly how much work, and especially how much labour done in advance, this or that machine has really cost. The average quantity of labour and period of production within each group can be found approximately only if the goods are here divided into larger groups.
Another difficulty is caused by the existence of durable (productive) goods. If these, like tools or machines, only last a few years, it will still be of some help to us that the work necessary to produce the machine is distributed to the goods produced by its aid. In this case the average life of the machine can be regarded as an indication of the average length of the period of production or as part of this. This expedient breaks down, however, when it is a question of production goods which last 50, 100 or more years. Böhm-Bawerk disregards this difficulty. He remarks23: ‘A fraction of a working-day already expended hundreds of years ago, on account of its smallness, is in most cases of no importance.’ But if with him we reckon amongst capital productive buildings, factories, store-houses, railways, etc., which are often very old, then, according to the above conception—after deduction of maintenance and running costs—the interest paid for the use of these capital-goods must necessarily be regarded as remuneration for a part of the work which has gone into their construction in these far-off times. Obviously, however, the original cost of construction no longer has any influence on the present-day level of rent of these buildings or on the freight charges of the railways in question; and if similar work is to be carried out to-day, its prospective returns in some distant future will have just as little significance for its present capital-value or profitableness24—as, by the way, Böhm-Bawerk himself explicitly emphasizes. In my opinion, however, it is precisely because of this that goods of greater durability (such as streets, railways, buildings, etc.) cannot be regarded or treated as capital in the narrower sense, but, once they are there, must be placed, economically speaking, in the same category as landed property itself. In other words, if, in accordance with Böhm-Bawerk’s precedent which we ourselves shall later follow, all existing capitals are united in one sum, in order to use this sum as an element in the theoretical determination of the level of interest and of wages, it would be misleading to think of the capital value of all railways, buildings, etc., as being included in this sum. This value is rather, like the capital value of landed property itself, to be thought of as a secondary phenomenon which has no influence on the determination of the above-named magnitudes. The net interest of durable goods, however, is determined, like ground-rent, simply by the value of their useful services (after the cost of repairs has been deducted).
If, however, we disregard the difficulties which we mentioned first, and if in the meantime we suppose that the services of the land and the use of the other rent-goods are free—the influence of these factors will be considered later—then Böhm-Bawerk in Volume III, Chapter V, of his book has taught us that with the help of the concept of the length of the production period a very simple relationship between the present position of wages and of capital-interest can be laid down, if the number of the available workers within an economy and the amount of the capital are known. Böhm-Bawerk avoids the use of mathematical symbols here and tries to make the matter clear by presenting it in tabular form. But in doing this he is obliged to assume that the magnitudes in question vary discontinuously. Since, however, the assumption of magnitudes which vary continuously in fact corresponds more nearly to reality as well as being simpler in theory, I for my part prefer to take this assumption as fundamental, and shall present the theory in a corresponding mathematical guise. About Böhm-Bawerk’s method of treating these questions, I shall say a few words later.
4—Capital-interest and wages in the stationary economy
A. Mathematical presentation
Let us therefore assume that a group of workers wish to start a productive undertaking on their own account, in which one commodity or a number of goods is produced once. They themselves possess no capital. They can, however, within certain limits, obtain any amount of money on loan at a rate of interest which for the time being we shall think of as given. In order to make the matter as simple as possible, we shall assume that they do all the necessary preparatory work themselves, make the tools, and so on. However, once the production process is complete and the goods are ready, these tools are assumed to be worn out and valueless. The more labour they devote to these preparations for production, the lengthier will be the production process. But, as compensation for this, the quantity of goods produced, or rather their value, will be greater, according to our assumptions; and, what is more, this value must here be assumed to be growing in a greater proportion than the length of the period of production itself; so that the value of the average (i.e. annual or daily) production of a worker is also to be thought of as growing with the length of the period of production (in which case, however, the scale of the surplus profits is necessarily a decreasing one).
If now we ask what method of production or—what is here the same thing—how long a period of production these workers are to choose with most advantage to themselves, this problem, it is clear, remains vague, since the workers can obviously pursue two different aims: on the one hand, they may strive to attain the greatest possible ultimate profit; on the other, they may desire to procure for themselves a subsistence as abundant as possible while the work lasts. But since we still wish to keep the hypothesis of the stationary condition and must consequently regard the sum of the capitals as an invariable magnitude, we can disregard completely the gain which will ultimately result and which would obviously be a new capital.25We therefore assume that the workers, even when they themselves are the entrepreneurs, merely strive to attain the second of these two aims, the greatest possible subsistence or wages. Then the problem is quite definite and very easy to solve.
Let the value of the final product be s. According to our last assumption, we shall find that this value comprises the whole capital engaged in production plus interest on this capital, and no more. But the capital consists here merely of the cost of maintaining the workers and will consequently amount to t. l for each worker, if l stands for the annual subsistence or annual wage of one worker, still to be determined, and t for the length of the period of production expressed in years (and fractions of years). If now the whole capital was borrowed already at the beginning of the production process, then, on the assumption of simple interest and if z stands for the rate of interest, t .l. z . t (or t2 .l. z) must consequently be paid as interest. But if the capital is only invested by instalments, this sum has to be multiplied by some proper fraction, which in the case of a constant taking-up of capital can, it is evident, become as small as ½, and no smaller. We therefore write
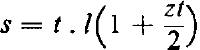
(12)
The value can be taken as the average length of the investment of capital, which therefore need only amount to half the length of the process of production, if the production is constant.
If both sides are divided by t, we have, since  obviously stands for the average annual production of one worker which we shall call p:
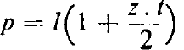
(13)
s and p are here, as has already been said, to be understood as functions and, what is more, as known functions of t ; z is assumed to be a known value; and the task is now to determine t in such a way that l becomes as great as possible. This is done, of course, by means of differentiating on both sides in respect of t, as if l were a constant; since, in the case of a maximum, dl = 0.26 We consequently obtain

(14)
and this equation gives us, together with (13), the values of t and l, expressed in terms of z, which we require to know.
In order to make the understanding of this problem easier, we shall also illustrate this result geometrically. We assume that t and p are abscissa and ordinate of a curve that, according to the known attributes of p, must follow a rising course which, however, is concave in respect of the axis of abscissae and (since something can always be produced, even in production for immediate use which is carried out without any capital) intersects the axis of ordinates at a certain distance from the zero-point. If we take any one point on this curve and connect it by a straight line to a fixed point which lies on the negative side of the axis of abscissae at a distance of  from the zero-point, then this straight line will cut off a section of the axis of ordinates which is equal to l, as follows from equation (13) if it is written in the form
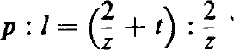
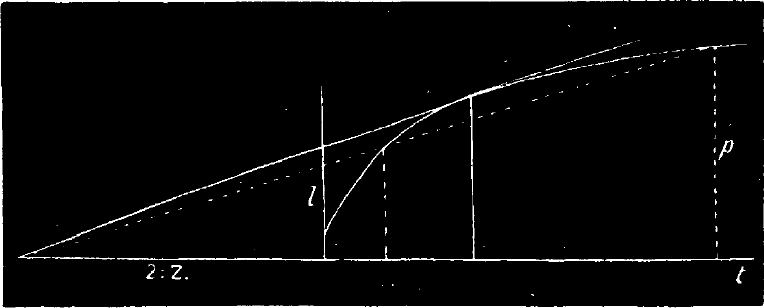
The greatest value of l can consequently be attained, if from the fixed point mentioned a tangent is drawn to the curve. This is just what equation (14) expresses.
Let us now deal with the contrary question. Let us suppose that the wages are given and that an entrepreneur who is himself a capitalist wishes to direct his production in such a way that the greatest possible profit accrues to himself from the capital which he has expended on each of the workers employed and consequently on the whole production. This problem (the only one which Böhm-Bawerk has dealt with) seems at first sight to be quite different from the former, but leads to precisely the same expressions. That is to say, when p and l stand for annual production and annual wages of a worker, we obtain in this case also
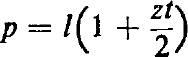
Here, however, l is understood as a known value and our task is to determine t in such a way that z becomes a maximum. But the differentiation in respect of t takes place in both cases as if l as well as z were a constant, and we obtain as before

Using these equations, t and z can now be expressed in terms of l.
The geometrical solution is arrived at in this case by taking a point at a distance l from the zero-point on the axis of ordinates and drawing from this point a tangent to the curve. This tangent now determines on the negative side of the axis of abscissae the length  , which in turn determines the value of z. (If, for instance, the length so determined is 40, z becomes equal to
 or 5 per cent.)
Here it is assumed, however, that the capital is employed only successively. Temporarily, therefore, a use must be found for it outside the business. In order to avoid this difficulty, we could imagine that the entrepreneur carries on not merely one, but several businesses of the same kind at the same time, in all of which the period of production is the same, but which are at different stages of progress, so that the entrepreneur can consequently market finished goods once a month, say, or once a week. The proceeds from these provide him with necessary money for the next payment of wages. Since in this case each of the workers employed has, on an average, half of the production process behind him,27 the average capital invested in each worker obviously amounts to  . But the average monthly production of each worker is
 and the monthly wage
 and their difference
 can be regarded as monthly interest on the capital invested in each worker; so that the monthly rate of interest amounts to
 and the yearly rate of interest consequently amounts to
 and we obtain
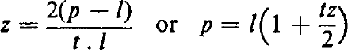
as above.
But it is not necessary to suppose such a rigorously conducted gradation of production within the separate businesses. It is sufficient if this phenomenon appears as the result of the total production This is the same as saying that the different products and half-finished products are produced precisely when consumption and production require them. That is to say, the capital, too, can then find employment through the mechanism of the loan-market just when it becomes free.28
This is more or less the actual state of affairs, or rather it is the ideal towards which production continually strives. But this ideal, for several reasons, can only be partly attained.
It was, by the way, assumed in what has just been said, that production is itself constant, so that at each moment of production the same number of workers is employed. This, too, is of course not the case. At certain stages of production there is perhaps room for very few workers or for no workers at all—when, for instance, the goods in process of production are simply exposed to the action of natural forces; for example, when ripening grain continues standing in the fields throughout the summer, or when, in the production of wine, after the completion of the actual production, the new wine remains lying in the cellar, perhaps for years. Finally, the period of production ought actually to be thought of as lasting until the finished goods are in fact sold.
Still, we shall allow for all these facts if we put the general expression €. t (where € is a proper fraction) instead of  for the length of the investment of capital.
It is clear that in this case the gradation of production within the particular economy must at least be carried to the point at which the workers employed find uninterrupted occupation. Our equation (13) can then take the form
p = l(1+ € . t .z)
The distribution of labour over the period of production can itself be altered, however, and e is therefore in reality a variable quantity. The product € . t, that is to say, the investment period of the capital, can here, however, be conceived as a single variable, so that the expressions undergo no essential alteration, at least when calculating simple interest.
If now, within the branch of the business in question, the total existing capital and the total number of workers employed were each a constant magnitude, we could find out not only the above relations between wage, level of interest and length of the period of production (which, to be sure, can be assumed to be equal practically everywhere within this branch of the business), but even these magnitudes themselves. That is to say, since the capital invested in each worker is, on an average, (or more generally €. t.l), we obtain
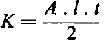
(15)
when K stands for the total capital and A for the number of workers employed. Using this equation in combination with the equations (13) and (14), we can express l, t and z in terms of K and A. We obtain, in fact, from (13) and (14), by eliminating z,
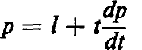
(16)
and if the value of l obtained from the above equation is substituted in (15), we get
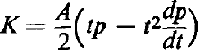
(17)
This equation can be solved for t, since p and  must be thought of as known functions of t; and so forth.
This assumption, however, will not do. Capital and labour which are to-day employed in the manufacture of goods of a certain kind, can to-morrow have been partly transferred to other branches of business. Within the whole economy, however, the number of available workers and the total capital can be regarded as approximately given magnitudes. If, therefore, following Böhm-Bawerk’s precedent, we may assume as a first approximation within all branches of the business the same productivity and the same increase in productivity when the length of the period of production is increased, then, obviously, our equations set forth above can be regarded as valid for the whole economy, since t stands for the length of the period of production, p the yearly production of one worker, and l and z the wage and the level of interest. According to our assumption, these values must be the same in all the businesses.
Indeed, in practical life the fulfilment of these equations would take place in the following way. At each level of wages a period of production of a certain length proves to be the most advantageous to the entrepreneur-capitalists, since it promises the greatest possible interest (makes z a maximum). If in this case all the workers find employment and the whole of the existing capital is invested, these proportions will undergo no further change: equilibrium on the capital-labour market has been reached. But if more labour is demanded than is available, wages must rise. At the new level of wages a new and, what is more, a longer period of production proves at once to be the most profitable, as is evident, and the superfluous capital is absorbed partly by the rise in wages, and partly by the lengthening of the period of production.
If, on the other hand, more labour is available than can be employed during a period of production of the length in question, wages must fall, owing to competition of the workers. At this lower level of wages a new and, what is more, a shorter period of production recommends itself as the one which is now most profitable to the capitalists. This is adopted, and the capital which was before insufficient is now able to give employment to all workers, partly owing to the decrease in wages, but partly also to the shortened period of production.
In both cases equilibrium is finally achieved, although only after several oscillations in this and that direction; and in the case of equilibrium all our above equations are fulfilled.
If, on the contrary, we had set out from the assumption that the workers are themselves entrepreneurs, the result would have been the same—with this difference, however, that supply and demand now occur on the loan market, so that the rising or falling rate of interest now takes the place of increasing and decreasing wages.
In both cases the equations of equilibrium will be the same, and, what is more, a large amount of capital and a comparatively small number of workers will always be connected with a longer period of production, high wages and a low rate of interest—and vice versa. That is to say, when the capitalists are entrepreneurs, the lengthening of the period of production is seen to be a reaction on the part of the capitalists against the increase in wages which has taken place and the low rate of interest which results therefrom. But as a result of this lengthening of the period, interest can again be raised to some extent, but cannot reach the level achieved in the case of the previous lower level of wages.
If, on the contrary, the workers are entrepreneurs, and the rate of interest, due to increased demand for capital, has risen, the workers will shorten the period of production, and by this means once again be able to improve to some extent their incomes (i.e. wages), diminished by the rise in interest. But neither wages nor interest can in this case return to quite the former position.29
The question could be asked, how far the above result is affected by the existence of people who work with their own capital. This question is, however, easily answered. If such a worker has enough capital to observe (in the case of steadily-flowing production)30 the usual period of production, then he will select just this period (always supposing that his purpose is merely to conserve his capital and not to increase it). If he has less capital, he must adopt a shorter period of production; if he has more, then he can, if he so desires, adopt a longer period. In both cases, however, he will obtain a greater income if he chooses the customary period of production. In order to do so, he will, in the first case, procure the capital which he still requires by means of a loan at the ordinary rate of interest, and in the second case he will lend the superfluous capital or use it to employ other workers. For the validity of our formulae it is therefore of no consequence whatever who possesses the capital, provided only that the latter is employed as capital.
Here, however, I must draw attention to a certain ambiguity in the problem, which was not taken into consideration by Böhm-Bawerk and which I in my criticism of his presentation (in Conrads Jahrbücher, December 1892) had not yet noticed.
One could imagine capitalists adopting longer and longer periods of production in a quite haphazard way, wages being in this case determined every time by the competition of capitalists and workers according to equation (15),
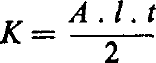
The interest attained is still given by (13),
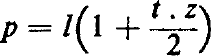
but since l is now no longer regarded as a constant but depends, according to (15), on t, it follows that when we try to determine t in such a way that z becomes a maximum, we are led (as can easily be seen) not to equation (14) but to the quite different equation

Since l and t are essentially positive, would have to be negative here ; that is to say, supposing the length of production is increased more and more, the greatest possible interest will only be attained when the scale of productivity (the annual production of one worker) has changed into a decreasing one. Practically speaking, no real maximum of the rate of interest consequently exists here, but each lengthening of the period of production will be advantageous to the capitalists.
This result may seem strange, but is not difficult to understand. What we have been considering above was the case of free competition, where everyone pursues his own advantage. But our last assumption presupposes that capitalists combine to depress wages and that the workers can do nothing about this. But then each lengthening of production will prove in the end to be remunerative, provided it is undertaken simultaneously in all businesses; since the wage-capital available for each year is diminished and wages must consequently fall. Even if the productivity of one worker remains unaltered or even undergoes a slight decline, it will still be remunerative. In this case, of course, the fall in wages will sooner or later cause, somehow or other, a drop in the number of workers within the economy, or the workers must be partly supported by charity. But if this point has not yet been reached, it will always be in the interest of the capitalists as a class to extend the period of production.
But the situation is different if there is free competition between the capitalists, because in this case the low level of wages will be a temptation to every individual capitalist to shorten the period of production and to use his capital for the employment of a greater number of workers. But if several capitalists do this, wages will, of course, rise.
On the other hand, by sticking together, workers can, within certain limits, undoubtedly enforce a shorter period of production if, for instance, they refuse to work with the new ‘labour-saving’ machines. As a result of this, wages will rise—if, of course, we assume that the capital remains undiminished in spite of the lower rate of interest. But if there is free competition amongst workers, this reduced rate of interest will, for some workers, be a temptation to become entrepreneurs themselves—and, what is more, according to the lower level of interest—by adopting longer periods of production. And so the demand for capital would again become greater, etc. We cannot pursue this subject further here. However, what has been said will suffice to show that the new concept ‘period of production’ seems destined to bring order and clarity to some of the most complicated problems of political economy, problems which are far from being explained.
B. Böhm-Bawerk’s presentation and his ‘positive’ law of interest. His criticism of Jevons’s theory of interest
The above-mentioned presentation is substantially identical with the theory to which Böhm-Bawerk has devoted the last chapter of his book. But this theory obviously contains merely an element of a complete theory of interest, because, on the one hand, the services of the land (actually the services of all rent-goods) were left unconsidered, and because, on the other hand, the theory assumes that there is an identical productivity and scale of productiveness for all branches of production—which is very far from reality. In what follows I shall try to replace this theory by another, which is complete in both these respects; and in this way I hope, in the end, to be able to take up again our problem of determining the exchange value, which was not brought to a conclusion in the previous chapter.
First of all, however, I shall go a little more deeply into Böhm-Bawerk’s treatment of this problem, in order to emphasize once again the great importance of this theory, but also because of several remarks which he makes, as it seems to me that his reasoning there does not hold good in all points.
Böhm-Bawerk lays down as an hypothesis an invariable pattern, which is supposed to represent the productiveness of production when, for instance, a period of production of one, two, three, etc., years is adopted. After this he shows how, assuming different levels of wages, now this and now that period of production yields the highest interest on the capital which has to be invested in each worker. I reproduce here one of the relevant tables. This corresponds to just the level of wages, 500 fl., which would prove absolutely right for the number of workers and amount of capital chosen in this example.
| Level of wage 500 fl. | ||||
| Period of production | Product of one working-year | Annual profit per worker | Number of employed | Total annual profit on each 10,000 fl. |
| 1 year | 350 fl. | – 150 fl. | 40 | (Loss) |
| 2 years | 450 „ | – 50 „ | 20 | „ |
| 3 „ | 530 „ | 30 „ | 13.33 | 400.00 fl. |
| 4 „ | 580 „ | 80 „ | 10 | 800.00 „ |
| 5 „ | 620 „ | 120 „ | 8 | 960.00 „ |
| 6 „ | 650 „ | 150 „ | 6.66 | 1,000.00 „ |
| 7 „ | 670 „ | 170 „ | 5.71 | 970.70 fl. |
| 8 „ | 685 „ | 185 „ | 5 | 925.00 „ |
| 9 „ | 695 „ | 195 „ | 4.44 | 866.66 fl. |
| 10 „ | 700 „ | 200 „ | 4 | 800.00 „ |
The first three columns require no explanation. The fourth column shows the number of workers that can be employed with a capital of 10,000 fl. in a period of production of 1, 2, 3, etc., years respectively; in which case it is assumed that the advance of capital amounts to only half the sum of wages paid during the period of production—as will really be the case if there is an appropriate ‘gradation’ of production and payment of wages. If, therefore, the period of production is χ years, the figures in this column are determined by the formula
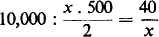
The fifth column can now be obtained by multiplying the appropriate figures of the third and fourth columns. Its figures give, therefore, for each year, the profit on 10,000 fl., or, divided by 100, the level of interest, expressed in percentages.31
From this table we see that, when the rate of wage is 500 fl., the adoption of a period of production of six years will yield the highest interest on the invested capital, i.e. 10 per cent, whilst a period of five years would yield only 9-6 per cent, and a period of seven years only 9-7 per cent. This depends entirely, however, upon the level of wages. In the same way we see that, at a rate of wage of only 300 fl., and under otherwise identical circumstances, a period of production of only three years would prove the most profitable, and the capital would even yield interest at the rate of 51 per cent. At a rate of wage of 600 fl., on the other hand, a production period of eight years must be selected, ‘which will yield the modest, but still advantageous interest of 3 · 54 per cent.’32
If now—as the author for the sake of argument supposes—a national capital of 15,000 million gulden and 10 million workers are available, then, at a rate of wage of 500 fl. and with the correspondingly most advantageous production period of six years, the market will be in equilibrium. In other words, the existing capital will be just sufficient to keep all these workers fully occupied (and vice versa), since
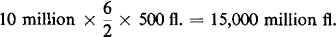
And this state of equilibrium will necessarily also arise of its own accord through the competition of workers and capitalists. If, that is to say, wages were somewhat higher, i.e. 510 fl., then the six-year production period would still be the most remunerative. However, with the existing capital of 15,000 million fl., only 9,800,000 workers could be employed, ‘and the unemployed remainder, by creating a situation in which supply far exceeds demand, would exert pressure on the price of labour, until such time as they themselves can be, and are, employed’; which can only happen at a rate of wage of 500 fl. (This superfluity of workers shows itself, of course, in a much more marked degree when the rise in the rate of wages leads also to a lengthening of the period of production, which in our example will only be the case when the rate of wages is 530 fl. or more. It will, however, always by the case if we assume a continuously variable period of production.) If, on the contrary, the wage were a little lower, say 490 fl., then only 14,700 million fl. capital would be taken up by the employment of the existing 10 million workers. The unemployed remainder would then obtain employment through overbidding, and the result would again be a rise in wages which would continue until the point was finally reached at which everything can and does come into equilibrium.
So far everything seems to be correct.33 The agreement with our formulae set forth above will be clear to every mathematically-trained reader. Strange to say, however, Böhm-Bawerk believes that he has found in the series of numbers which he has set down ‘other relationships as well, which in a positive (?) way point to the resulting rate of interest of 10 per cent and which can provide the material for a positive law of the level of interest.’ I reproduce here literally what he has to say on this subject.
“To arrive at the position of equilibrium, the capital of the community had to be withdrawn from the shorter processes of production, in which full employment could not have been found for it with the existing stock of labour, and employed in gradually lengthening processes, until it was fully occupied. This happened in a six-year period of production. On the other hand, the adoption of still longer processes, for which the capital would not have been sufficient, had, economically, to be prevented. In these circumstances the producers who adopt the six-year period of production are the last buyers, the ‘marginal buyers’; the producers who would like to adopt a seven-year period of production are the most capable excluded suitors for means of subsistence; and, according to the well-known law, the price that results must fall between the subjective valuations of these two. How does it stand with the valuations?
“What we have to consider is simply this: What is the utility which, for these two sets of buyers, depends on the disposal over a definite sum of means of subsistence? First of all, the general assertion must be made, that on the disposal over each half-year’s wage—in the present case 250 fl.—depends one year’s extension of the production period per worker.34 Thus the ability to embark on or continue in the six-year, instead of the shorter five-year period of production, employing one labourer, depends, especially for the producers who adopt the six-year period, on the possession or non-possession of 250fl.; and since, according to our scheme of productivity, the year’s product from one worker in a five-year production period amounts to only 620 fl., whereas in a six-year period it amounts to 650 fl., the attainment of an annual surplus product of 30 fl. depends, for the marginal buyers, on their having at their disposal 250 fl. On the other hand, those would-be producers who try to take means of subsistence out of the market, in order to extend the production period to seven years even, could gain by this extension only a surplus return of 20 fl. (670 − 650 fl.) . . .
“If, therefore—and this is indispensable to the attainment of equilibrium—the extension of the production period is to halt at the limit of six years, the agio established by the fixing of the price (i.e. the interest) must lie between the rate that corresponds to the valuation of the last buyers (30 fl. on 250 fl., or 12 percent) as upper limit, and the rate of 8 per cent, corresponding to the valuation of the competitors first excluded, as lower limit. . . . The fact that, within these bounds, a rate of interest of 10 per cent was precisely indicated, is, of course, no longer due to the limiting effect of the valuations of the marginal pairs, but, as described on p. 226 ff., simply to the quantitative effect of supply and demand.”
All this sounds very clear and convincing, to be sure. But, when we look at it more closely, it unfortunately no longer seems clear. How could a surplus return of 30 fl., i.e. a net profit of 12 per cent, depend, for the producers who have adopted the six-year period, on their having the disposal over 250 fl. ? we are obliged to ask ; since at the assumed rate of wage of 500 fl. the capital can, at most, yield an interest of 10 per cent! And vice versa: if they can obtain this net profit, why should ‘supply and demand’ depress the interest which has to be paid to only 10 per cent? This could only occur if the capital sufficed for more than a six-year period, which, however, was not the case. But as a matter of fact a net profit of only 25 fl., or just 10 per cent, depends, for the producers who wish to go over, at the rate of wage mentioned, from the five-year to the six-year period, on having at their disposal 250 fl. ; the remaining 5 fl. of the surplus return are due to the fact that their capital, which was already employed before, and which in the five-year period amounted to 5 x 250 fl. per worker, is now employed in a six-year period of production where it now yields 10 per cent instead of only 9·6 per cent. For 5 x 250 fl. it consequently yields 125 fl. instead of 120 fl.
And this increase of profits they could obtain in any case, even without having new capital at their disposal, if they only decreased the number of their workers in a corresponding proportion.
Likewise, an added capital of 250 fl. would yield, when changing over to a seven-year period, not only 20 fl., but more than 24 fl. But at the same time the capital which was previously employed in the six-year period will have to be content with an interest of only 9-7 per cent instead of 10 per cent.
It is, therefore, certainly true that interest, calculated for half the level of wage, comes to lie ‘between the surplus return of the last permissible extension of production and that of the no longer permissible extension of production’; but between these limits its definite level is not determined by supply and demand but simply by the productiveness of the most profitable period of production. Whether in this case wages will really remain at the assumed rate or can be kept there, will depend on the supply and demand situation with regard to labour. This, however, is quite a different question.35
The idea of regarding the ‘producers who adopt the six-year period of production’ as ‘the last buyers,’ etc., must be regarded as altogether wrong, for, at the rate of wage in question, everybody will choose this period, and neither a longer nor a shorter one. It would, indeed, not be impossible to conceive the present problem also as one which involves an exchange between present and future goods—with this reservation, however, that the exchange is an alternative one, in that the length of the period of production to be chosen influences the quantity of the future commodity (the average annual production) as well as that of the present commodity (namely the wage-capital to be employed in the present year). But we shall not dwell longer upon this.
When the length of the process of production can be changed by indefinitely small steps, as is for the most part really the case in practical life, the productiveness of the last small step that can actually be taken, and the productiveness of the step which is just out of reach, approach each other closely. Böhm-Bawerk therefore believes that he is able ‘to formulate the law of the level of interest in such a way that this level is determined by the surplus return of the last still permitted extension of production’; and in his controversy with Jevons (p. 427, note) he remarks that ‘the level of the rate of interest is to be deduced from the relation of the last surplus return to the sum of subsistence which allows the last extension of production.’
Without further qualification, however, the last statement is misleading. The words ‘at an unchanged rate of wage’ need to be added to it, and the word ‘allows’ should be replaced by ‘brings about’ or some such phrase. But then this statement simply expresses a consequence of the fact that the highest possible level of interest is already reached, and throws no further light on the nature of interest. One could, however, be led by the wording of the sentence to believe that, if an increase in the national capital leads to an extension of the period of production, the number of workers remaining the same, then the surplus return obtained through this extension, divided by the capital increase in question, will give us approximately the level of interest. This would be decidedly wrong. The result of this division sum is, as we shall see, always smaller than the interest and, what is more, it is smaller by a finite amount, even when it is a question of a minimum change. This is connected with the fact that this increase in the national capital is accompanied by an increase in wages which partially swallows it up, with the result that the lengthening of production actually achieved always falls short of the lengthening of production possible when the rate of wage remains unchanged.
With the help of the equations which we used before, this can be shown quite easily, and further relationships between the values occurring here, which might not be without interest, can be stated.
If p is replaced by F(t) and  by F’(t), then, generally speaking
F(t) − F(t − Δt) > F’(t)Δt > F(t + Δt) − F(t)
since F(t) is an increasing, and F’(t), on the contrary, a decreasing function of t. Here Δt stands for a small quantity of time. Now, according to (14), when the level of interest reaches a maximum,

We therefore obtain for the corresponding value of t
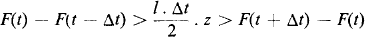
In this inequality Böhm-Bawerk’s rules stated above find expression, since an extension of the period of production amounting to Δt requires a new capital investment per worker of  .36
In the case of a given national capital and a given number of workers, the length of the period of production and the wage are found, as we have seen, by means of the equations

(15)

(16)
and
in which p’ replaces dp: dt. The rate of interest proper to them is then given by one or other of the identical expressions
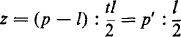
If, however, the total capital is slightly increased, whilst the number of workers remains the same, a new state of equilibrium is reached, with a change in the level of wage and in the length of the period of production; with the result that, when K becomes K + dK, l is changed to l + dl and t to t + dt. The relationships between the quantities dK, dl and dt are found simply by differentiation of the above equations (15) and (16), namely
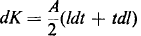
(18)
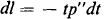
(19)
and
where p” is written for  . We shall now apply these equations in various ways.
The annual production p of one worker undergoes, when t becomes t + dt, the increase dp or p’dt; the total surplus return is consequently A. p’dt. If we want to find out the proportion of this quantity to the increase in the national capital, we obtain from (18) and (19)
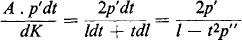
Since p” is always negative, the latter expression will always be smaller than  —that is to say, smaller than the rate of interest, as I have remarked above.
In the case of a relative increase of the national capital the wage increases and the level of interest decreases. This circumstance is generally explained by the fact that, with increasingly capitalistic production, the workers’ share in the result of the production becomes greater and greater, whilst that of the capital becomes smaller and smaller. This, however, is not unconditionally true. It might very well happen that the workers, although they now have higher wages, nevertheless obtain a smaller share in the production, since its productiveness has in the meantime increased; or—which is the same thing—the share of the capitalists might be greater, although this share amounts to a smaller interest on the capital, which in the meantime has increased. In order to be able to decide whether this is really the case or not, we must see whether the expression  increases or decreases when t increases, that is to say, whether

is positive or negative.
Taking into account the equations (19) and (16), this expression becomes
-tp” . p + t(p’)2 − p’ . p
The first two terms of the expression are positive (since p” < 0); the third term, on the contrary, is negative. In certain circumstances, therefore, the sum of the three terms can be positive or negative.
For example, at a rate of wage of 280 fl. a two-year period of production would be the most remunerative (if we base our calculations upon Böhm-Bawerk’s figures). At a rate of wage of 300 fl., on the other hand, a three-year period would be the most remunerative. The annual production of one worker in the two-year period was 450 fl., in the three-year period, on the other hand, 530 fl. Now 280 : 450 > 300 : 530. If, consequently, the period of production is here extended from two to three years through a corresponding increase in capital, the share of the capitalists in the production increases and the share of the workers decreases, in spite of the fact that the wages have risen and the capital-interest has decreased. If, on the contrary, it is a question of periods of production of greater length, every new extension of the period of production will, in general, diminish the share of the capitalists and increase that of the workers.
But, finally, the question could be raised, to what extent the net profit of the capitalists—in the absolute sense—will, in fact, increase when the capital is increased and the period of production is extended. This is obviously a question of the greatest practical significance. If, that is to say, an increase in capital merely helped to diminish the profit on the capital, then such a capital increase would conflict with the interests of the capitalists as a class and would probably be prevented in some way or other. On the other hand, every increase in capital is, of course, advantageous to the workers. The result would be that the interests of the capitalists and the workers, which in this respect hitherto went hand in hand to some extent, would now clash.
The yearly profit on each worker was p’ − l. When t becomes t + dt, this quantity undergoes the change
d(p − l) = p’dt − dl
or, taking into account (19),
= (p’ + tp”)dt
The solution of our problem consequently depends on whether the latter expression is positive or negative, p’ is positive; p”, on the contrary, is negative. If now p” (taken positively) is very small, that is to say, if p’ is approximately constant, so that each extension of the period of production yields nearly the same surplus return, then the expression becomes positive. Every extension of the period of production and every increase of the national capital will then increase the net profit also (although, of course, not in the same proportion as the capital itself increases). If, on the other hand, p” is relatively big, that is to say, if p’ decreases rapidly, then the expression becomes finally negative: the surplus return of the extended period of production is more than counterbalanced by the increase of wages.
If we suppose that p increases with t in a logarithmic proportion, so that p = α + β log nat t, where α and β are constants, then  and
 ; we therefore now have for every value of t
p’ + tp” = 0
The net profit, then, remains constant, even if the period of production is lengthened to a very great extent by continuous formation of capital: a national capital of 15,000 million fl. does not yield more than a capital of 1,500 or even of 150 million fl.—provided the number of workers is always assumed to be unchanged. But if ρ increases in a greater proportion, then, in the case of an extended period of production, the net profit increases also. If, on the other hand, ρ increases in a smaller proportion,37 then the absolute net profit decreases with every new increase of capital and lengthening of production. If we base our calculations on the figures of productiveness given in the table, we see, for instance, that if the capital increases from 15 milliards fl. to 19¼ milliards fl., then, at the new rate of wage of 550 fl., the seven-year period would prove to be the most profitable one. But the annual profit from each worker would then amount to only (670 − 550) = 120 fl. instead of the 150 fl. obtained before, and the total net profit would, of course, diminish in the same proportion.
The figures in the table are, to be sure, only examples, but the decreasing scale of surplus returns which characterizes them may be regarded as a well-established fact or, rather, a matter of course. Sooner or later, if the formation of capital is continued and if the population remains relatively unchanged, the point must therefore be reached, at which the increasing capital is not only accompanied by a fall in the rate of interest, and not only has to be content with a smaller quota of the total production, but even leads to a smaller amount of the total profit; so that every new accumulation of capital directly damages the capitalists—always assuming, of course, completely free competition of capitalists.
As is well known, Thünen had already laid down a law of the level of interest, analogous to his familiar proposition which stated that the average wage38 depended on the ‘yield of the last worker.’ According to this law, the level of the rate of interest depends on the productiveness of the ‘last invested particle of capital.’ The agreement of this theorem with Böhm-Bawerk’s own is obvious and is rightly emphasized by the latter. Only it must be remembered that here it is always a question of the capital investments of the individual entrepreneurs only, in which case the wage can and must be assumed to be given.39 This theorem can by no means be applied to the increase in the national capital itself and to the surplus return brought about thereby.
Jevons in his Theory of Political Economy (2nd edition, p. 266) sets out from somewhat different considerations, in order to arrive at a general formula for the level of the rate of interest. Jevons supposes that, when the actual production is completed, the value of the product goes on rising for a while (for example, through its being exposed to the influence of the free forces of nature, as wine lying in the cellar; or because the sale conditions have improved in the meantime). So then the increase in value, taking place at each moment of time, can be thought of as the natural interest on the value which the product possessed at the beginning of this moment of time. If, therefore, F(t) denotes the value of the product after a certain length of time t has elapsed, and F’(t) stands for its derivative, the level of this interest is expressed by the following equation:
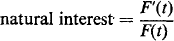
Under the assumptions which Jevons makes, this formula is not incorrect, but it is still rather meaningless, for it says nothing about the way in which this natural, continuously variable rate of interest becomes the decisive factor for the interest actually gained. In Jevons’s works the problem of the increase of the rate of interest to a maximum, and the relationships between interest and wages, are nowhere discussed.
However, the above-mentioned formula could also quite well be chosen as a point of departure, and is even the most natural starting point if we wish to take compound interest into consideration. But in this case, if it is a question of a continuous production, the labour element and wage element which have been added in each case must be taken into consideration too.40
Böhm-Bawerk, as can be seen from his criticism of Jevons’s theory (Positive Theorie, p. 427, footnote), has completely misunderstood the latter’s train of thought, and reproaches him without reason for an ‘error’ or an Oversight in principle.’
The ‘concrete example’ which Böhm-Bawerk uses to illustrate the ‘bearing of this oversight’ is badly devised and shows that Böhm-Bawerk, as was pointed out before, has himself not arrived at a perfectly clear understanding of the necessary conditions of the problem. He says: ‘Let us suppose the case of an entrepreneur whose means would allow him to carry through an eight-year production period with a yearly return of 685 fl., who, by a loan of 300 fl., which would guarantee him subsistence for a ninth ( ?), is put in a position to go over to a nine-year production period with a return of 695, or a surplus return of 10 fl. According to Jevons, the rate of interest here should be 10 : 685, or 1-46 per cent. But clearly there is no reason whatever why the suitor for the loan should be ready to offer 10 fl. per year and no more as interest for a sum of 685 fl. It is not the sum of 685 fl., but that of 300 fi., acquisition of which makes the extension of production possible,’ etc. According to Böhm-Bawerk, ‘an interest of 10 fl. on 300 fl., i.e. 3⅓ per cent—or even, assuming a steadily-flowing production, a rate of 10 fl. on 150 fl., i.e. 6⅔ per cent—would be economically possible.’
It is obvious that Jevons has been misunderstood here. But, what is more, where does Böhm-Bawerk get his figure of 300 fl. from? How does he know that the entrepreneur, who before used to earn 685 fl. a year, will be content for a whole year with the very small subsistence of 300 fl. ?
In fact, the problem is unsolved so long as it is not known how much of his income the entrepreneur in question is accustomed to save. The simplest hypothesis is, however, that he does not save anything, but merely preserves his existing capital, that is to say, creates it afresh from period to period. But then his yearly subsistence and the average yearly return from his production (when he only works with his own means) are simply identical magnitudes; for his investment of capital would then merely consist in the fact that he supplies himself with his own subsistence while the work lasts; and in the final product he gets back the value of this amount of means of subsistence, neither more nor less. In the case of steadily-flowing production only half the sum of subsistence is necessary as capital. Consequently, for a one-year extension of production, an increase of capital of 685 : 2 = 342½ fl. is necessary. But for this sum he will be able to pay at most 10 fl. per year as interest ; so that at the very best a rate of interest of 2·92 per cent is ‘economically possible’ under the assumptions here made.
Instead of this simplest hypothesis, we could, of course, make any other assumption about the dispositions of this entrepreneur in general. But if no definite assumption of this kind is made at all, the whole problem obviously lacks a solid basis.
C. Böhm-Bawerk’s theory and the wage fund theory
After my efforts to give to Böhm-Bawerk’s presentation greater precision and to clarify what is obscure in it, I should like to draw attention once again to the great importance of his theory. As the author himself has explained, this importance consists partly in the fact that in this theory for the first time a real substitute is provided for the obsolete wage fund theory, which several writers have tried to overthrow by cheap criticism without being able to replace it by a better.
The wage fund theory, as is well known, represented the wage as equal to the results of dividing the capital destined for the payment of wages by the number of workers. Now it was pointed out with good reason by the opponents of this theory, that the first of these magnitudes is from the very start completely undetermined. For from the very first it is uncertain how much of the existing national capital will be used productively; nor will the whole of the capital used productively be paid out as wages. Rather, it is more or less ‘permanently’ invested in buildings, machines, tools, raw materials and half-finished products of all kinds.
The first objection applies equally well to Böhm-Bawerk’s theory and can only be removed by a comprehensive theory of savings and capital formation. As for the latter objection, it was clear from the beginning that the actual division of productive capital into means of labour and means of subsistence (into, shall we say, fixed and variable capital) is not arbitrary, but takes place according to the principle of the greatest possible profit ; but no one has been able to say anything more definite on this subject. This gap has now been brilliantly bridged by Böhm-Bawerk’s theory, which introduces the length of the period of production as one of the factors of the problem and replaces the vague ‘wage capital’ by the whole national capital, which is relatively definite.
Let us now return to mathematical language. While, according to the wage fund theory, the relationship between wage, number of workers and ‘capital’ is expressed by the equation

which leaves nothing to be desired in the matter of simplicity but has this drawback, that it gives only a single relation for two quantities which have to be determined, the new theory expresses these relationships by the equation

in which, however, K is now the relatively known magnitude of the total national capital productively used. Here, too, in order to determine the new unknown t, the further relation
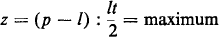
or, which is the same thing,
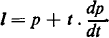
is added.
The boundary between fixed and variable capital is in this case really abolished.41 The whole capital, at least in so far as it is ‘turned over’ during the period of production, will subsequently appear in the form of money and means of subsistence, and, when no account is taken of ground-rent and the like, will be paid out in wages up to the last penny, but, as Böhm-Bawerk rightly remarks, not in one year, but during a period of time which, incidentally, amounts to half the length of the period of production.
5—Completion of Böhm-Bawerk’s theory. Capital-interest, wage and rent in their relationship to each other
Böhm-Bawerk’s theory forms, as was remarked above, only one element in the complete determination of the level of interest. The main reason for this is that the operation of natural forces, i.e. the services of the land, are not taken into consideration or, rather, are regarded as free. However, it would not be impossible to consider this factor also,42 particularly as the services of the land with regard to capital behave, in several respects, exactly like labour. The landowners, too, get their rent in advance, before the products are ready for the market. We can even assume, for the sake of simplicity, that ground-rent is paid by instalments, just as wages are; so that here also the necessary advance of capital comprises, on an average, half the length of the period of production.
In what has been said above we have assumed with Böhm-Bawerk, as the simplest hypothesis, that all labour is paid at the same rate and that in all branches of production the scale of surplus returns is the same, so that one and the same period of production is adopted everywhere. In the same way we can assume as a first approximation, that landed property everywhere is of the same quality and that in all branches of production an equally large area of land is required for each worker. The problem is then susceptible of exact treatment in its broadened form also, and we can generalize our equations, laid down above, in such a way that they also include the factor which has now been added.
Let us express the yearly wage by l, as before, and the ground-rent per hectare by r. If now h hectares of land are required for each worker, it is obvious that the capital advanced, calculated for a single worker, amounts in a t-year production to  . This is analogous to what has been said before.
Here the yearly production of one worker depends not only on the length of the period of production, but also, obviously, on the size of the area of land which falls to him. In other words, this magnitude becomes here a function of two variables which are independent of each other, namely t and h, and must be expressed by p = F(t, h). We notice at once that this function possesses, with regard to h, attributes which are quite analagous to those which it possesses in respect of t ; it increases when h increases, but the surplus return from one worker for every hectare of land added is as certainly a decreasing magnitude as the surplus return from every new extension of production.
The yearly expenditure of capital, calculated for each worker, is here consequently l + h. r, and equation (13) is now replaced by the equation
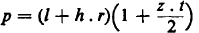
(20)
which changes into (13) as soon as r = 0, that is to say, as soon as the use of land is supposed to be free.
Now thrift requires that at each level of wages and ground-rent the greatest possible capital interest should be attained. z must therefore become a maximum (l and r being assumed to be constant). As is well known, this is done by making its partial derivatives in respect of t and h, each separately, equal to zero. (That in this case a maximum is actually reached, can easily be proved by reference to the attributes of the function p indicated above.) Or we simply differentiate the above equation partially with regard to t and h, as if z, too, were a constant, and we obtain thereby the two new equations
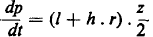
(21)
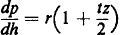
(22)
and
If, therefore, l and r were known, t, h and z could be determined from these three equations; so that we should obtain the most advantageous length of the period of production and the most profitable proportion of the use of land per worker, as well as the rate of interest itself, expressed in terms of wages and ground-rent.
But l and r, too, belong to the unknowns of the problem. To be able to solve it completely, we consequently need two independent equations as well. One of these is modelled on our previous equation (15). The existing capital of the community K must just suffice, in the case of the period of production and proportion of use of land in question, to employ fully all the available workers, and at the same time pay the necessary ground-rent. We therefore obtain, if the number of workers is A,
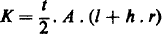
(23)
But just as all the available workers must here be employed by the capital, so, too, must the whole of the available area of land. If this is not the case, or if, on the contrary, more land is demanded than is available, the present level of ground-rent cannot be maintained; it must rise or fall, respectively. In other words, when equilibrium is to be attained, the most advantageous proportion of the use of land per worker, found above, must be equal to the proportion in which the number of hectares of land existing within the whole economy stands to the existing number of workers. If we express the former magnitude by B, we consequently obtain as the required fourth equation simply

(24)
The problem is now solved in its entirety.
Equation (23) can in this case, of course, also be replaced by
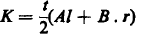
(23*)
The existing capital must suffice to pay all the workers during the period of production adopted, and must at the same time be sufficient to rent the whole of the land.
The landowners who work with their own means are here conceived in the double role of capitalists and landowners, just as, in the foregoing, we have treated the workers who are themselves capitalists. All three functions can, of course, be united in one person.
Discussion of the equations set forth above would now reveal the true relationship between capital-interest, wage and ground-rent—in so far as the assumptions which we have made are in approximate agreement with reality.43
Just as the equations set forth above constitute a completion of Böhm-Bawerk’s theory of interest, so they also include, as I shall now show, the older (Ricardo-Thünen) theory of ground-rent as a special case.
Our conditional equations obviously remain unchanged if, assuming in the first place any two of the three magnitudes l, r and z to be constant, we try to determine t and h in such a way that the third of these quantities becomes a maximum. If, therefore, we assume that z is constant and, in the meantime, for the sake of simplicity, = zero (or, which is the same, if we assume that its amount is already included in l and r), and if, moreover, we make the assumption that the length of the period of production is unchangeable, then equation (21) drops out and instead of (20) and (22) we obtain simply
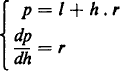
The former equation means that the yearly production of one worker must replace his yearly wage and, in addition, the ground-rent of the area of land which he has used. The latter equation, in its turn, expresses the fact that production will develop in the most advantageous way when each worker disposes of just so many hectares of land that the addition of a further hectare would increase his yearly production merely by the amount of the ground-rent of this hectare; since the wage reaches its highest possible level if the ground-rent is unchanged, and, vice versa, if the wage is unchanged, the ground-rent per hectare reaches the highest possible level.
In order to show that this is nothing else but the ordinary theory of ground-rent, we choose as unit for the used area of land, instead of one hectare only, an area so great that on each of these area-units a large number of workers can be employed. Our h then becomes a proper fraction; indeed,  , if n stands for the number of workers employed per unit of area. In the same way,
 , when q stands for the yearly production attained by the unit of land. Although n is here a whole number according to the nature of the matter, it can be treated approximately as a continuous magnitude. Thus we obtain, according to the rules of the differential calculus,
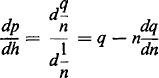
and the above-mentioned system of equations turns into
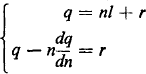
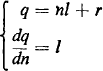
or into
which is the same thing.
What these two equations provide is precisely the mathematical expression of Ricardo’s theory of rent in the form given to it by Thünen. The significance of the first equation is self-evident (here, of course, r stands for the ground-rent of the present area-unit). But the second equation expresses the fact that the most advantageous production is attained if on each area-unit just so many workers are employed that the employment of a further worker would yield merely his annual wage and no more; which agrees with Thünen’s well-known law, mentioned above.
If we wish to take into consideration capital-interest as well here, we have simply to multiply the right side of the equations by  . But t must here be assumed to be a constant, otherwise a third relation is necessary, namely equation (21)44, which now turns into
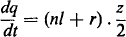
Now in the older theory of ground-rent the last relation was missing—quite naturally, since the length of the period of production has never been laid down as an independent concept. For this reason, however, the whole theory remained a very incomplete one. Without more exact definitions, there was talk of different quantities of ‘labour and capital’ or of different ‘doses’ of capital which are added to the land successively. But labour and capital can be used in various ways, and in particular it makes an important difference whether the capital is used simply to employ several workers in direct production, or for preparatory work, production of machines, breeding of draught-animals and food-producing animals, etc., as well—in other words, whether a longer or shorter period of production is adopted. Altogether, one could never arrive at the necessary factors which determine the level of capital-interest without considering this circumstance, and for the relationship between capital and wages there was, after all, only the completely insufficient wage fund theory. In all these respects Böhm-Bawerk’s theory forms, so to speak, the corner-stone which before was missing. Once this corner-stone had been laid, the science of economics could be looked on as something complete in itself.
All rent-goods (buildings, railways, etc.) which form, each group by itself, an unvarying sum of goods (assuming a stationary economy), would, in my opinion, have to be treated in the same way as landed property. In this case, of course, a special unit would have to be chosen for each group. However, I will not dwell on this matter, but will at once proceed to show how, with the help of the theory of capital-interest and ground-rent which we have obtained, our problem of the exchange values of goods, which we left for the time being at the end of the previous chapter, can now be treated in an exact way.
6—Attempt at a definite theory of the value of goods. Criticism of Walras’s presentation
Let us first of all try to imagine what an economy must be like, if the equations (20)-(24) (or the alternative equations given in the footnote to p. 152) are to reflect the true play of economic phenomena. This requires, of course, that within the whole economy only one single consumption good, for instance corn, is produced. Wages, ground-rent and capital-interest are all received in the form of goods, that is to say, in corn, and the capital itself consists of corn and the installations and tools necessary for the production of corn, which, however, we imagine as being so simple that they can be produced by the economies in question themselves and are of short duration. Durable goods are not produced at all. The economy must be a completely stationary one.
Let us now suppose that beside this economy there exists another, where in the same way another commodity—again, a single commodity only; for instance, linen—is produced. Exchange between the two economies is completely free, but capital and labour cannot be transferred from one to the other. For each of these two economies there would then exist a system of equiiibrium equations similar to system (20)-(24). The constants of the equations—the number of workers, the area of land and the capital—as well as the form of the function of productivity p (or q) are, however, different for both economies. Let the above-mentioned magnitudes be A1, B1, K1 and p1 for one economy and A2, B2, K2 and p2 for the other. When these magnitudes are inserted in equations (20)-(24) instead of A, B, K and p, we obtain from each of these equilibrium systems, by elimination of the remaining unknowns,45 first the length of the period of production t in question, then the values of the magnitudes l, r and z which we require to know. If these values are t1, l1, r1 and z1 for the first economy and t2, l2, r2 and z2 for the second, then A1l1 + B1r1 + K1z1 and A2l2 + B2r2 + K2z2 respectively express the quantities of goods which are produced every year in the two economies. Since, furthermore, the distribution of capital property and landed property within each economy must be assumed to be constant, we know now how much of this production falls to each person’s share. Of these quantities of goods, one part of the yearly production of one economy is exchanged for one part of the yearly production of the other economy. And this exchange takes place exactly according to the laws of exchange developed previously. If, for instance, some proportion of exchange (the price on both sides) is first of all assumed at random, then each of the owners of corn—that is to say, each worker, landowner and capitalist of the first economy—offers, at this price, a certain quantity of the corn which has fallen to his share for the year in exchange for a corresponding quantity of linen—i.e. just so much that the ratio of the marginal utilities of corn and linen (appropriate to the quantities of corn and linen which have been consumed during the year) is made equal to the ratio of the prices, that is, the proportion of exchange. By addition of these partial quantities, we obtain the yearly supply of corn and the yearly demand for linen on the part of the owners of corn—at the price in question. In exactly the same way a total supply of linen and a total demand for corn arise on the other side, at the same price. If supply of, and demand for, the one commodity are equal, and consequently also equal with regard to the other commodity, equilibrium is attained; if not, a shifting of prices must take place. But this change has obviously no influence on the proportion of production on both sides. The problem of international trade, of which we have here presented the simplest pattern, is therefore, in fact, much less complicated than that of internal trade. Before long an average proportion of exchange will establish itself. Afterwards, this proportion is maintained practically unaltered from year to year, and is characterized by the fact that for every member of both economies the proportionality between marginal utility and price of both commodities is fulfilled. In this case, of course, it is not necessary that each individual member should appear in the exchange market. Without essential change in the proportions, the exchange can be transacted by all the capitalists, or by a few of them; so that wage, ground-rent and capital-interest, too, can be paid in both kinds of goods or in any conventional medium of exchange (for instance, paper money), provided only the above-mentioned proportion of marginal utility is thereby realized as the final result.
But if we now imagine that both economies are united in a single economy, so that the existing workers, natural resources and capitals of both can now be used indiscriminately in the one or the other production of goods, then at first sight everything seems fluid. If we wish to make use of two equilibrium systems here, the difficulty arises that the magnitudes A1, A2, B1, B2, K1, K2 can no longer be assumed to be known; to begin with, we only know the sums A1 + A2 = A; B1 + B2 = B. As for the capitals K1 and K2, neither they themselves nor their sum are known, strictly speaking. The national capital, in so far as it is free, consists here of two commodities, and its value can therefore only be determined after having found out their prices—that is to say, can only be expressed in one of these or in some other conventional medium of exchange.
But, on the other hand, it is obvious that in this case two different rates of wage, rates of rent and rates of interest can no longer exist, but wage, rent and interest on both sides will become approximately equal (in so far as the labour force and natural resources can be assumed to be uniform).
Let us first try to give an account of how these changes would come about after abolition of the boundary-line between the two economies. Let us suppose that at first l1 and l2, r1 and r2, z1 and z2 are still different. If l1 > l2, the workers will gradually go over from the linen business to the corn business: A1 increases; A2, on the other hand, decreases. And vice versa: if, when the boundary-line is abolished, r1, for instance, is smaller than r2, part of the land used for the cultivation of corn will gradually be employed for the production of linen. B1 decreases and B2 increases. Finally, if z1, for instance, is at first smaller than z2, the capital engaged in the production of corn, in proportion as it becomes free (which occurs by production itself), will be partly invested in the production of linen. Since this capital appears first in the form of corn, some of the workers in the linen business will consequently, if no account is taken of previous exchanges, now receive their wages directly in corn. However, this does not make any difference to them, provided the proportion of exchange between linen and corn remains unchanged. But this proportion of exchange cannot remain unaffected by the changes which have taken place either. If, therefore, taking corn as the standard of value, the price of linen has fallen, the capitalists, whose free capital consists mainly of linen, must increase the number of pieces in their capital stock if they wish to restore to it the same value; if, on the contrary, the price has risen, they can, without loss, decrease this number and consume part themselves. But it is very probable that all the capitalists will increase the number of pieces in their capital stock, at least for some time. In general, this freer and therefore more appropriate employment of productive forces must necessarily lead to higher productivity within both branches of business, and this increased productivity will facilitate the formation of new capital, until finally the stationary situation is again reached—only this time with more capital and probably a higher average level of ground-rent and wages (but not necessarily a higher average level of the rate of interest).
To pursue all these changes in detail is quite impossible, especially as they take place in an infinite number of different ways. We can, however, determine without difficulty the position of equilibrium finally attained, with the help of our equations set forth above—but only if we assume that the present capital is a known magnitude.
First of all the two initial equations
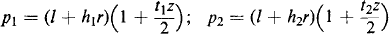
with their derivatives46 in respect of t1, h1, t2 and h2 (altogether six equations), must be fulfilled.
The magnitudes l, r and z are now equal on both sides. On the other hand, we assume here for each branch of the business, according to the nature of things, a special form of the productivity function p = F(t,h) (which we assume to be known), as well as a different length of the most profitable period of production and a different proportion of the use of land (number of hectares per worker or, vice versa, number of workers per hectare). We therefore have, for the time being, six independent equations with the seven unknowns t1, t2, h1 h2, l, r and z.
In the equations still remaining
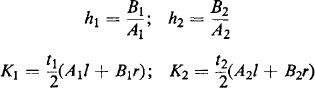
the six new unknowns A1, A2, B1, B2, K1 and K2 occur, but for their determination we still have the equations
A1 + A2 = A
B1 + B2 = B
K1 + K2 = K
where A, B and K stand for the number of workers, area of land and capital existing within the whole economy, the latter expressed in terms of corn. We therefore have altogether thirteen equations with the same number of unknowns,47 but only on the assumption that the proportion of exchange of both commodities is known.
Here, p1 and p2 express values, that is to say, they give the exchange value of the yearly production (as functions of t and h). But, of course, in the first instance only the number or quantity of the products in question is, in fact, established by the functions of productivity, which were assumed to be known on both sides. Since now the corn has been taken as our standard of value, p1—the value of the production of corn (per year and worker)—is dependent merely on t1 and h1; the function p2, on the other hand, includes, in so far as it is supposed to give the exchange value of the production of linen, another factor π, namely the proportion of exchange of both commodities or the uniform price of linen expressed in terms of corn.48 But this proportion of exchange cannot be assumed to be known here; rather, our task is to show how it is determined by the interplay of all the economic forces. We therefore still have one unknown in excess of the number of equations and need one more of the above-mentioned independent equations, if the problem is to be completely solved.
To find this, we must imagine ourselves placed on the market of exchange of both commodities, and we must lay down the condition that on this market, too, there is equilibrium—equilibrium between supply and demand or, what is here the same, equilibrium between production and consumption.
This can come about, for instance, in the following way. At each level of l, r and z the yearly income of every single member of the economy, in addition to other factors, is definitely fixed. If, for instance, the individual in question is a worker himself, and if he possesses b hectares of land and has invested in the production capital of the value k, then his yearly income e is expressed by e = l + br + kz. This income he uses, according to our fundamental assumption, to the last penny (or rather to the last part of corn) for his yearly consumption of corn and linen. We therefore obtain
e = x + πy
when x and y respectively stand for his yearly consumption of these goods.49 But these quantities must now fulfil the law of marginal utility, so that, if f( ) and g( ) stand for the marginal utility functions related to the quantity of the yearly consumption,
f (x) : g(y) = 1 : π
Since the forms of the functions f( ) and g( ) must be assumed to be known, x and y can be determined from the last two equations, that is to say, can be expressed in terms of l, r, z and π. When this operation is carried through for each member of the economy,50 we have also found the total consumption of, or demand for, the goods concerned, and, according to what has been said above,
X = Σx = A1p1
The yearly consumption of corn on the part of the total economy must correspond to the yearly production of corn. In the same way, with regard to the consumption and production of linen,
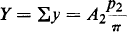
One of these equations, however, can be derived from the other; for we obtain from these
A1p1 + A2p2 = Σx + πΣy = Σe = Al + Br + Kz
On the other hand, as is evident, we obtain by addition of our initial equations of production, or by multiplying them by A1 and A2,
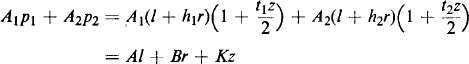
The one or the other of the above equations gives us, consequently, the hitherto missing relation between our unknown magnitudes. If A1 and A2 are already eliminated, we can instead use the equation
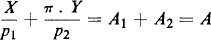
Or we could imagine each of the two branches of production as complete in itself, so that the yearly production is in the first instance simply distributed among the members as wage, rent and interest, and the supplies on both sides are partly exchanged later, p1 as well as p2 are then to be thought of as numbers of pieces. Wage and rent, likewise expressed in terms of number of pieces of the commodity in question, are connected by the relations
l1 = πl2, r1 = πr2
and if the capital invested on both sides is in the first instance valued in terms of the commodities concerned, then
K1 + πK2 = K
in which K, as before, expresses the known value of the total national capital (valued in corn). If now, for instance, the individual mentioned above uses b1 hectares in the corn business and b2 in the linen business, or invests the capitals k1 and k2 and has himself worked about eight months in the corn business and four months in the linen business, then he receives each year
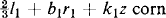
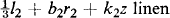
and
All these individual quantities are then brought to the cornlinen market and are partly exchanged against each other. The equilibrium price, found according to the rules of exchange, appears now as a known function of l1, l2, r1, r2 and z, but must equal π, by which means the missing relation is found. Both methods, obviously, lead to the same result, and we can lay down as the final result of our investigation the rule:
If an economy comprises the production, distribution and consumption of only two commodities, the proportion of exchange between them is given by the following conditions: (1) that wage, rent and interest during production of both commodities must be equal; (2) that at the level of wages and rent attained, interest becomes a maximum (or, in general, at the attained level of two of these three magnitudes, the third becomes a maximum); (3) that the existing capital must just suffice to employ the existing number of workers and to rent the existing area of land, and; (4) that the two commodities are distributed among all members of the economy directly or after a preceding exchange, in such a way that the ratio of the marginal utilities of the quantities consumed yearly becomes everywhere equal to the ratio of exchange of the goods.
We have now reached the end of our investigation; for if the theory developed here has gone to the root of economic phenomena, all complications of the problem will find their solution by suitable combinations of equations of the kind laid down above, at least in so far as it is a question of a stationary economy. Let us glance at these complications as they occur in real economic life.
1. Production and consumption in a modern economy comprise not only two commodities, but hundreds of them, even if only the main kinds of goods are reckoned ; and within every class of goods there is usually a large number of different qualities and specialities.
However, this circumstance will only make necessary a larger number of equations. With every new commodity which must be taken into consideration, six new unknowns enter the problem, according to our above-mentioned scheme; since for each commodity the most profitable period of production and proportion of the use of land, the number of workers, area of land and capital employed in its production, and finally the exchange value of the commodity are to be determined. If there are n goods and one of them is taken as the standard of value, the number of unknowns will consequently be 6n + 2.51 For their determination the laws of production give, as can easily be seen, 5n + 3 independent equations, whilst the missing n—1 equations are obtained from the laws of exchange—for instance, by means of a formula expressing the fact that, at the n— 1 prices of the goods, which must be determined and expressed in terms of one of them, the quantity of each commodity yearly consumed or demanded must be equal to its yearly production, and by taking into consideration that only n—1 of the n equations laid down in this way are independent.52
2. Labour and forces of land were each assumed as a homogeneous mass.
This is, of course, not correct. For certain productions there is at any time only a very limited number of workers who are employable at all, since the business requires either special abilities or a longer training. In order that this circumstance may be taken into consideration, the existing workers must be divided into groups, and the wage for each group, which can then be very different for the various groups, must be ascertained separately. But once the boundary-lines of these groups are drawn, the number of independent conditioning equations (Bedingungsgleichungen) will here obviously increase also to the same extent as the number of the unknowns.53
As for natural resources, we come first of all to the well-known fact of the difference of landed property with regard to fertility, situation, etc. But, in addition to this, there are natural resources of an entirely different kind: agricultural landed property, fish-ponds, woods, ore-bearing tracts, waterfalls, etc. For each of these kinds, a special uniform measure must, of course, be chosen.
Finally, in my opinion, produced goods also, in so far as they are continuing sources of rent, should be taken into consideration here. In the stationary economy such goods are not produced at all, but kept in the same good condition.54 The capital investment in question itself belongs to past time and need no longer be considered. The net interest on this capital has consequently the precise character of a rent, since necessary repairs and maintenance work, as well as running costs, are imposed on the capitalist who uses these goods.
On the other hand, it cannot be right to do as Böhm-Bawerk does and try to exclude means of improving the soil, as soon as they have ‘grown together’ with the land, from the sphere of capital. In the same way, improvements, such as fertilization and the like, which suffice for only a few harvests and must consequently replace the invested capital after a short time, belong obviously to agriculturally-employed capital in the narrower sense, as do tools, labour, draught animals and food-producing animals, etc.
Dwelling-houses, too, must in my opinion be added to rent-goods. Dwellings—just as much as food, clothes, heating, etc.—belong to the needs which must be satisfied from the economic point of view. Why, then, should the service of giving shelter which dwelling-houses provide not be put in the same category as the economic services of fields, meadows, woods, fish-ponds, etc.? From the point of view of the stationary economy there is scarcely any substantial difference left between them.
The boundary-line between rent-goods and capitals in the narrower sense can, I grant, only be established empirically, and even then only approximately. Practically, however, the difference is a highly important one. The volume of circulating capital determines the level of wage, rent and capital-interest. Upon these the highly durable goods merely exercise the same influence as, say, the size of the cultivated area of land. But their capital value is, at least in the stationary economy, an entirely secondary phenomenon and has for the exchange values of consumable goods no importance whatsoever.
For production, we have consequently to consider—once this boundary-line is drawn—not merely the capital K and the different groups of workers AI, AII, AIII, AIV, etc., but also the different groups of rent-goods BI, BII, BIII, BIV, etc., each with its different quantity-unit and rent of this unit. Each new group becomes the source of new unknowns but also the source of the necessary number of new independent equations.
3. It was assumed that the production of a new commodity in all its different stages is done in one single business. In reality this is practically never the case. The raw materials and means of production are usually produced in special firms; the same factory often supplies tools and machines for several different branches of business, and, on the other hand, half-finished products and raw materials coming from quite different sources are put together and further worked up in a single business, etc. Viewed prospectively or retrospectively, the businesses branch out or meet.
This circumstance would create no special difficulties if the production of each separate commodity could be followed through the various businesses, and if we could find out what quantity of labour, capital and natural resources (or of services of the other rent-goods) has been engaged in the completion of this particular commodity. If this is not possible, and if, consequently, the production of two or more commodities forms more or less an indissoluble whole, then, if we are to treat the problem mathematically, these goods must be united in one single group; because then they pay for the labour, capital and rent-goods used in their production not separately, but all together. In the equations of exchange, however, they are to be treated separately again (in so far as two or more of them cannot replace each other).
4. The supply of labour was treated as a constant magnitude. This is not quite correct even if the number of workers remains the same; for the daily working-time can, in certain circumstances, vary, or several days or weeks of the year can be spent in idleness—not only because of lack of employment during certain seasons, but also because the worker may allow himself more leisure when wages are more abundant. That is to say, a labourer’s ability to work or his time, unlike most rent-goods, is of value to its possessor, even when it is not used productively.
If, therefore, we do not (with L. Walras) use the word ‘production’ in such a general sense that even a person’s use of his spare time, a walk, etc., is regarded and treated as ‘production,’ it obviously becomes necessary to consider the yearly working-time, and consequently the yearly production, of a worker as itself a function of the wage. It must be remarked in this connexion, however, that, even if the working-time of the individual worker possibly decreases when wages rise, yet, on the other hand, people who have previously lived in idleness are now tempted or rather forced by the higher price of labour to become workers themselves. Moreover, men will be able to work harder in the shorter working-time because of the greater abundance of food, etc. It cannot therefore be decided a priori to what extent, in given circumstances, a rise or fall in wages would increase or reduce the effective supply of labour. Each individual case must be investigated separately.
5. Finally, our assumption of a stationary economy represents only the simplest case which is theoretically conceivable, but which never quite comes to pass in reality. In exceptional cases, such as our own century, for instance, there can even occur a progression of society so great that this hypothesis does not correspond even approximately to reality. In any case the theory must, in order to be complete, not only be able to treat the statics but also the dynamics of economic phenomena; it must not only take into consideration the equilibrium of economic forces, but also the disturbance of this equilibrium caused by their changes.
The number of workers, or, more generally, of the population, can be increased by a rise in the birth rate or by immigration, and can be decreased by exceptionally heavy mortality or by emigration. The sum of rent goods, including the cultivated area of land, can be increased by industry and decreased by neglect respectively. Lastly, the national income carusuffer changes in several ways. The transformation of capital in the narrower sense into rent-goods or even into working ability (its sacrifice for purposes of education) is here to be emphasized as such a change, and, what is more, as a change of the greatest importance.
If in all these relationships a certain rate of progression may be assumed to be given, then it is clear that equations of production and exchange can be laid down. We have then, so to speak, a problem of dynamic equilibrium instead of a problem of static equilibrium with which to deal.55
It would be quite a different matter to try to lay down laws for determining the rate of progression itself. I personally make no attempt in this direction.56 How far present-day political economy still is from being able to treat these situations in an exact way, becomes clear if we consider the fact that economists are still by no means agreed as to the extent to which such a progression of society is advantageous or not. In particular, so far as I know, the question has never been raised in economic writings, what size of population is economically most profitable when the amount of capital, size of the area of land, etc., are given. If, therefore, these problems are to be solved according to the principle of the greatest utility, it is obviously a serious drawback that there is not even common agreement in what direction economic advantage or disadvantage in fact lies. If, on the other hand, we assume that changes of population are not regulated according to the principle of what is economically most advantageous (in the widest sense of the word), but are regulated now and for ever merely by blind natural instincts, then at least we are on firm ground. In that case, however, we should have no alternative but to accept Ricardo’s doctrine of the natural wage—that is to say, the smallest possible wage—as a fact beyond dispute. Altogether, population questions are unfortunately still neglected by the economists of practically all schools. This is regrettable from the theoretical point of view, but still more regrettable, of course, from the practical point of view.
Even if we take no account of the unfortunate state of affairs last mentioned and look at the problem as a purely statical one, the foregoing enumeration shows that the list of complications is a very considerable one. But it is clear, when treating concrete problems of reality, as soon as the required facts are more or less at hand, all necessary simplifications will follow automatically. The practical business man has, after all, to consider as far as possible all circumstances which influence the conditions of production and sale of his commodity. If he cannot possibly penetrate, or does not need to see at a glance, all phenomena of the market, this may be regarded as proof that, for the theoretical treatment of the problems which he has in fact to solve, at first only a comparatively small number of the pertinent magnitudes need be inserted in the calculation.
Above all, we should, in this case, have to define more precisely the still somewhat hazy concept of the length of the period of production within the individual main businesses—for instance, agriculture, the textile industry, the iron industry, etc.—and to find out the increase in this period which has resulted from the improvements introduced from time to time, in so far as they have really required a larger investment of capital. Once such information is available for the main fields of economic life, the counting procedure and, with it, the a posteriori investigation of the theory can start. It must be remembered, however, that the results of the theory can only remain valid on the assumption of completely free competition.
The doctrine set forth here has much in common with the theory presented in Léon Walras’s Élements d’économie politique pure. There, too, equations of production are laid down and combined with the equations of exchange previously obtained. But, as was remarked above, Walras calls ‘capital’ and treats as ‘capital’ only durable goods, but not raw materials and half-finished products and not the means of subsistence of workers. What the owner of the circulating capital advances to the workers, landowners, etc., is therefore not treated by Walras as capital at all. It is therefore implicitly assumed by Walras that workers and other producers maintain themselves during production and receive remuneration for their productive services from the proceeds of the products in question only after completion of the production. This is obviously incorrect. In this interpretation the true rôle of capital in production is completely overlooked. A necessary consequence of this is the peculiar fact that these equations of production and exchange can give no information at all about the level of the rate of interest. If only durable goods are regarded as capital, then a certain rent is fixed for each group of these by the above-mentioned equations, but not the capital value of the goods itself, nor, consequently, the rate of interest either, ‘le taux du revenu net.’ This is explicitly admitted by Walras; but he asserts that, in order to determine the level of interest, it is necessary to turn from the investigation of a stationary economy to the investigation of a progressive one, where new interest-bearing capital goods are produced, whose capital value can be determined from the production costs. This is certainly incorrect. In the stationary economy, too—even if we assume that all the means of production are indestructible—a rate of interest of the circulating capital will undoubtedly establish itself, precisely because the lengthier methods of production prove more profitable. Walras’s theory of production and capital consequently rests upon incorrect assumptions and cannot be regarded as definitive. However much it may—in several respects—testify to its author’s acuteness, the- real essence of the matter has not become clear to him. The merit of having taken the decisive step forward belongs in this field to Jevons and, above all, to Böhm-Bawerk.57
______________________
58 Throughout this chapter I shall use as fundamental the excellent works of Böhm-Bawerk, especially his Positive Theorie des Kapitals, which, I may be allowed to assume, is known to most readers.
59 Positive Theorie des Kapitals, p. 24.
60 Inversion of this seeming paradox produces the question, How is it that goods which can yield, according to their nature, an infinite number of useful services, above all landed property, possess nevertheless only a finite capital value ?
61 Principles of Economics, p. 124. Adam Smith’s remark (Wealth of Nations, vol. II, chapter I), that houses let to a tenant and similar goods can only be reckoned as private capital for the simple reason that rent must always be taken from any other source of income, is meaningless. The same is, after all, true of every money income and, generally speaking, of every income which arises from exchange. If a craftsman or a business-man reckons his landlord as customer, his income is drawn from the landlord’s, just as the landlord’s is drawn from his.
62 Op. cit., p. 70.
63 Op. cit., p. 76.
64 Böhm-Bawerk, op. cit., p. 73.
65 It must not be overlooked that the role of the capitalist and that of the worker can also be united in one and the same person.
66 Op. cit., p. 75.
67 We say intentionally, ‘up to the moment of consumption’; for it is after all of little importance whether the duration of life of capital is or is not theoretically prolonged by several hours, days or even weeks. The economic sign that goods cease to be capital-goods is, as I see it, this—that they, so to speak, have passed into the lawful possession of the consumers; that is to say, are exchanged for some capitalistic equivalent: labour, the use of land, other capital-goods or money. Nevertheless, the consumers—or the persons so named by us for the sake of simplicity—can in this case partly deny themselves the consumption goods which now belong to them lawfully and use them as new capital-goods. We have already dealt with the position of durable consumption goods.
68 According to Böhm-Bawerk the productive undertakings designed to improve landed property in so far as they preserve an independent character and do not become completely absorbed in the landed property (e.g. dams, pipes, etc.), ought to be called capital. But of what importance is this independent character here? When it is a question of the level of interest or wages, these goods have exactly the same importance as landed property itself, provided only they are sufficiently durable.
69 Money has in this case a remarkable double position. For the community as a whole it is a rent-commodity; what is more, rent (the utility of money) received by the community is many times in excess of the amount of the usual money interest. For the single possessor it is a capital-good.
70 It is, in my opinion, even more comprehensive than the problem itself, in that it also includes interest phenomena where no interest-bearing capital exists any longer (as in the case of a consumption loan).
71 In his book Principii di economia pura (p. 301), M. Pantaleoni opposes Böhm-Bawerk in saying that, if it were true that a present commodity possessed a higher marginal utility than a future commodity, the loan would in fact be a purposeless transaction, because like would merely be exchanged against like. The superficiality of this objection is obvious after what has been said above.
72 If this were not the case, one would hear little of times of famine and distress, and so on. Nothing seems easier than to do as Joseph and Pharaoh did and, when the harvest is good, put aside the surplus for use when the harvest is bad. But the practical solution of this problem soon proves to be a very difficult one, not only because of the improvidence of individuals, but first and foremost because of the cost and inconvenience of the storage itself.
73 Here, obviously, we are speaking only of the well-thought-out and ‘motivated’ productivity theory of a writer like Thünen. Böhm-Bawerk has a much easier task with most of the other so-called productivity theorists, who were often not even able to distinguish between product of capital and interest on capital. I shall not even mention the incredible superficialities of a writer like Carey. Böhm-Bawerk rightly says of this author, that ‘his theory belongs to those which not only discredit their author, but also the study which is betrayed into accepting them so faithfully; and this not because of its errors, but because of the unpardonable nature of the mistakes by which it errs.’ (Kritik und Geschichte der Kapitalzinstheorie, p. 179.)
74 The usual explanation of capital-value of durable, produced goods, such as a dwelling-house, by reference to the costs of production and reproduction, is, of course, unscientific and amounts to mixing up and lumping together cause and effect.
75 Positive Theorie des Kapitales, p. 301.
76 Particularly as regards the question of the ‘use of money,’ the Use theory can be applied with success. When we so apply it we are generally disturbed by the fact that a borrowed sum of money is ‘used’ by the debtor once only, and for the most part immediately after the receipt of the loan. In fact, however, he uses the money at least twice, once for the purchase, and once for the sale of goods; and in this case the circulation of the money which has taken place in the meantime generally enables him to sell the purchased commodity at a profit later on. This becomes especially clear if one looks at the simplest case where no real production is involved but the money merely serves for the exchange—that is to say, for the economically more advantageous distribution of the existing goods. If we assume that this sum constitutes the only money in circulation within the economy in question, then the situation which we have met before in the case of the exchange of several commodities arises, and we can follow the identical moneys right up to the time of the repayment of the loan. In this case at any rate, interest appears first not in the form of money but in the form of goods.
77 Strictly speaking, however, as was indicated above, interest on a consumption loan does not belong to the sphere of true capital interest, since here the loaned ‘capital’ continues to exist not as a material commodity but merely as a claim and the repayment takes place by a new formation of capital on the part of the debtor (or by diminution of already existing capital).
78 Adam Smith (Wealth of Nations, vol. II, Introduction) tried to explain the need for capital formation by the division of labour, since the latter can only come about if the subsistence of the workers concerned is already assured by the accumulation of a given supply of food. But this seems to me to be a false conclusion. Division of labour by itself does not lengthen the period of production, but shortens it, and therefore does not in fact make necessary new capital formation (but does make necessary a certain concentration of the already existing capital). On the other hand, however, as is well known, division of labour is one of the most powerful instruments of production: many round-about methods of production which would otherwise not be sufficiently remunerative, become so by division of labour; and to this extent, of course, the possibility of division of labour becomes indirectly an effectual cause of the adoption of these round-about methods and consequently of the accumulation of new capital.
79 For several reasons, the constancy of these changes is still more evident if the average proportions within a certain branch of business, considered as a whole, are examined.
80 Loc. cit., p. 95.
81 Whether a capital-good, for example a dwelling-house, will presumably last only 50 or even 100 years, makes, on the assumption of a rate of interest of 5 per cent, a difference of not quite 9 per cent (8 · 72 per cent) to its present-day capital value; whether it lasts 200 instead of 100 years makes a difference of less than 0·7 per cent; whether it lasts for ever instead of for 200 years, makes absolutely no difference, since only the minute difference in value of 0-0057 per cent is involved (i.e. instead of perhaps 100,000 M the house would then be worth 100,005 M 70 Pf.).
82 The neglect of this important distinction is, in my opinion (indicated above), one of the fundamental mistakes in Böhm-Bawerk’s presentation, which is otherwise so clear. We shall see in due course how he was led by it to criticize in a quite mistaken way Jevons’s theory of interest.
83 That in this case a maximum and not a minimum of l occurs, can, with reference to the conditions of the problem, easily be proved. Compare the following geometrical illustration.
84 Strictly speaking, this is, of course, only correct if the month can be regarded as an infinitely small part of the whole process of production. As regards this whole subject, cf. my essay ‘Kapitalzins und Arbeitslohn’ in Conrads Jahrbücher, December 1893, p. 868 ff.
85 No account is, of course, taken here of brokerage, etc., and a single rate of interest is assumed for the whole capital market.
86 We can easily convince ourselves of the truth of this, either by examining equations (13) and (14), or, still more easily, by considering the relevant diagram.
87 This gradation of production can, of course, be very easily adopted by individual producers as well. Agriculture and, still more, market-gardening are examples.
88 The figures of the third column, divided by the number of years of the period of production in question, represent the interest, calculated for half the level of wages; for the necessary advance of capital for each worker over a period of x years is  of the yearly wage, and the annual profit from one worker constitutes the interest on this sum. For example, if the period is one of six years, we obtain
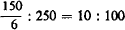
89 Loc. cit., p. 415.
90 Here, however, we must remember the situation mentioned on p. 128 ff. Certainly, when competition is free, a rate of wage of 500 fl. comes about in the way described above, and at this rate the six-year period of production is seen to be the most profitable for each individual capitalist. If, however, the capitalists, regardless of this, agree to adopt and keep to a seven-year period, then the wage would have to fall to about 430 fl., and at this rate of wage the seven-year period will now yield a net profit of more than 16 per cent. The profit would be still more huge if an eight-year period were adopted, and so forth.
91 Böhm-Bawerk gives in a note (p. 419) ‘the mathematical proof of this somewhat paradoxical thesis,’ assuming a ‘five-year production divided into sections of one year each.’ If, however, we assume—as in other contexts he himself does—a continuous gradation of production and wage-payment, then what was assumed above becomes self-evident; for a production of n years will then require for every worker, as was pointed out above, an advance of capital of  yearly wages. A production of n + 1 years consequently requires an advance of
 yearly wages, and the difference between these figures is precisely half the yearly wage.
92 The passage on p. 226 ff. quoted by Böhm-Bawerk refers to the capital-labour market, where capitalists and workers offer to each other, within certain limits, their ‘goods’ ‘at any price,’ and where, therefore, the proportion of exchange (the wage) simply becomes equal to the proportion of the existing quantities.
93 That is to say, the capital formerly employed was  per worker; the capital now employed is consequently
 , and the difference between these expressions amounts to
 .
94 This must in the end be the case, since, if t increases, even the expression α + β log nat t increases beyond all limits.
95 This must not be confused with his well-known but mistaken speculations about the so-called natural wage.
96 Or vice versa: If the workers themselves are entrepreneurs, it must be assumed that the rate of interest is given and that the wage is still to be determined.
97 If a certain capital k is invested, and then t years elapse before the product—which all this time has grown in value—is sold, we obtain
s = k(1 + z)t
where s is the final value of the product and z the average yearly rate of interest. This rate of interest becomes a maximum when
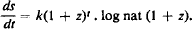
By division of these equations we obtain
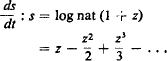
Since, now, log nat (1 + z) expresses the ‘instantaneous’ rate of interest, where z is the yearly rate of interest, Jevons’s rule could be completed in such a way that, when interest becomes a maximum, the ‘natural’ rate of interest must ultimately correspond to the present rate of interest. (For small values of z, log nat (1 + z) is approximately equal to z.)
If, on the other hand, we assume that production is continuous, we obtain from the two equations in the footnote on p. 123, as can easily be seen,
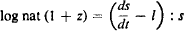
or

Here, too, it is most advantageous to extend the period of production up to the point at which the (paid out or received) interest (instantaneous rate of interest) is equal to ‘the rate of increase of produce divided by the whole produce,’ according to Jevons’s formula except that in this case the amount of wages which has to be paid each moment must be subtracted from the gross increase of produce.
98 But only, as I understand it, if we exclude predominantly durable goods (such as buildings, streets, railways, etc.), with which we shall deal soon.
99 For the time being we shall leave out of account the services of the remaining ‘rent-goods.’
100 In passing, we may show that what Böhm-Bawerk has to say about the influence of ground-rent on capital-interest can scarcely be right.
Böhm-Bawerk asserts (loc. cit., p. 438) that the advance of capital to landowners (ground-rent) has an effect on the level of the rate of interest precisely analogous to the effect of the existence of the consumption loan (discussed by him before). ‘The fact that the landowners, too, compete for consumption loans,’ he continues, ‘takes a portion of the means of subsistence out of the market, and a result of this is that the investment of capital in production decreases; investment must call a halt at a higher level of surplus returns; and in this way the rate of interest is at last maintained on a higher level.’
But Böhm-Bawerk forgets the tremendous difference which is made by the fact that the applicants for consumption loans pay interest on the advance of capital which has been made to them, whilst the landowners do not. In other words, the portion of capital paid out as ground-rent together with the portion of capital used in the production itself (paid out as wages) yields interest in the form of the net profit of production. Consequently it is not enough that the capital diminished by ground-rent remains ‘at a higher level of surplus returns.’ When in these circumstances the rate of interest is forced up, the case examined above must occur, where (leaving out of account the services of the land) an increase of productive capital would lead to an absolutely lower net profit and a decrease of capital would consequently yield an absolutely greater net profit. That this is really the case in the present state of production, is scarcely credible. It seems to me most probable that if ground-rent were abolished, that is to say, if the services of the land were free, capitalists would obtain a higher interest on their capital. But what would happen if—as Böhm-Bawerk supposes by way of example—the taxation of ground-rent reached a confiscatory level or private ownership of land were even abolished, is less easy to decide. Actually, however, ground-rent would not be abolished, but would be paid by the capitalists exactly as before; only the state would have replaced the private owner of landed property.
101 At the very beginning, of course, we could equally well have set down the equation
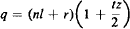
and its derivatives in respect of t and n
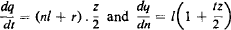
and combined them with equations (23*) and (24), which latter is to be replaced by  .
However, we have preferred to use as starting-point the production of one worker supported by the forces of nature.
102 This elimination can be done quite easily for l, r and z (even without knowing the form of the function of p). h is then replaced simply by  in equations (20), (21) and (22).
103 Analogous to equations (21) and (22).
104 The unknowns which were introduced last can, it is evident, be eliminated very easily. By this means we obtain between t1, t2, h1, h2, l and r and between the known magnitudes A, B and K one single relation, namely
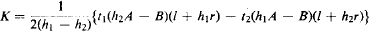
which in conjunction with the first six equations, is sufficient for the determination of the still remaining unknowns t1, t2, h1, h2, l, r and z.
105 When q2 = F(t2, h2) expresses the number of pieces of linen produced (per year and worker), then p2 = π . q2 = π. F(t2, h2).
106 It is in this case totally indifferent in what form he originally receives his income, whether in the form of corn or linen or both, since linen is always expressed, at the equilibrium price π, in terms of corn.
107 It is clear that, if a really numerical treatment of the problems should ever be attempted, the consumers would have to be divided into larger groups, whose consumption of, or demand for, the various goods could be found out empirically at each level of prices.
108 Namely t1 . . . tn, h1 . . . hn, A1 . . . An B1 . . . Bn, K1 ... Kn, the l’s, r’s and z’s for all productions, and finally the n − 1 proportions of exchange—independent of each other—of the n goods. In the way indicated on p. 132, footnote 1, the 3n magnitudes A1 . . . An, B1 . . . Bn, K1 . . . Kn can easily be eliminated, and in this way the number of the unknowns of the problem is reduced to 3n + 2.
109 When in this case two or more goods can partly replace each other, the marginal utility of any one of them will, of course, not only be a function of the yearly consumed quantity of this commodity, but of all the goods in question.
110 If workers from the different groups are employed in the same production, the equations in question become, of course, even more complicated, especially as the proportion of workers of different categories would often have to be ascertained according to the principle of the greatest possible profit (difference between male, female and young workers, etc.). Similarly with regard to different qualities of land and to rent-goods altogether.
111 The replacement of completely worn out goods of this kind by new ones need not be excluded, of course, but can be regarded as repair of a greater complex of goods. According to the conception stated above, the difference between rent-goods and capital-goods consists in the fact that the sum of the former is independent of the length of the period of production of consumption goods.
112 The production of new rent-goods, for instance, must then be treated in the same way as the production of consumable goods, in which case, however, the sum of the circulating capital no longer remains unchanged. Instead, the condition is added that the newly produced rent-goods must yield as rent the usual capital-interest on the costs of production.
113 We could, of course—as L. Walras does—think of the yearly savings, and consequently the increase of capital, under otherwise unchanging circumstances, as a function of the level of interest, provided we keep in mind that a rise in the rate of interest can not only give cause for an increase in savings, but can also, in certain circumstances, have the contrary effect, and vice versa. But then the population must necessarily be assumed to be stationary or at least its yearly change must be assumed to be given; for obviously—to take an example—the number of children in a family is of much greater importance for the eventual formation or consumption of capital by that family, than the level of the rate of interest.
114 In the second edition of his work, Walras, commenting on Böhm-Bawerk’s theories, raises the objection that capital-interest can only establish itself on the market and that he has tried in vain to find mention of this market in Böhm-Bawerk’s writings. Walras probably knows only the extract from Böhm-Bawerk’s book in the Revue d’économie politique which he mentions, because it is precisely this market which is presented in sketches in the last chapter of the Positive Theorie des Kapitals, although the services of the land are left unconsidered. I have tried, in what has been said above, to supply what was wanting here.
______________________
1 If we are to take into consideration compound interest instead of simple interest, it will be best to set out from equation (12). However (on the assumption of immediate interest) this equation then takes the form
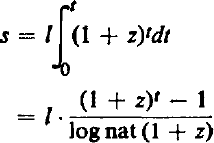
which afterwards is combined with its first derivative in respect of t:
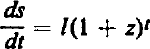
For sufficiently small values of z and values of t which are not too great, the first expression turns into
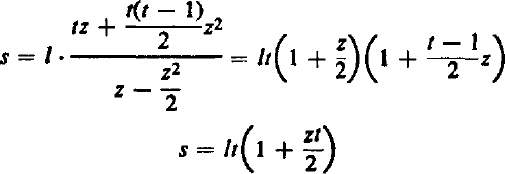
as when calculating simple interest.
- 1Wicksell’s work was like a mountain from whose flanks divergent streams run down and bring fertility to widely separated fields, only to merge again later into a single broad river. For the fiercest and most exciting battle of economic theory in the first half of the twentieth century was that fought in the middle thirties between the adherents of Professor Hayek’s over-investment theory of the business cycle, on the one hand, and Lord Keynes and his lieutenants on the other. No two theories, it seemed at that time, could be more directly opposed to each other in method and conclusions. Yet in both of the books from which the controversy started, Keynes’s Treatise on Money which appeared in 1930 and Professor Hayek’s Prices and Production which was published in 1931, Wicksell’s name was prominent and the power and insight of his analysis acknowledged. And the solution of this paradox, as we can now discern it, is no less surprising: Lord Keynes was setting out the theory of under-employment and Professor Hayek that of over-employment; these were in a fundamental sense two sides of the same theory, one of them describing what happens when effective demand for productive resources is less than the available resources and the other explaining the mechanism of boom, crisis, and collapse which result from an attempt to use more resources than there are. The flat contradiction in which the two theories seemed to confront each other was illusory; they were no more contradictory than the two statements, that if a stone is denser than water it will sink, and if a cork is less dense than water it will float. The basis of Professor Hayek’s theory was the Austrian theory of capital, which Böhm-Bawerk had founded and Wicksell had interpreted and refined. Professor Hayek showed how the power of the banking system to create money and thus, through an ‘artificially’ low market rate of interest, delude the economy into thinking that it had a larger potential flow of real investible resources than in fact it had, could lead to a crisis where people might find themselves rich in half-constructed railways but starving for lack of today’s dinner; and it is precisely the mechanism and nature of the ultimate dependence of our choice of methods of production upon our available reserves of sustenance that Wicksell, following Böhm-Bawerk and in essence the wage-fund theorists, is concerned with in Über Wert, Kapital und Rente. The banks’ power to create money? But this is also what Keynes was concerned with in his Treatise, and again what Wicksell had been concerned with in his famous book Geldzins und Güterpreise, published in 1898, in which the essential and many-fold importance of time in the economic process is made the king-pin of a fundamental synthesis.
- 2In the early 1870’s Jevons, Menger and Walras had independently and almost simultaneously created the marginal utility theory of value, which explains how the ratios in which different goods exchange for one another are determined by the balancing of marginal subjective desires. But there was one startling omission from the list of things whose value in terms of each other could be thus accounted for. The subjective theory of relative prices depends on the principle of diminishing marginal utility; utility, that is to say, for purposes of consumption. But money is not consumed, it is merely exchanged or stored, its utility must therefore be of quite a different kind from that of consumable goods, and its value in terms of these goods must require some different principle for its explanation. In Wicksell’s own words ‘It is of no consequence whatever to a purchaser that he has to pay more for one commodity provided he can be certain of himself obtaining a correspondingly higher price for some other commodity.’ The general level of absolute or money prices was, in fact, left unexplained by the marginal utility theory of value, and some other account had to be given of it. Until the appearance of Geldzins und Güterpreise the prevailing explanation was the Quantity Theory, whose crude arithmetical argument presents a striking contrast, às Professor Hicks has pointed out, with the subtlety of the theory of value. The Quantity Theory assumes that the frequency with which money units change hands, when averaged over all the money units in existence, is fairly constant through time, and from this deduces that the total money value of transactions per unit of time is proportional to the number of money units in existence. Thus so long as the size of the stream of goods being bought and sold remains in some sense unchanging, the general level of prices will depend on the Quantity of Money, that is, on the number of money units in existence.
- 3In the early 1870’s Jevons, Menger and Walras had independently and almost simultaneously created the marginal utility theory of value, which explains how the ratios in which different goods exchange for one another are determined by the balancing of marginal subjective desires. But there was one startling omission from the list of things whose value in terms of each other could be thus accounted for. The subjective theory of relative prices depends on the principle of diminishing marginal utility; utility, that is to say, for purposes of consumption. But money is not consumed, it is merely exchanged or stored, its utility must therefore be of quite a different kind from that of consumable goods, and its value in terms of these goods must require some different principle for its explanation. In Wicksell’s own words ‘It is of no consequence whatever to a purchaser that he has to pay more for one commodity provided he can be certain of himself obtaining a correspondingly higher price for some other commodity.’ The general level of absolute or money prices was, in fact, left unexplained by the marginal utility theory of value, and some other account had to be given of it. Until the appearance of Geldzins und Güterpreise the prevailing explanation was the Quantity Theory, whose crude arithmetical argument presents a striking contrast, às Professor Hicks has pointed out, with the subtlety of the theory of value. The Quantity Theory assumes that the frequency with which money units change hands, when averaged over all the money units in existence, is fairly constant through time, and from this deduces that the total money value of transactions per unit of time is proportional to the number of money units in existence. Thus so long as the size of the stream of goods being bought and sold remains in some sense unchanging, the general level of prices will depend on the Quantity of Money, that is, on the number of money units in existence.
- 4Wicksell by no means rejected the Quantity Theory in toto, but he was disturbed by its dependence, in its classical form, on the assumption of a constant velocity of circulation of money: ‘The Quantity Theory,’ he says, ‘is theoretically valid so long as the assumption of ceteris paribus is firmly adhered to. But among the “things” that have to be supposed to remain “equal” are some of the flimsiest and most intangible factors in the whole of economics—in particular the velocity of circulation of money, to which, in fact, all the others can be more or less directly referred back.’ How strongly these words suggest Lord Keynes’s later pre-occupation with the elusive essence of money and its recalcitrance to a purely mechanical, non-psychological analysis. Ricardo had, of course, believed that there was an intimate and indeed an obvious connection between changes in the quantity of money, changes in the general level of prices (or its inverse, the value of money) and the level of the interest-rate. A willingness of the banking system to increase continually the outstanding amount of its loans or of its note issue could express itself, and become effective, only by a low rate of interest. As soon as the outflow of extra money into public circulation ceased, prices of goods would soon adjust themselves to this new larger quantity of the circulating medium; at these new higher prices, the quantity of money would no longer be in effect any greater than before, and the interest-rate would accordingly return to its former level. But Wicksell, though agreeing with Ricardo’s conclusion, did not think that Ricardo had penetrated deeply enough into the mechanism by which interest, the quantity of money, and the price-level are connected with each other. For what, he asked, is a low rate of interest? By what criterion do we judge when the rate of interest is low? By comparison with what is it low?
- 5Wicksell found the answer by looking back at that branch of economic theory which had been his earliest concern, and which he had expounded in Über Wert, Kapital und Rente, the theory of capital. The more highly articulated, specialized and elaborate the system of equipment becomes through which men apply their effort to their natural environment, the larger the ultimate reward to a given effort, but to carry the elaboration from a given degree to a still higher one implies the foregoing of, say, N units of consumable output which would have been available in year T in exchange for the prospect of an extra m units per year in perpetuity, beginning in year T + 1. The ratio then represents, nearly enough, what Wicksell called the natural rate of interest. It is a measure of the ‘worthwhileness,’ at any stage of the development of the economy’s total assemblage of productive equipment, of adding one more ‘unit’ to that equipment. How are such units to be defined? In making such an addition to their total equipment the people composing the economy are, in effect, postponing the consumption of some of the output which their current input of productive services entitles them to consume. The average time elapsing between the moment when a dose of work or of the services of nature is put into the productive process, and the moment when the dose of consumable product attributable to that dose of work comes out, is thus lengthened, and this average time, Böhm-Bawerk’s ‘average period of production,’ can serve as a measure of the size of the total capital equipment. A balanced assemblage of such capital equipment, comprising tools, machines, buildings, flocks and herds, growing crops, forests, mines, libraries, transportation systems, and indeed the whole material frame of civilized life, is like a great reservoir into which human effort has been poured and from which the means of living can be drawn off. The metaphor of a reservoir will serve to illustrate the meaning and use of the average period of production. If a heavy shower of rain falls on an actual reservoir on a particular day, some of this rainwater will flow out for use on that same day, but a large proportion will remain for many days or weeks mixed with the rest of the reservoir’s contents, and it would indeed be possible to describe the size of the reservoir by saying how long, on the average, with a given outflow, each drop of water that enters it remains in it. The natural rate of interest, then, is a measure of the strength of the inducement to increase the average period of production; and in a given set of other circumstances, the numerical value of the natural rate, the percentage , will be a decreasing function of the length of the average period of production. But these ‘Other circumstances’ are, of course, just as important, in determining the natural rate of interest, as the average period of production itself is. In Wicksell’s own words: ‘The natural rate is not fixed or unalterable in magnitude. ... In general, we may say, it depends on the efficiency of production, on the available amount of fixed and liquid capital, on the supply of labour and land, in short on all the thousand and one things which determine the current economic position of a community; and with them it constantly fluctuates.’ Now it was this natural rate of interest by comparison with which, at any time, the rate of interest charged by the banks for money loans could be said to be high or low. ‘Now let us suppose,’ says Wicksell, ‘that the banks and other lenders of money lend at a different rate of interest, either lower or higher, from that which corresponds to the current value of the natural rate of interest on capital. The economic equilibrium of the system is ipso facto disturbed. If prices remain unchanged, entrepreneurs will in the first instance obtain a surplus profit... over and above their real entrepreneur profit or wage. This will continue to accrue so long as the rate of interest [on loans of money] remains in the same relative position. They will inevitably be induced to extend their business in order to exploit to the maximum extent the favourable turn of events,... As a consequence, the demand for services, raw materials, and goods in general will be increased, and the price of commodities must rise.’
- 6Properly speaking, one therefore needs only to know the three ratios of these four values, as we shall see.
- 7Wicksell found the answer by looking back at that branch of economic theory which had been his earliest concern, and which he had expounded in Über Wert, Kapital und Rente, the theory of capital. The more highly articulated, specialized and elaborate the system of equipment becomes through which men apply their effort to their natural environment, the larger the ultimate reward to a given effort, but to carry the elaboration from a given degree to a still higher one implies the foregoing of, say, N units of consumable output which would have been available in year T in exchange for the prospect of an extra m units per year in perpetuity, beginning in year T + 1. The ratio then represents, nearly enough, what Wicksell called the natural rate of interest. It is a measure of the ‘worthwhileness,’ at any stage of the development of the economy’s total assemblage of productive equipment, of adding one more ‘unit’ to that equipment. How are such units to be defined? In making such an addition to their total equipment the people composing the economy are, in effect, postponing the consumption of some of the output which their current input of productive services entitles them to consume. The average time elapsing between the moment when a dose of work or of the services of nature is put into the productive process, and the moment when the dose of consumable product attributable to that dose of work comes out, is thus lengthened, and this average time, Böhm-Bawerk’s ‘average period of production,’ can serve as a measure of the size of the total capital equipment. A balanced assemblage of such capital equipment, comprising tools, machines, buildings, flocks and herds, growing crops, forests, mines, libraries, transportation systems, and indeed the whole material frame of civilized life, is like a great reservoir into which human effort has been poured and from which the means of living can be drawn off. The metaphor of a reservoir will serve to illustrate the meaning and use of the average period of production. If a heavy shower of rain falls on an actual reservoir on a particular day, some of this rainwater will flow out for use on that same day, but a large proportion will remain for many days or weeks mixed with the rest of the reservoir’s contents, and it would indeed be possible to describe the size of the reservoir by saying how long, on the average, with a given outflow, each drop of water that enters it remains in it. The natural rate of interest, then, is a measure of the strength of the inducement to increase the average period of production; and in a given set of other circumstances, the numerical value of the natural rate, the percentage , will be a decreasing function of the length of the average period of production. But these ‘Other circumstances’ are, of course, just as important, in determining the natural rate of interest, as the average period of production itself is. In Wicksell’s own words: ‘The natural rate is not fixed or unalterable in magnitude. ... In general, we may say, it depends on the efficiency of production, on the available amount of fixed and liquid capital, on the supply of labour and land, in short on all the thousand and one things which determine the current economic position of a community; and with them it constantly fluctuates.’ Now it was this natural rate of interest by comparison with which, at any time, the rate of interest charged by the banks for money loans could be said to be high or low. ‘Now let us suppose,’ says Wicksell, ‘that the banks and other lenders of money lend at a different rate of interest, either lower or higher, from that which corresponds to the current value of the natural rate of interest on capital. The economic equilibrium of the system is ipso facto disturbed. If prices remain unchanged, entrepreneurs will in the first instance obtain a surplus profit... over and above their real entrepreneur profit or wage. This will continue to accrue so long as the rate of interest [on loans of money] remains in the same relative position. They will inevitably be induced to extend their business in order to exploit to the maximum extent the favourable turn of events,... As a consequence, the demand for services, raw materials, and goods in general will be increased, and the price of commodities must rise.’
- 8Wicksell found the answer by looking back at that branch of economic theory which had been his earliest concern, and which he had expounded in Über Wert, Kapital und Rente, the theory of capital. The more highly articulated, specialized and elaborate the system of equipment becomes through which men apply their effort to their natural environment, the larger the ultimate reward to a given effort, but to carry the elaboration from a given degree to a still higher one implies the foregoing of, say, N units of consumable output which would have been available in year T in exchange for the prospect of an extra m units per year in perpetuity, beginning in year T + 1. The ratio then represents, nearly enough, what Wicksell called the natural rate of interest. It is a measure of the ‘worthwhileness,’ at any stage of the development of the economy’s total assemblage of productive equipment, of adding one more ‘unit’ to that equipment. How are such units to be defined? In making such an addition to their total equipment the people composing the economy are, in effect, postponing the consumption of some of the output which their current input of productive services entitles them to consume. The average time elapsing between the moment when a dose of work or of the services of nature is put into the productive process, and the moment when the dose of consumable product attributable to that dose of work comes out, is thus lengthened, and this average time, Böhm-Bawerk’s ‘average period of production,’ can serve as a measure of the size of the total capital equipment. A balanced assemblage of such capital equipment, comprising tools, machines, buildings, flocks and herds, growing crops, forests, mines, libraries, transportation systems, and indeed the whole material frame of civilized life, is like a great reservoir into which human effort has been poured and from which the means of living can be drawn off. The metaphor of a reservoir will serve to illustrate the meaning and use of the average period of production. If a heavy shower of rain falls on an actual reservoir on a particular day, some of this rainwater will flow out for use on that same day, but a large proportion will remain for many days or weeks mixed with the rest of the reservoir’s contents, and it would indeed be possible to describe the size of the reservoir by saying how long, on the average, with a given outflow, each drop of water that enters it remains in it. The natural rate of interest, then, is a measure of the strength of the inducement to increase the average period of production; and in a given set of other circumstances, the numerical value of the natural rate, the percentage , will be a decreasing function of the length of the average period of production. But these ‘Other circumstances’ are, of course, just as important, in determining the natural rate of interest, as the average period of production itself is. In Wicksell’s own words: ‘The natural rate is not fixed or unalterable in magnitude. ... In general, we may say, it depends on the efficiency of production, on the available amount of fixed and liquid capital, on the supply of labour and land, in short on all the thousand and one things which determine the current economic position of a community; and with them it constantly fluctuates.’ Now it was this natural rate of interest by comparison with which, at any time, the rate of interest charged by the banks for money loans could be said to be high or low. ‘Now let us suppose,’ says Wicksell, ‘that the banks and other lenders of money lend at a different rate of interest, either lower or higher, from that which corresponds to the current value of the natural rate of interest on capital. The economic equilibrium of the system is ipso facto disturbed. If prices remain unchanged, entrepreneurs will in the first instance obtain a surplus profit... over and above their real entrepreneur profit or wage. This will continue to accrue so long as the rate of interest [on loans of money] remains in the same relative position. They will inevitably be induced to extend their business in order to exploit to the maximum extent the favourable turn of events,... As a consequence, the demand for services, raw materials, and goods in general will be increased, and the price of commodities must rise.’
- 9Jevons’s formula could be applied in one case only, namely when the marginal utility function concerned may be replaced by an approximating function of the first degree which is identical for all members of the market party in question. (It is a somewhat less special case than the one mentioned above, where this function must be identical for the members of both parties.) Then, as can easily be seen, the arithmetical mean of all the marginal utility values would only be dependent on the acquired or remaining total supply of the community concerned and on the number of the possessors in question. Jevons’s formula, which in that case would probably assume the form
- 10Some Leading Principles of Political Economy newly expounded.
- 11Principles, Ch. I, Section V.
- 12Launhardt reproached Walras with ‘great error’ in supposing that ‘what is generally best would most certainly be reached by the natural effect of the rule of free competition.’ As far as I know, however, Walras has never asserted this, although he expresses himself a little incautiously upon this subject.
- 13It is said to have been in fact put forward by a certain Dr. Anderson before Adam Smith, but at that time remained unconsidered.
- 14There was, in my opinion, a good reason why Ricardo, in showing up these weaknesses, did not treat capital property in the same way as landed property. The former had, at least, the advantage over landed property that its object, capital, had first to be created; and the existence of large amounts of capital can only have beneficial consequences for society itself, which could hardly be affirmed of the monopoly of landed property. Adolf Held’s reproaches, Zwei Bücher zur sozialen Geschichte Englands, are therefore unfounded in my opinion. As to Ricardo’s alleged ‘harshness’ towards the working classes, it should be mentioned that he never represented the low level of wages as the only possible situation for workers, still less as something which is pleasant in itself. How in his opinion workers could achieve a better position at that time, Ricardo has partly shown directly, and partly indicated indirectly, by accepting Malthus’s doctrine. As I see it, men like Malthus and Ricardo, who tried to search out the true reason of social conditions and particularly of the low standard of living of workers, have done more for their welfare than those economists who sometimes make a great show of friendly feelings towards the workers, but do not want to learn the means which could really have remedied their situation. A German economist, very well known in recent times and very praiseworthy in different ways, has actually delivered an academic speech on the causes of social want without uttering a single word on the population question. In the Revue d’Economie politique of November 1891, the same author made the astonishing statement that Karl Marx has ‘refute la these, en consequence de laquelle le salaire devait dépendre de l’augmentation ou de la diminution de la population totale, au lieu de dépendre de l’excès existant dans chaque industrie, et cela de telle manière qu’elle ne devrait plus ètre soutenue dans les cercles scientifiques.’ Probably as a proof of this alleged victory of Marx over Ricardo and Malthus, it is later mentioned that the attempts of the coal-miners of Durham and Northumberland to improve their situation during the prosperous period that followed the Franco-Prussian war, failed because new workers from other branches of industry came from all parts of the United Kingdom. ‘Ce fut surtout des matelots qui s’y rendirent.’
- 15If I am not wrong, the so-called specular iron-ore.
- 16This expression occurs only here and there in Marx’s work—e.g. on page 96, n. 80, of the third edition of Das Kapital—but it expresses exactly his true meaning.
- 17If working time alone determined exchange value, it would make no difference to the value or to the quantity of the product whether, for example, 10 workers took 10 years to produce it or 100 workers a single year. This, in fact, cannot be true, because otherwise it would never be profitable to invest capital in the longer period of production.
- 18For one has, as can easily be seen,
- 19Theory of Political Economy, 2nd edition, p. 124 ff.
- 20Considered geometrically, it is represented by a curve which can nearly always be replaced by a broken line, but not by one and the same straight line.
- 21In Jevons’s book these signs are represented by ϕ1( ), ϕ2( ), ψ1( ) and ψ2( ).
- 22Of other selling possibilities and of the production of the goods concerned, no account is taken here.
- 23Cf. the above treatment of this problem in respect of two exchanging persons.
- 24For, in accordance with his assumptions repeatedly mentioned, a simple marginal utility function (in respect of each of the commodities) was drawn, identical for both parties. Here, of course, the curves can only have one single (real) point of intersection in common.
- 25The problem of exchange of two commodities also could, of course, have been treated in this way. This would express the more general case, where each of the exchanging persons at first possess both commodities, and according to the level of prices acts as buyer of the one commodity and seller of the other, or vice versa.
- 26Obviously, any one of the commodities could itself be conceived as the standard of value, in which case the price of this commodity would = 1. For the sake of symmetry, however, we have adopted a different standard of value, as in fact, in most cases, agrees best with reality ; for even if two commodities are exchanged for each other in a simple way by reciprocal credit between two business-men, their value is initially almost always reckoned in money.
- 27In this case, the notation used above will have to be altered correspondingly.
- 28We must here draw attention to tome discontinuities of our functions previously laid down, which we have not discussed so far. Our equations of value
- 29Strictly speaking, however, this is generally only the case when the commodities (A) and (B) cannot replace each other, so that, as we have assumed above, the marginal utility of one of them depends simply on the quantity owned of this commodity or on the quantity acquired, and not at the same time on the quantity acquired or the quantity owned of the other commodity. But if both commodities can replace each other completely or partly, it is a different matter. Suppose, for instance, that (B) is wheat and (A) potatoes. If a possessor of wheat can cover with it the whole of his annual food requirements, but potatoes are cheaper in proportion to their nutritive value, then he will probably exchange every year a certain quantity of wheat for the cheaper potatoes. But if now the price of potatoes (expressed in terms of wheat) were to fall still lower, he could first of all procure for himself the same quantity of potatoes in exchange for a smaller outlay of wheat. But since he thus keeps more wheat, his annual requirements in the matter of food could be even more than covered in this way. Therefore, if it is for him only a question of satisfying these requirements, he will be able to keep without loss a still greater quantity of wheat and content himself with a smaller quantity of potatoes, so that his demand for potatoes would finally decrease with the falling price instead of increasing.
- 30Untersuchungen Uber die Theorie des Preises, Preface, p. XXIII.
- 31Of the production of goods no account is taken here, of course.
- 32In the case of three commodities the equations (7), with the help of the equations (8), may be considered solved in x, y, z, etc.; in which case the positive x’s and y’s are conceived as (individual) demands and the negative ones as supplies, etc. (the appropriate + or—sign must in this case, of course, be regarded as given by the nature of the task).
- 33In this case, the curves of the commodity (B) also would, of course, intersect at three points, lying vertically under the points of intersection of the curves of commodity (A).
- 34In the case of three commodities, these are identical with equations (9).
- 35Even the exchange of finished goods requires time. In so far as it does this, it can be added to the production and is itself a source of capital interest.
- 36We shall soon see what is meant by these according to Walras.
- 37This must in the end be the case, since, if t increases, even the expression α + β log nat t increases beyond all limits.
- 38This must not be confused with his well-known but mistaken speculations about the so-called natural wage.
- 39Or vice versa: If the workers themselves are entrepreneurs, it must be assumed that the rate of interest is given and that the wage is still to be determined.
- 40If a certain capital k is invested, and then t years elapse before the product—which all this time has grown in value—is sold, we obtain
- 41But only, as I understand it, if we exclude predominantly durable goods (such as buildings, streets, railways, etc.), with which we shall deal soon.
- 42For the time being we shall leave out of account the services of the remaining ‘rent-goods.’
- 43In passing, we may show that what Böhm-Bawerk has to say about the influence of ground-rent on capital-interest can scarcely be right.
- 44At the very beginning, of course, we could equally well have set down the equation
- 45This elimination can be done quite easily for l, r and z (even without knowing the form of the function of p). h is then replaced simply by in equations (20), (21) and (22).
- 46Analogous to equations (21) and (22).
- 47The unknowns which were introduced last can, it is evident, be eliminated very easily. By this means we obtain between t1, t2, h1, h2, l and r and between the known magnitudes A, B and K one single relation, namely
- 48When q2 = F(t2, h2) expresses the number of pieces of linen produced (per year and worker), then p2 = π . q2 = π. F(t2, h2).
- 49It is in this case totally indifferent in what form he originally receives his income, whether in the form of corn or linen or both, since linen is always expressed, at the equilibrium price π, in terms of corn.
- 50It is clear that, if a really numerical treatment of the problems should ever be attempted, the consumers would have to be divided into larger groups, whose consumption of, or demand for, the various goods could be found out empirically at each level of prices.
- 51Namely t1 . . . tn, h1 . . . hn, A1 . . . An B1 . . . Bn, K1 ... Kn, the l’s, r’s and z’s for all productions, and finally the n − 1 proportions of exchange—independent of each other—of the n goods. In the way indicated on p. 132, footnote 1, the 3n magnitudes A1 . . . An, B1 . . . Bn, K1 . . . Kn can easily be eliminated, and in this way the number of the unknowns of the problem is reduced to 3n + 2.
- 52When in this case two or more goods can partly replace each other, the marginal utility of any one of them will, of course, not only be a function of the yearly consumed quantity of this commodity, but of all the goods in question.
- 53If workers from the different groups are employed in the same production, the equations in question become, of course, even more complicated, especially as the proportion of workers of different categories would often have to be ascertained according to the principle of the greatest possible profit (difference between male, female and young workers, etc.). Similarly with regard to different qualities of land and to rent-goods altogether.
- 54The replacement of completely worn out goods of this kind by new ones need not be excluded, of course, but can be regarded as repair of a greater complex of goods. According to the conception stated above, the difference between rent-goods and capital-goods consists in the fact that the sum of the former is independent of the length of the period of production of consumption goods.
- 55The production of new rent-goods, for instance, must then be treated in the same way as the production of consumable goods, in which case, however, the sum of the circulating capital no longer remains unchanged. Instead, the condition is added that the newly produced rent-goods must yield as rent the usual capital-interest on the costs of production.
- 56We could, of course—as L. Walras does—think of the yearly savings, and consequently the increase of capital, under otherwise unchanging circumstances, as a function of the level of interest, provided we keep in mind that a rise in the rate of interest can not only give cause for an increase in savings, but can also, in certain circumstances, have the contrary effect, and vice versa. But then the population must necessarily be assumed to be stationary or at least its yearly change must be assumed to be given; for obviously—to take an example—the number of children in a family is of much greater importance for the eventual formation or consumption of capital by that family, than the level of the rate of interest.
- 57In the second edition of his work, Walras, commenting on Böhm-Bawerk’s theories, raises the objection that capital-interest can only establish itself on the market and that he has tried in vain to find mention of this market in Böhm-Bawerk’s writings. Walras probably knows only the extract from Böhm-Bawerk’s book in the Revue d’économie politique which he mentions, because it is precisely this market which is presented in sketches in the last chapter of the Positive Theorie des Kapitals, although the services of the land are left unconsidered. I have tried, in what has been said above, to supply what was wanting here.
- 58‘There remains, however, one outstanding attempt at a systematic treatment, namely Knut Wicksell’s Geldzins und Güterpreise, published in German in 1898, a book which deserves more fame and much more attention than it has received from English-speaking economists. In substance and intention Wicksell’s theory is closely akin ... to the theory of this Treatise.’
- 59See ‘A suggestion for simplifying the theory of money,’ by J. R. Hicks, Economica, New Series, No. 5
- 60Interest and Prices, by Knut Wicksell, translated by R. F. Kahn (Macmillan and Co. Ltd., London 1936) p. 39.
- 61Interest and Prices, p. 42.
- 62Interest and Prices, p. 106.
- 63In order to be able in this case to determine the constants α, β, α’, β’, it is necessary to know for at least two values of x which belong to this sphere, the corresponding four values of the functions of the marginal utilities F(a − x) and f (x). If we suppose that for x = b the marginal utility of corn is ν and the marginal utility of the corn converted into spirits ν’, and that for x = c their values are w and w’ respectively, α, β, α’, β’ can easily be expressed by ν, w, ν’ and w’, and we obtain
- 64In Über Wert, Kapital und Rente Wicksell treated highly durable goods as ‘Rentengüter,’ that is, goods whose durability renders them economically akin to the self-maintaining forces of nature.
- 65Interest and Prices, p. 105.
- 66But Jevons never says clearly what is really meant by this collective marginal utility of a trading body, and it seems as if he himself had not formed a sufficiently clear idea of it. The marginal utility of a commodity for a trading body can scarcely be anything else but the average marginal utility, the arithmetical mean, or else any mean of the individual marginal utilities of its members. But neither is it clear how the proportion of exchange can depend on this average marginal utility in the way Jevons demands, nor can one understand how it could be conceived as a function of the size of the possessed total supply, since the average marginal utility in fact also depends on the distribution of this supply and, what is more, on the distribution after the exchange, which is still unknown.
- 67As regards labour, this is a consequence of the reciprocal competition of workers, whereby wages are always reduced to one and the same level. Here, of course, one must meet the objection that in fact different kinds of labour are generally rewarded very unequally. Ricardo, indeed, has not given sufficient thought to this fact. He simply pointed—as Adam Smith did before him—to the effect of competition, which has apparently been the laying down of a fixed scale of reward for qualified labour which, during longer or shorter periods, remains unchanged. This is not correct, as Cairnes especially has shown in detail : between different grades of workers or of society in general no effective competition exists.
- 68The theoretical difficulty presented by this was not solved by Ricardo; and of course it never can be solved in such a way that this proportionality between prices and quantities of labour would still hold good. It should be remembered, however, that here, too, Ricardo has correctly understood the sequence of cause and effect; if money wages rise (which in his view could only happen over longer periods as a result of the greater difficulty in producing the means of maintenance of workers, although in general such a rise can be understood as the consequence of every increase of capital), then the introduction of machines which before proved unproductive will now become more profitable, as he has shown in an ingenious example. The price of machinery, that is to say, includes profit as well as wages. As this profit, like all the others, must fall when wages rise, the price of machines can consequently never rise in the same proportion as wages. According to the more modern terminology, this means that every increase of wages encourages a lengthening of the period of production, which occupies more time but is more productive, whereby the wage increase is partly compensated. Indeed, in this example of Ricardo’s, the fine theories with which Böhm-Bawerk has recently enriched the subject lie enclosed as in the bud. In these theories the relationships between the rate of interest and wages appear in a strong light, in which, however, they are seen to be less simple than was assumed in Ricardo’s ‘iron’ law of wages or in the wage fund theory.
- 69Still less can it be asserted that the distribution of the com modities which is most favourable economically, that is to say, the greatest possible general satisfaction, arises from free competition. If this problem is conceived in the absolute sense, its solution, as can easily be seen, requires that the marginal utility of all exchanging persons should become the same in relation to each separate commodity. But this situation will quite often lie beyond the limits of the possible exchange, as it would bring to some of the exchanging persons loss instead of profit. This, however, does not prevent the problem from being solved in the relative sense, that is to say, in so far as it is compatible with the fundamental condition of exchange. But this could obviously only happen if the individual transactions were carried out at different prices, instead of at the single joint price required by free competition.
- 70It is known that the last-mentioned point in particular gave rise to the ingenious theory of rent which bears Ricardo’s name, though it really originates from Malthus and Sir Richard West. With growth of population and increasing capital, the demand and prices for agricultural products rise, ceteris paribus; this leads to the cultivation of poorer land as well as a more intensive cultivation of land already under the plough. The owners of better land, or the landowners generally, are consequently able to appropriate to themselves as rent from this monopoly a greater and greater share, absolute and relative, of the yield of land. Only the poorest land gives no rent; the last labourer engaged in cultivation only raises products equal in value to his own means of maintenance (including the usual interest, in cases where these were advanced to him by the capitalist). At this extreme point the products of agriculture, in respect of their exchange value, come under the same rules as were valid in actual industry. It is the labour engaged on the poorest land, or, more generally speaking, that agricultural labour which provides no rent, but, nevertheless, does yield profit, that determines, in Ricardo’s view, the value of agricultural products. The rule of labour as a measure of value was therefore also applied in this connexion, though, as one finds, in an entirely formal manner. Proportionality of commodity prices with the quantity of labour employed in the production of these goods, is here no longer mentioned.
- 71A more searching analysis of economic phenomena would certainly have made possible a scientific extension of Ricardo’s theory of value. Such an extension, however, was not undertaken; on the contrary, this theory underwent a completely unscientific and paradoxical exaggeration at the hands of two completely opposed schools, the harmony economists (Bastiat among others) on the one hand, and the socialists on the other. The dispassionate and purely scientific investigation of the English scholars had unmercifully exposed the weaknesses of our modern economic life. It now became the task of the defender of the existing order of society to conceal or explain away these weaknesses as far as possible. It was the aggressors’ task, on the contrary, to show them in a particularly strong light. Both trends met strangely in the attempt to establish labour not only as a formal measure of exchange value, but—and from this attempt Ricardo wisely abstained—also as the real cause and substantial ground of value.
- 72In Ricardo’s system, as we have seen, not only labour, but also capital profit and ground-rent, claimed to get their share of the fruits of production. But are not the latter themselves products of labour? asked Bastiat and his school. Is not capital itself produced by labour, and does not the fertility of the cultivated land depend on the labour of former generations? They answered both these questions in the affirmative, and believed they had achieved by this a considerable improvement on Ricardo’s theory. All value became now an indirect or direct product of labour; not only the true capitalist but also the owner of landed property obtained as his profit only the reward of his own and his ancestors’ labour, or the reward of his renunciation in not having consumed the fruits of this labour. It needs few words to show how absurd this view is, especially as regards landed property. Let us look merely at the extreme cases. What human hand ever gave value to our forests, coal-fields, ore-seams, natural meadows and pastures, fish-ponds, etc.; what human hand ‘created’ the source of returns which they give to their owners? The matter does not wear a much better aspect if one tries to explain these un-produced values as the fruits of the industrial labour of the whole society, as Leroy-Beaulieu did in his work Repartition des Richesses. This is a point which, as is well known, Lasalle also tried to make, but in the socialist interest. A vacant building site in the middle of a well populated town has, as everybody knows, a very high value. Is this value also a product of the local industries? This is certainly a confusion of ideas. The real cause of this phenomenon is not the productivity of industry or labour, but the fact that this labour is not sufficiently productive. In spite of all hard work, all improvements of the means of communication, etc., a numerous town population cannot overcome the inconveniences which are caused by increasing distances. This is the cause of the high value of central building sites or open spaces. What is given for them may indeed be the creation of industry, but not their value itself, which, on the contrary, is determined by the sum of the needs which they satisfy. There can, of course, be cases where human thought or hand can sometimes give a high value to things which were hitherto worthless, without any direct influence. It is said, for instance, that, through the introduction of the Bessemer method in the iron-industry, certain ores which in former times were thought valueless have proved to be the best material for the new process, so that the owners of the ore-seams in question suddenly found themselves in possession of considerable wealth. Up to a certain point one can, of course, regard this value as a product of Bessemer’s inventive genius, but it would be quite absurd to try to find any proportion between the labour which in this case Bessemer employed for his invention (even if the labour of all his predecessors were included) and the values, perhaps quite unknown to him, which they later produced or, rather, revealed. Even Leroy-Beaulieu does not go so far.
- 73This is not the place to go into a more detailed analysis of the socialist doctrines, which in fact include many things which do not stand or fall by this or that economic theory. But in their criticism of the present system of production as well as in the estimate of economic resources which they themselves recommend, the socialist authors are to a great extent under the influence of the peculiar theory of value which, since the first writings of Marx, has become more and more the pillar of the socialist system. The so-called proof which Marx gives of his rule that labour is the substance of exchange value, whilst unpaid labour equals the profit of capitalists, on which his extensive work Das Kapital is only a continuous commentary, has, in fact, as is now most probably more and more admitted, scarcely the virtue of being able to be discussed seriously. It consists of a kind of free application of the principium exclusi tertii. If two commodities are exchanged against each other in the market, they must, says Marx, be equal in some one respect. But the equality cannot consist in the fact that they have the same value in use; on the contrary, this must necessarily be different, otherwise the exchange would be senseless. The values in use of different commodities are indeed incommensurable quantities (says Marx), and nothing is consequently left but that both commodities are the product of an equally long working time. Or, as the same thought is expressed by Marx elsewhere: If one divests commodities of the specific attributes which determine their values in use (which cannot be compared with one another), there is only one attribute left, namely that of being ‘labour jelly’ (Arbeitsgallerte), definite masses of ‘congealed labour time.’ The gaping holes in this argument hardly require special mention. Even if the values in use of two different commodities, or the utility which they have at any time, were quite incomparable magnitudes and could consequently not be taken into consideration, there could generally exist a great number of circumstances besides labour which together could, without being the same for both commodities, constitute the same exchange value. For instance, both have used a certain area of land for the production of raw material as well as for the production of the finished commodity; for both of them a certain quantity of power (coal) was needed to bring them to market, etc. But as regards working time, not only its length, but also the intervals between different stages of production, in other words the time during which the means of maintenance and of production for the workers must be advanced, have influence on the productivity of labour.
- 74This is not the place to go into a more detailed analysis of the socialist doctrines, which in fact include many things which do not stand or fall by this or that economic theory. But in their criticism of the present system of production as well as in the estimate of economic resources which they themselves recommend, the socialist authors are to a great extent under the influence of the peculiar theory of value which, since the first writings of Marx, has become more and more the pillar of the socialist system. The so-called proof which Marx gives of his rule that labour is the substance of exchange value, whilst unpaid labour equals the profit of capitalists, on which his extensive work Das Kapital is only a continuous commentary, has, in fact, as is now most probably more and more admitted, scarcely the virtue of being able to be discussed seriously. It consists of a kind of free application of the principium exclusi tertii. If two commodities are exchanged against each other in the market, they must, says Marx, be equal in some one respect. But the equality cannot consist in the fact that they have the same value in use; on the contrary, this must necessarily be different, otherwise the exchange would be senseless. The values in use of different commodities are indeed incommensurable quantities (says Marx), and nothing is consequently left but that both commodities are the product of an equally long working time. Or, as the same thought is expressed by Marx elsewhere: If one divests commodities of the specific attributes which determine their values in use (which cannot be compared with one another), there is only one attribute left, namely that of being ‘labour jelly’ (Arbeitsgallerte), definite masses of ‘congealed labour time.’ The gaping holes in this argument hardly require special mention. Even if the values in use of two different commodities, or the utility which they have at any time, were quite incomparable magnitudes and could consequently not be taken into consideration, there could generally exist a great number of circumstances besides labour which together could, without being the same for both commodities, constitute the same exchange value. For instance, both have used a certain area of land for the production of raw material as well as for the production of the finished commodity; for both of them a certain quantity of power (coal) was needed to bring them to market, etc. But as regards working time, not only its length, but also the intervals between different stages of production, in other words the time during which the means of maintenance and of production for the workers must be advanced, have influence on the productivity of labour.
- 75Of the two latter equations, however, each can be derived from the other with the help of the equations (4). We consequently obtain altogether 2(m + n) + 1 equations, which are independent of each other, or just as many as the number of the unknown magnitudes: x1 . . . xm, y1 . . . ym, x’1 . . . x’n, y’1 . . . y’n and p. Our problem is consequently theoretically solved. We will undertake the discussion of these equations and their discontinuities later on, when we deal with supply and demand.
- 76This is how Jevons treats the problem, except that, as in the case of exchange between two commodities, he introduces the vague concept of the marginal utility of a ‘trading body,’ by which means he believes that he is able to reduce the number of equations to only 2 x 3 = 6.
- 77This observation, which is at any rate interesting, was made by Launhardt. It is open to doubt whether any practical importance can be attached to it. As we have already several times remarked, this rule can only be generally valid, i.e. valid for all forms of functions, if it is a question of very small deviations, that is to say, if all exchanging persons are from the outset or by previous exchange in possession of approximately equal quantities of the same commodity, so that the marginal utility of the commodity (A) as well as that of the commodity (B) is already nearly equal for all of them. This, however, will not often come about in reality; for even if the marginal utility function were identical throughout, the amounts of property would nevertheless be different. From this it follows that this function can indeed be replaced by a series of different approximating functions, but not by one and the same formula,as the validity of the rule requires.
- 78The treatment of the problem of exchange given above derives from Walras. Jevons, who has also availed himself of the mathematical method, but in a less correct way, believed that he could summarize the solution in two equations by regarding all possessors of the one as well as of the other commodity as a trading body. According to Jevons, for each of these trading bodies, in respect of each of the commodities, a kind of collective marginal utility holds good, which can be regarded as a function of the possessed or acquired total supply. If A and β are the total supplies of the commodities (A) and (B), and X and Y the exchanged total quantities of these, and if the mentioned collective marginal utility is expressed by F( ),J( ),f() and j( ) respectively, we obtain
- 79In the case of exchange in the open market also, as well as in the cases treated previously, a maximum problem is solved ; but only in the sense that each of the exchanging persons (and consequently all of them together) obtains the greatest possible gain of utility which can be attained by him (or them) at the price fixed on the market. On the other hand, this would obviously not be the case if a uniform price were fixed in advance in some other way, e.g. by governmental order. That being so, only one market party, the one not favoured, could exchange until saturation was reached; but at no time could all the members of the other party, or perhaps even a single member, sell such a great amount of their goods as would be profitable for them at this price. Equilibrium on the market would then be impossible, since the supply of the favoured commodity would always exceed the demand.
- 80Still less can it be asserted that the distribution of the com modities which is most favourable economically, that is to say, the greatest possible general satisfaction, arises from free competition. If this problem is conceived in the absolute sense, its solution, as can easily be seen, requires that the marginal utility of all exchanging persons should become the same in relation to each separate commodity. But this situation will quite often lie beyond the limits of the possible exchange, as it would bring to some of the exchanging persons loss instead of profit. This, however, does not prevent the problem from being solved in the relative sense, that is to say, in so far as it is compatible with the fundamental condition of exchange. But this could obviously only happen if the individual transactions were carried out at different prices, instead of at the single joint price required by free competition.
- 81I reproduce on the next page Launhardt’s diagram, in which, certainly, the peculiarity mentioned above does not appear.Here, for the sake of greater clarity, two of these curves are drawn beneath the axis of the abscissae. If p is zero, i.e. if the commodity (A) is to be had for nothing, everybody, and consequently the possessors of (B) also, will provide themselves with it until saturation is reached, but they will not desire an infinite quantity of it. The demand curve therefore cuts the axis of ordinates at a certain distance from zero. If p increases, the demand for (A) on the part of the possessors of (B) decreases, and at a certain price this demand becomes zero.
- 82In order to simplify the mathematical treatment of this problem as far as possible, it is perhaps best to unite the different possessors of commodities not in several, but in one single group, each of whose members is already from the outset conceived as possessor of certain quantities of all these goods, and therefore, on the assumption of only three commodities, as the possessor of all three. Initially, one or two of these quantities can, of course, be zero.
- 83If we further suppose that the equilibrium prices of the three commodities, measured according to an optional standard, are pa, pb and pc, the principle of thrift (the principle of the greatest possible profit for everyone) demands that the possessor in question exchange up to the point at which, for him, the marginal utilities of the three commodities stand in the same proportion as their prices. We consequently have, if the marginal utilities of the three commodities for him are expressed by Fr( ), Gr( ) and Hr( )
- 84On the other hand one could easily introduce the condition of direct exchange, if one conceived the three proportions of exchange between (A) and (B), between (A) and (C) and finally between (B) and (C) as three magnitudes which are independent of each other. The unknowns of the problem would then be increased by one, and would then amount to 3n + 3.
- 85since all the x’ express here supply and all the y’ demand. p therefore denotes the price of the commodity (A) expressed in terms of (B); consequently or π denotes the price of the commodity (B) expressed in terms of (A).
- 86If, for instance, it is a matter of demand and supply of the commodity (A), it can generally be asserted that, if p [the price of (A) expressed in terms of (B)] increases, the demand for (A) always falls; if, on the contrary, p decreases, the demand for (A) will always increase. If we could now be certain that, on the contrary, the supply of (A), at least near the equilibrium price found [i.e. the value of p, ascertained from (10) or (11)] would increase when the price rose, and would decrease when the price fell, then the stability of the equilibrium would obviously be secured ; for in the case of an accidental deviation of the price upwards the supply would be greater than the demand; in the case of a deviation downwards, the demand would, on the contrary, exceed the supply; in both cases the inequality of supply and demand would necessarily drive back the price to approximately the earlier position.
- 87This interesting result of the theory, which was first noticed by Walras, is impugned in the well-known work by Auspitz and Lieben, who assert that ‘the simultaneous validity of both demand curves [of the commodities (A) and (B)] is founded on assumptions which contradict each other.’ In this case, the authors go on to argue, one would have to assume firstly that ‘the prices or proportions of exchange of all other articles’ excluding the commodity (B) are constant against one another; and consequently, that the prices, on both sides, of all articles excluding the commodity (A), but including the commodity (B), are constant.
- 88When the price rises, therefore, not only the demand but also the supply of the commodity in question can decrease. If, now, the demand decreases more rapidly than the supply (and therefore, on the contrary, increases more rapidly when the price falls), the stability of the equilibrium is, as can easily be seen, even in these circumstances still secured. But there is nothing to prevent from decreasing or increasing even more rapidly than ϕ(p), near the value of p in question, since supply and demand of the same commodity proceed from different persons and are consequently totally independent of each other.
- 89When the proportions of exchange of three or several (m) commodities are to be found, we obviously have to consider the total supply and the total demand of each commodity as functions of all proportions of exchange or prices of the commodities concerned. The equalization of the supply and demand of each separate commodity supplies m equations, amongst which, however, only m — 1 are independent. The variable prices are here also m — 1 in number in that, for instance, one of the commodities itself is taken as the standard of value.
- 90As regards the supply curve of the commodity (A) in particular, this has, as can be seen, a highest point and approaches afterwards the axis of the abscissae asymptotically. But although it is quite independent of the form of the demand curve of the same commodity, its intersection point with the latter can lie just as well on the right side of the highest point as on its left side (as in the figure). These two positions of the intersection point correspond to our two above-mentioned cases of stable equilibrium of the price. But this does not prevent these two curves from being able to have more than one point, and if so at least three points of intersection in common, as, for example, is shown by the dotted line [representing the demand for (A)] drawn in our figure. If this is the case, the two extreme intersection points, as we can easily convince ourselves, determine prices of stable equilibrium. The middle intersection point, on the contrary, shows no real equilibrium of prices, as was mentioned above, but only a temporary equality of supply and demand.
- 91When the proportions of exchange of three or several (m) commodities are to be found, we obviously have to consider the total supply and the total demand of each commodity as functions of all proportions of exchange or prices of the commodities concerned. The equalization of the supply and demand of each separate commodity supplies m equations, amongst which, however, only m — 1 are independent. The variable prices are here also m — 1 in number in that, for instance, one of the commodities itself is taken as the standard of value.
- 92But the matter is certainly not as simple as this. Here the well-known dictum of J. S. Mill (to which he himself, to be sure, gave quite an undue extension) is confirmed, that ‘demand for commodities is not demand for labour’ (or for the other productive services). Production requires time, and the sellers of the productive services will generally not be able or willing to await the completion of the commodities in order to secure their remuneration from the amount realized by the sale: they obtain this remuneration from the proceeds of the production periods already completed. Production will therefore, in reality, never be like the simple market; it consists rather of a series of acts of exchange performed at different times which together span the whole period from the beginning of the production to the sale of the commodity in question. Only if one takes this fact into consideration can one adequately explain to oneself the role of capital in production, that mysterious ‘productivity’ of capital, and obtain at the same time the main key to the phenomenon of capital interest. We shall discuss these questions in detail in the next chapter, where it will be our task to comment on the outstanding work done by Böhm-Bawerk. But first let us say something about the so-called law of costs in its older and newer forms.
- 93Walras sets out from the assumption that the real profit of enterprise is cancelled out by the reciprocal competition of entrepreneurs. Thus they are simply compensated for their work of managing the enterprise as other workers are, according to a measure fixed by competition. But then the assumption is made, or rather the fiction is introduced—and in this lies the weak point in Walras’s presentation—that the entrepreneurs would buy ‘on the market of the productive services’ the services needed for their production of goods, namely the use of land, the various uses of capital, and finally labour—but not against cash or commodities but simply against the promise to repay the same quantities of these services later after the conclusion of the production. But instead of really doing this, they would sell ‘on the market of the products’ the finished goods to those who offer the productive services and who appear now as consumers and, consequently, as buyers. In this way the entrepreneurs would be absolved from their promise to return the productive services as such; because the exchange value of the products must be equal to the productive services necessary for their production, if equilibrium between production and consumption is to exist and if the entrepreneurs are to have neither loss .nor profit. The productive services themselves, therefore, are here exchanged against each other ‘en fin de compte,’ as Walras explicitly remarks, and this according to the principle of marginal utility; since the existing productive services possess a certain utility and marginal utility—directly for the owners themselves, as well as indirectly, in the form of finished products, for the consumers of these products (who on their part have also to dispose of productive services).
- 94The net profit, then, remains constant, even if the period of production is lengthened to a very great extent by continuous formation of capital: a national capital of 15,000 million fl. does not yield more than a capital of 1,500 or even of 150 million fl.—provided the number of workers is always assumed to be unchanged. But if ρ increases in a greater proportion, then, in the case of an extended period of production, the net profit increases also. If, on the other hand, ρ increases in a smaller proportion, then the absolute net profit decreases with every new increase of capital and lengthening of production. If we base our calculations on the figures of productiveness given in the table, we see, for instance, that if the capital increases from 15 milliards fl. to 19¼ milliards fl., then, at the new rate of wage of 550 fl., the seven-year period would prove to be the most profitable one. But the annual profit from each worker would then amount to only (670 − 550) = 120 fl. instead of the 150 fl. obtained before, and the total net profit would, of course, diminish in the same proportion.
- 95As is well known, Thünen had already laid down a law of the level of interest, analogous to his familiar proposition which stated that the average wage depended on the ‘yield of the last worker.’ According to this law, the level of the rate of interest depends on the productiveness of the ‘last invested particle of capital.’ The agreement of this theorem with Böhm-Bawerk’s own is obvious and is rightly emphasized by the latter. Only it must be remembered that here it is always a question of the capital investments of the individual entrepreneurs only, in which case the wage can and must be assumed to be given. This theorem can by no means be applied to the increase in the national capital itself and to the surplus return brought about thereby.
- 96As is well known, Thünen had already laid down a law of the level of interest, analogous to his familiar proposition which stated that the average wage depended on the ‘yield of the last worker.’ According to this law, the level of the rate of interest depends on the productiveness of the ‘last invested particle of capital.’ The agreement of this theorem with Böhm-Bawerk’s own is obvious and is rightly emphasized by the latter. Only it must be remembered that here it is always a question of the capital investments of the individual entrepreneurs only, in which case the wage can and must be assumed to be given. This theorem can by no means be applied to the increase in the national capital itself and to the surplus return brought about thereby.
- 97However, the above-mentioned formula could also quite well be chosen as a point of departure, and is even the most natural starting point if we wish to take compound interest into consideration. But in this case, if it is a question of a continuous production, the labour element and wage element which have been added in each case must be taken into consideration too.
- 98The boundary between fixed and variable capital is in this case really abolished. The whole capital, at least in so far as it is ‘turned over’ during the period of production, will subsequently appear in the form of money and means of subsistence, and, when no account is taken of ground-rent and the like, will be paid out in wages up to the last penny, but, as Böhm-Bawerk rightly remarks, not in one year, but during a period of time which, incidentally, amounts to half the length of the period of production.
- 99Böhm-Bawerk’s theory forms, as was remarked above, only one element in the complete determination of the level of interest. The main reason for this is that the operation of natural forces, i.e. the services of the land, are not taken into consideration or, rather, are regarded as free. However, it would not be impossible to consider this factor also, particularly as the services of the land with regard to capital behave, in several respects, exactly like labour. The landowners, too, get their rent in advance, before the products are ready for the market. We can even assume, for the sake of simplicity, that ground-rent is paid by instalments, just as wages are; so that here also the necessary advance of capital comprises, on an average, half the length of the period of production.
- 100Discussion of the equations set forth above would now reveal the true relationship between capital-interest, wage and ground-rent—in so far as the assumptions which we have made are in approximate agreement with reality.
- 101If we wish to take into consideration capital-interest as well here, we have simply to multiply the right side of the equations by . But t must here be assumed to be a constant, otherwise a third relation is necessary, namely equation (21), which now turns into
- 102Let us now suppose that beside this economy there exists another, where in the same way another commodity—again, a single commodity only; for instance, linen—is produced. Exchange between the two economies is completely free, but capital and labour cannot be transferred from one to the other. For each of these two economies there would then exist a system of equiiibrium equations similar to system (20)-(24). The constants of the equations—the number of workers, the area of land and the capital—as well as the form of the function of productivity p (or q) are, however, different for both economies. Let the above-mentioned magnitudes be A1, B1, K1 and p1 for one economy and A2, B2, K2 and p2 for the other. When these magnitudes are inserted in equations (20)-(24) instead of A, B, K and p, we obtain from each of these equilibrium systems, by elimination of the remaining unknowns, first the length of the period of production t in question, then the values of the magnitudes l, r and z which we require to know. If these values are t1, l1, r1 and z1 for the first economy and t2, l2, r2 and z2 for the second, then A1l1 + B1r1 + K1z1 and A2l2 + B2r2 + K2z2 respectively express the quantities of goods which are produced every year in the two economies. Since, furthermore, the distribution of capital property and landed property within each economy must be assumed to be constant, we know now how much of this production falls to each person’s share. Of these quantities of goods, one part of the yearly production of one economy is exchanged for one part of the yearly production of the other economy. And this exchange takes place exactly according to the laws of exchange developed previously. If, for instance, some proportion of exchange (the price on both sides) is first of all assumed at random, then each of the owners of corn—that is to say, each worker, landowner and capitalist of the first economy—offers, at this price, a certain quantity of the corn which has fallen to his share for the year in exchange for a corresponding quantity of linen—i.e. just so much that the ratio of the marginal utilities of corn and linen (appropriate to the quantities of corn and linen which have been consumed during the year) is made equal to the ratio of the prices, that is, the proportion of exchange. By addition of these partial quantities, we obtain the yearly supply of corn and the yearly demand for linen on the part of the owners of corn—at the price in question. In exactly the same way a total supply of linen and a total demand for corn arise on the other side, at the same price. If supply of, and demand for, the one commodity are equal, and consequently also equal with regard to the other commodity, equilibrium is attained; if not, a shifting of prices must take place. But this change has obviously no influence on the proportion of production on both sides. The problem of international trade, of which we have here presented the simplest pattern, is therefore, in fact, much less complicated than that of internal trade. Before long an average proportion of exchange will establish itself. Afterwards, this proportion is maintained practically unaltered from year to year, and is characterized by the fact that for every member of both economies the proportionality between marginal utility and price of both commodities is fulfilled. In this case, of course, it is not necessary that each individual member should appear in the exchange market. Without essential change in the proportions, the exchange can be transacted by all the capitalists, or by a few of them; so that wage, ground-rent and capital-interest, too, can be paid in both kinds of goods or in any conventional medium of exchange (for instance, paper money), provided only the above-mentioned proportion of marginal utility is thereby realized as the final result.
- 103with their derivatives in respect of t1, h1, t2 and h2 (altogether six equations), must be fulfilled.
- 104where A, B and K stand for the number of workers, area of land and capital existing within the whole economy, the latter expressed in terms of corn. We therefore have altogether thirteen equations with the same number of unknowns, but only on the assumption that the proportion of exchange of both commodities is known.
- 105Here, p1 and p2 express values, that is to say, they give the exchange value of the yearly production (as functions of t and h). But, of course, in the first instance only the number or quantity of the products in question is, in fact, established by the functions of productivity, which were assumed to be known on both sides. Since now the corn has been taken as our standard of value, p1—the value of the production of corn (per year and worker)—is dependent merely on t1 and h1; the function p2, on the other hand, includes, in so far as it is supposed to give the exchange value of the production of linen, another factor π, namely the proportion of exchange of both commodities or the uniform price of linen expressed in terms of corn. But this proportion of exchange cannot be assumed to be known here; rather, our task is to show how it is determined by the interplay of all the economic forces. We therefore still have one unknown in excess of the number of equations and need one more of the above-mentioned independent equations, if the problem is to be completely solved.
- 106when x and y respectively stand for his yearly consumption of these goods. But these quantities must now fulfil the law of marginal utility, so that, if f( ) and g( ) stand for the marginal utility functions related to the quantity of the yearly consumption,
- 107Since the forms of the functions f( ) and g( ) must be assumed to be known, x and y can be determined from the last two equations, that is to say, can be expressed in terms of l, r, z and π. When this operation is carried through for each member of the economy, we have also found the total consumption of, or demand for, the goods concerned, and, according to what has been said above,
- 108However, this circumstance will only make necessary a larger number of equations. With every new commodity which must be taken into consideration, six new unknowns enter the problem, according to our above-mentioned scheme; since for each commodity the most profitable period of production and proportion of the use of land, the number of workers, area of land and capital employed in its production, and finally the exchange value of the commodity are to be determined. If there are n goods and one of them is taken as the standard of value, the number of unknowns will consequently be 6n + 2. For their determination the laws of production give, as can easily be seen, 5n + 3 independent equations, whilst the missing n—1 equations are obtained from the laws of exchange—for instance, by means of a formula expressing the fact that, at the n— 1 prices of the goods, which must be determined and expressed in terms of one of them, the quantity of each commodity yearly consumed or demanded must be equal to its yearly production, and by taking into consideration that only n—1 of the n equations laid down in this way are independent.
- 109However, this circumstance will only make necessary a larger number of equations. With every new commodity which must be taken into consideration, six new unknowns enter the problem, according to our above-mentioned scheme; since for each commodity the most profitable period of production and proportion of the use of land, the number of workers, area of land and capital employed in its production, and finally the exchange value of the commodity are to be determined. If there are n goods and one of them is taken as the standard of value, the number of unknowns will consequently be 6n + 2. For their determination the laws of production give, as can easily be seen, 5n + 3 independent equations, whilst the missing n—1 equations are obtained from the laws of exchange—for instance, by means of a formula expressing the fact that, at the n— 1 prices of the goods, which must be determined and expressed in terms of one of them, the quantity of each commodity yearly consumed or demanded must be equal to its yearly production, and by taking into consideration that only n—1 of the n equations laid down in this way are independent.
- 110This is, of course, not correct. For certain productions there is at any time only a very limited number of workers who are employable at all, since the business requires either special abilities or a longer training. In order that this circumstance may be taken into consideration, the existing workers must be divided into groups, and the wage for each group, which can then be very different for the various groups, must be ascertained separately. But once the boundary-lines of these groups are drawn, the number of independent conditioning equations (Bedingungsgleichungen) will here obviously increase also to the same extent as the number of the unknowns.
- 111Finally, in my opinion, produced goods also, in so far as they are continuing sources of rent, should be taken into consideration here. In the stationary economy such goods are not produced at all, but kept in the same good condition. The capital investment in question itself belongs to past time and need no longer be considered. The net interest on this capital has consequently the precise character of a rent, since necessary repairs and maintenance work, as well as running costs, are imposed on the capitalist who uses these goods.
- 112If in all these relationships a certain rate of progression may be assumed to be given, then it is clear that equations of production and exchange can be laid down. We have then, so to speak, a problem of dynamic equilibrium instead of a problem of static equilibrium with which to deal.
- 113It would be quite a different matter to try to lay down laws for determining the rate of progression itself. I personally make no attempt in this direction. How far present-day political economy still is from being able to treat these situations in an exact way, becomes clear if we consider the fact that economists are still by no means agreed as to the extent to which such a progression of society is advantageous or not. In particular, so far as I know, the question has never been raised in economic writings, what size of population is economically most profitable when the amount of capital, size of the area of land, etc., are given. If, therefore, these problems are to be solved according to the principle of the greatest utility, it is obviously a serious drawback that there is not even common agreement in what direction economic advantage or disadvantage in fact lies. If, on the other hand, we assume that changes of population are not regulated according to the principle of what is economically most advantageous (in the widest sense of the word), but are regulated now and for ever merely by blind natural instincts, then at least we are on firm ground. In that case, however, we should have no alternative but to accept Ricardo’s doctrine of the natural wage—that is to say, the smallest possible wage—as a fact beyond dispute. Altogether, population questions are unfortunately still neglected by the economists of practically all schools. This is regrettable from the theoretical point of view, but still more regrettable, of course, from the practical point of view.
- 114The doctrine set forth here has much in common with the theory presented in Léon Walras’s Élements d’économie politique pure. There, too, equations of production are laid down and combined with the equations of exchange previously obtained. But, as was remarked above, Walras calls ‘capital’ and treats as ‘capital’ only durable goods, but not raw materials and half-finished products and not the means of subsistence of workers. What the owner of the circulating capital advances to the workers, landowners, etc., is therefore not treated by Walras as capital at all. It is therefore implicitly assumed by Walras that workers and other producers maintain themselves during production and receive remuneration for their productive services from the proceeds of the products in question only after completion of the production. This is obviously incorrect. In this interpretation the true rôle of capital in production is completely overlooked. A necessary consequence of this is the peculiar fact that these equations of production and exchange can give no information at all about the level of the rate of interest. If only durable goods are regarded as capital, then a certain rent is fixed for each group of these by the above-mentioned equations, but not the capital value of the goods itself, nor, consequently, the rate of interest either, ‘le taux du revenu net.’ This is explicitly admitted by Walras; but he asserts that, in order to determine the level of interest, it is necessary to turn from the investigation of a stationary economy to the investigation of a progressive one, where new interest-bearing capital goods are produced, whose capital value can be determined from the production costs. This is certainly incorrect. In the stationary economy, too—even if we assume that all the means of production are indestructible—a rate of interest of the circulating capital will undoubtedly establish itself, precisely because the lengthier methods of production prove more profitable. Walras’s theory of production and capital consequently rests upon incorrect assumptions and cannot be regarded as definitive. However much it may—in several respects—testify to its author’s acuteness, the- real essence of the matter has not become clear to him. The merit of having taken the decisive step forward belongs in this field to Jevons and, above all, to Böhm-Bawerk.

