
Theory of Money and Fiduciary Media
8. Expansionist Monetary Policies and the Trade Balance
David Howden
Expansionist Monetary Policies and the Trade Balance
Much conventional wisdom of modern international economics can be condensed into two statements:
1. currency depreciations improve a country’s trade balance, and
2. trade deficits cause currency depreciations.
Historians of economic thought will notice that the first claim is not confined to “modern” economics. The sixteenth century advocates of mercantilism argued for similar policies.1 In the mercantilist view, international trade is a zero-sum game, and the winning side will be the one with a trade surplus. A country can achieve a trade surplus via specific policy prescriptions, among them controlling imports, promoting exports, or depreciating one’s currency.
Ludwig von Mises devoted one section of his Theory of Money and Credit to questioning the claim that exports can be stimulated through currency depreciation.2 Mises’s approach mostly rests on a long-run neoclassical analysis in which price level rigidity is largely excluded from the analysis. In this chapter we will first summarize Mises’s core argument. We will then consider objections to it, largely based on price-level considerations. Finally we will note that Mises’s original claims against policies aimed at depreciating the currency and promoting exports are actually stronger than he made in 1912, though never stated in a cohesive and complete manner.
Exchange Rates and the Trade Balance: The Conventional View
The conventional analysis of the trade balance starts with David Hume’s price-specie-flow mechanism to draw conclusions for exchange rate movements. Start with two countries with their trade balances in equilibrium, and using the same currency (in this example we will use gold, though this is not essential to the argument). Country A reduces its demand for, and hence imports of, country B’s goods. Immediately country A will reduce its gold transfers to B, thus increasing the money supply in A relative to B. This relative contraction of the money supply in B coupled with the increase in the money supply of A makes prices rise, on average, more quickly in country A than B. This incentivizes citizens from A to increase their purchases from B. The increased demand thus stops the gold outflow from B, stabilizing the trade balance.
Several immediate effects can be discerned. First, the contraction in the money supply in country B caused a deflation in the price level. This deflation allowed for an increase in competitiveness relative to country A, and stimulated B’s exports. On the other hand, the expansion of the money supply in country A reduced its own competitiveness, and halted its exports to country B. Under the neoclassical view of perfectly flexible prices, this money outflow gave rise to price deflation, allowing for the balance of payments to remain equilibrated.
Once we move away from an international commodity standard, the situation depends on the exchange rate regime, whether flexible or fixed.3
Trade imbalances are self-correcting under flexible exchange rates. Assume that country A runs a trade deficit against B. Citizens in A must be selling their currency to purchase B’s currency, in order to purchase that country’s goods. The increased buying pressure in country B increases the price of its goods, disincentivizing A’s citizens from continuing to import from it. An equilibrium obtains where trade is balanced again, but at an exchange rate that has appreciated for B relative to before.4
This example illustrates the two statements concerning international economics that we opened with. The currency depreciation in country A improved its trade balance (by decreasing its imports). This currency depreciation was itself originally caused by the trade deficit against B, whereby A’s citizens needed to sell A’s currency to purchase B’s.
From this example also comes an assumingly simple corollary. A country running a trade deficit can easily cure this through policy. A monetary policy that results in a depreciated exchange rate will increase foreign demand for a country’s goods, while simultaneously reducing domestic demand for foreign goods. The net result is a trade deficit improvement.
Currency depreciation as a policy tool to combat a trade deficit is increasingly favored by economists as a substitute for other measures. As monetary responses, exchange rate depreciations are only one of three measures that can be used, alongside domestic price level deflation and capital controls. The mainstream view today is that capital controls interfere with important trade flows and should be used only as a last resort, while price level deflation may only be reasonable in the long run (and may not even then be desirable). On the nonmonetary side of policies, tariffs and quotas, export promotion (through subsidies) and import substitution (through targeting domestic producers) can all limit a trade imbalance. They also come with the baggage of deadweight losses or rent-seeking questions surrounding what industries to specifically target. Manipulation of the exchange rate has come to be seen as one option that evades these problems, and is straightforward to implement via a central bank.
Mises’s Argument Revisited
In chapter eight of the Theory of Money and Credit, Mises takes the conventional balance-of-payments analysis and augments it to account for the process through which international competitiveness can be regained. Along the way, he also foreshadowed the Lucas Critique by over six decades.5
Mises is keen to note that any policy aimed at depreciating the exchange value of a currency to stimulate exports will likely be self-defeating.6 His rationale invokes real exchange rates—nominal rates adjusted for changes in money’s purchasing power—to make the point.
Depreciating the exchange rate on the foreign exchange market can only be achieved by reducing its purchasing power domestically relative to a foreign currency. Such an inflationary monetary policy thus has a two-pronged effect. On the one hand it increases the price of the good in question in nominal domestic currency terms through price inflation. On the other hand it decreases the number of foreign currency units necessary to purchase a unit of domestic currency. In equilibrium the effect would be a draw, as the effects of one cancel against the other.
As Mises notes, the “beneficial effects” on trade that a depreciated currency provides last only so long as the domestic price inflation comes either, (1) later than the depreciation on the foreign exchange market, or (2) at a slower rate than the depreciation of the currency. Inflationists aiming to increase international competitiveness through this deprecation could only see their policy maintained through continual diminutions of the currency’s purchasing power. It is doubtful that lenders would continually lend money in this currency while cognizant of their ensuing purchasing power loss—it may be possible to fool some of the people some of the time, but eventually expectations will catch up and make the real price of the country’s goods more expensive than before the policy was enacted.
If the effects of an export-promoting monetary policy are null in the long run, Mises raises another complication—the policy itself must be kept unapparent from the market for its effectiveness, by its purveyors’ own reckoning, to even be possible.
That this depreciation in the value of money must be unforeseen by individuals for the policy’s effectiveness is now apparent. Mises builds on the still relatively recent work of Irving Fisher7 to explain why it is that any inflationary measure aimed at reducing the value of money must be shrouded from the market.8 Specifically, Mises9 cites and builds upon the Fisher effect whereby any expected loss in purchasing power by a creditor will be compensated by an ex ante higher requested interest rate.10 The extension is that one can never know in advance the exact position of the creditor and debtor—who it is that gains at the expense of the other—because one can never know in advance the path that price inflation will take. Hence, it is possible that inflation possibly can benefit a debtor, if the ex ante interest rate was not increased sufficiently to cover the creditor’s loss of purchasing power.
Short- and the Long-run Considerations
While Mises invokes a long-run flexible price stance in his treatment of the balance of trade, we may now relax this assumption. The neoclassical tradition that Mises worked within assumed prices to be fully flexible, or at least did not focus on short-run phenomena during which prices could be “stuck” in place.
The modern view holds that currency depreciations can improve the trade balance in the short run, as prices adjust slower than exchange rates. Any increase in the money supply will affect the exchange rate instantly, based upon the expectation that future prices will increase. In the present, however, prices will require some time to adjust, typically as the new money will take time to work its way through the economy to affect prices.11 As a consequence, the real exchange rate will depreciate in the short run to provide an advantage for export industries, but in the long run this advantage will be slowly removed as the price level catches up.12
Such thinking is spurious for two primary reasons.
The first issue is one of over-aggregation. Depreciations of the real exchange rate are enacted by increasing the money supply, thus placing upward pressure on all prices. As the real exchange rate (q) is given as
q = E (p/p*),
where E is the nominal rate, P the domestic price level and P* the foreign price level, any alteration to the money supply is aimed at affecting the general price level to promote a real depreciation.13
The first issue that we may raise is the overly aggregative nature of the variables at hand. What matters is not the respective general price levels of two countries, but rather the specific prices for the goods being purchased. For example, the trade deficit in Spain today and the trade surplus in Germany is not the result of all goods being x-percent more expensive in Spain than in Germany. Some goods in Germany will be less expensive (cars and elevators, for example) while others will be more expensive than in Spain (wine and olives, for example). The trade surplus that Germany has is not the result of being more cost effective in all goods, but is instead the aggregate result of some goods being in a trade surplus offsetting those that have a deficit position. In trade relations it is never the brute movements of aggregate numbers that define the important relations, but rather the “interrelated variations in the complex of individual cash balances, incomes, and prices.”14
On the other hand, the effectiveness of a monetary expansion in depreciating the real exchange rate must also assume the long-run neutrality of money. In this way, any changes in the money supply affect the general price level, but not the individual array of prices. This is questionable for three reasons.
First, as the analysis is short-run given the assumption of sticky prices, any assumption of money’s neutrality must also be short-run. While Austrian economists are unified in the belief that money is never neutral, most mainstream economists would also agree that it is only in the long run that this neutrality reigns.15 A bifurcation occurs whereby the assumption is that the way prices behave is short run as it concerns price inflation, yet long run in how the price vector is affected by monetary policy.
Second, the assumption that the effects of monetary policy are neutral is questionable.16 The crux of the Austrian business cycle is based on the fact that monetary policy results in “Cantillon” effects. As money is necessarily injected “somewhere” in the economy, it is only through a time-consuming process that its effects (i.e., price inflation) alter prices. That it will affect prices asymmetrically arises as a physical result of the lengthy process for money to filter through different stages of production17 and also because the further away from the source freshly injected money strays, the less knowledge entrepreneurs have of its nature, effects and sustainability.18
The third questionable aspect, and a consequence of the first two, is the question of what price is “stuck” in the short run. Not all prices are equally sticky, resulting in different price adjustments as new money works its way through the economy.19 In this sense, claiming that an increase in the money supply will bring a real depreciation because the general price level is sticky in the short run misplaces a key aspect—as the general price level can only be comprised of its individual component prices. Any monetary policy will alter the individual constellation of prices, and while it is true that the general price level will also increase, not all individual prices will do so uniformly.
The Secondary Effects of Depreciation
The fact that not all prices will react uniformly to monetary policy is significant as it raises secondary considerations. Chief among these concerns the business cycle, while others concern the effect on the balance of trade if such a policy is undertaken.
The traditional Austrian business cycle commences with new credit being injected into the economy for commercial purposes. As interest rates are depressed below their natural levels, long-term projects gain the appearance of profitability. Entrepreneurs are enticed to invest in longer-dated projects, thus causing prices to inflate at the higher orders of production relative to the lower orders (i.e., producers’ prices increase faster than consumers’ prices).20 The result has one of two options, neither one conducive to growth.
On the one hand, if entrepreneurs have undertaken plans inconsistent with the amount of real savings (i.e., too many projects are undertaken relative to savings), as the boom culminates a rush to borrow the scarce savings will drive up interest rates. Short-term interest rates surge on the eve of the bust as borrowers scramble for the necessary but now recognizably scarce funds.21 As interest rates increase, higher order goods’ prices are negatively affected as they are capitalized at a higher interest rate.22 Alternatively, if a continued loose monetary policy prohibits upward pressure on interest rates, producers’ prices will surge as a scramble by entrepreneurs, not for scarce monetary funds, but for the scarce physical goods to complete projects.
The importance of this for the task at hand is the effect on trade flows from this policy. The expansionary monetary policy has been undertaken with the aim of depreciating the real exchange rate, in hopes of promoting the domestic country’s export-based industries. Yet four detrimental side effects will result.
First, the reallocation of spending from the late to early stages of production when credit is directed to commercial borrowing implies that less domestic attention is given to producing consumers’ goods. This shift can either occur with an increase in total expenditure directed at the higher stages, or with no aggregate increase and only a funding reallocation between stages. For countries lacking the input factors for higher-order production (natural resources, for example), imports can surge to meet the increased demand. Take the case of the United States since 1980 to 2000 (Figure 1). A continual monetary expansion and reduction in interest rates during the great moderation enticed entrepreneurs to move investment to higher stages of production. The increased demand this created on the country to import natural resources such as oil increased the trade deficit throughout the period culminating in the dot.com bust in 2000.
Second, a credit-induced boom increases the demand for all goods—imports as well as those domestically produced. If the goods demanded come from overseas, the result is a worsening trade balance. Since there is no reason to believe that an expansionist monetary policy will alter the demand foreigners have for the domestic country’s goods, the trade balance will worsen. Moreover, if the goods demanded domestically are also sourced domestically, price pressure will build on these goods. As these prices increase, foreigners are disincentivized from purchasing them. In this case the trade balance worsens because exports are stifled. Alternatively, if nominal incomes are not increased through an inflationary monetary policy, individuals will have to restrict their consumption of both domestically produced and imported goods. In this first case exports would increase and in the second case imports would decline.23 In both cases the non-expansionary monetary policy improves the balance of trade.
Third, as a credit-induced boom creates malinvestments along the domestic structure of production, the home country may find itself increasingly needing to turn to foreign markets to supply it with goods. Take the example of the United States during its recent housing boom from 2002–2007. As the structure of production became heavily skewed to producing higher order goods, mostly in industries related to housing, other common goods had to be sourced from foreign countries due to a lack of domestic productive capacity. The net result was a worsening trade balance, as imports increased while exports were unaffected.
The fourth and final point is that only the end of a credit-induced boom will turnaround a trade deficit set in motion by an expansionary monetary policy. As the boom created either the illusion of increased wealth or an actual increase in unsustainable credit-based wealth, the decrease in income during the ensuing bust will reverse this trend. The reason is that the decrease in income during the cleansing bust will reduce demand for all goods—both domestically and foreign produced. Yet provided that foreigners are not also undergoing a simultaneous recession, demand for the home country’s exports will remain unaffected. The net result will be an improvement in the balance of trade.
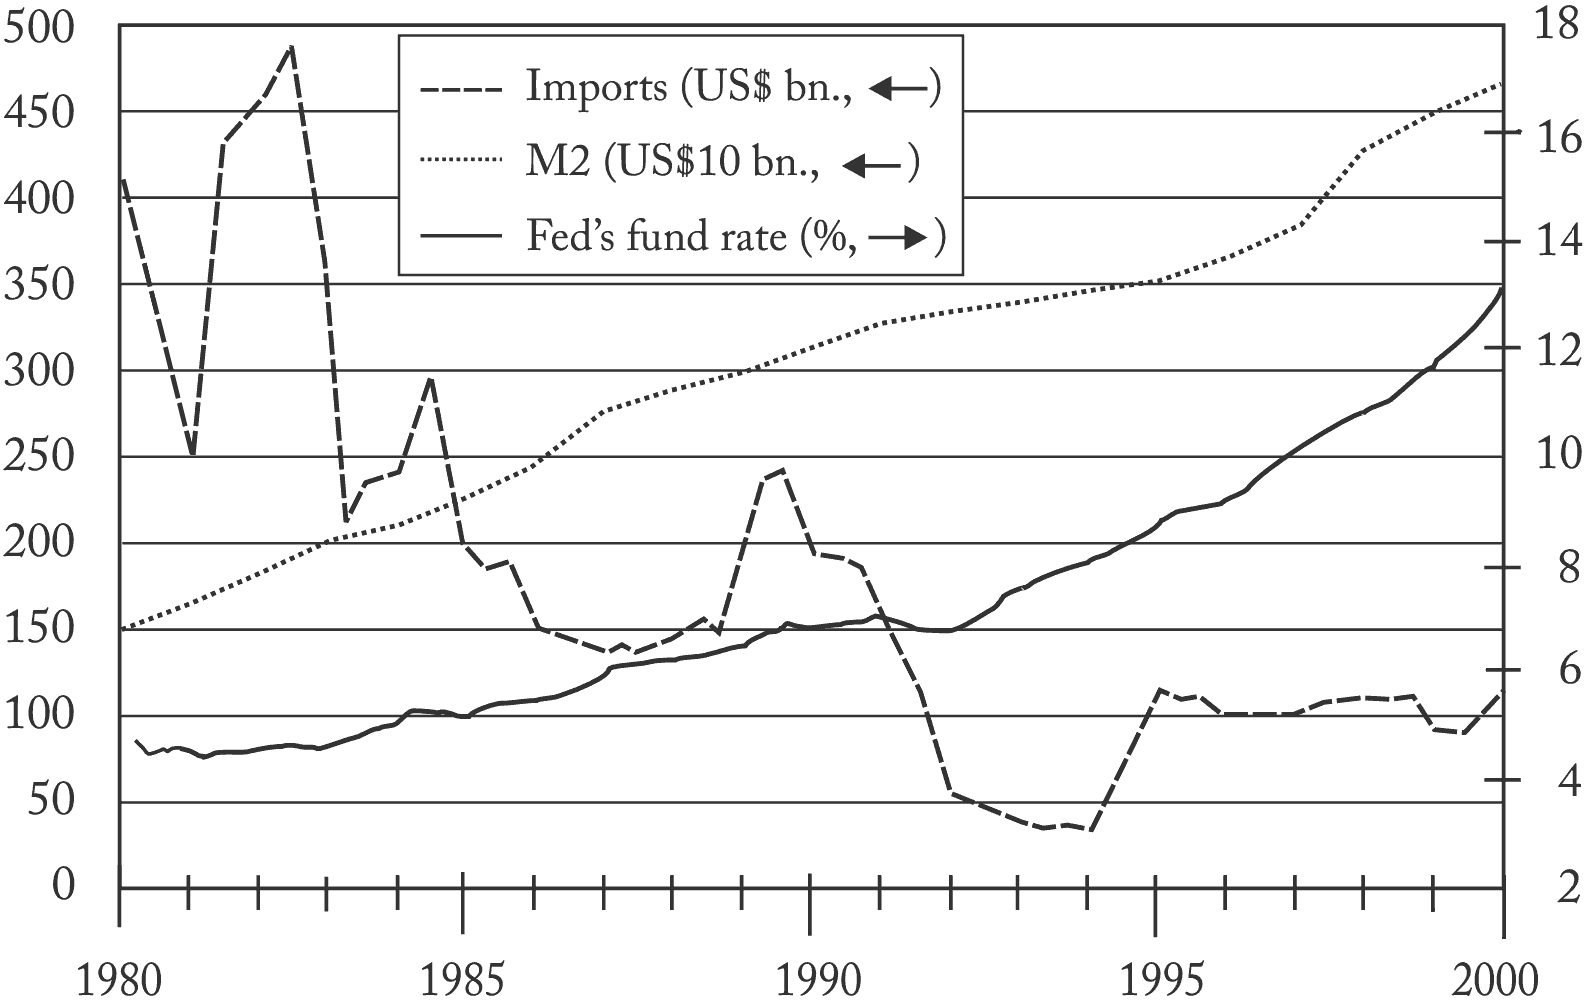
Figure 1
U.S. Imports, Money Supply and Federal Reserve Discount Rate
Source: Federal Reserve Bank of St. Louis, FRED
Concluding Remarks
Mises’s analysis in the Theory of Money and Credit of expansionist monetary policies to aid a country’s trade position is lucid and ahead of its time in terms of the attention afforded to expectations, prices and exchange rates. I noted in the introduction, however, that Mises’s24 claims against such policies were less strong than is warranted given his other contributions. With the completion of his business cycle theory nearly four decades later, we can now integrate the analysis into a unified whole.
The idea that an expansionary monetary policy can be beneficial in promoting exports must assume that the domestic price level increases slower under such a policy than the nominal exchange rate. As conventional wisdom ranks expectations and financial variables as faster adjusting to shocks than real variables in the short run, such a policy can only be effective in the short run. As prices adjust to the inflationary policy, any benefits accruing to the real exchange rate are reversed.
Mises latched onto this key insight and concluded that any expansionist policy aimed at improving a country’s balance of trade would be self-defeating.
Yet there are secondary considerations that would not become apparent until he more thoroughly developed his business cycle theory. Any expansionary monetary policy also alters the base rate of interest permeating the economy, forcing it to diverge from the natural rate. The two consequences—malinvestment and over-consumption—affect the balance of trade in separate ways.
As entrepreneurs are deceived about true savings preferences they undertake projects of longer duration than would otherwise be the case. Economic activity shifts from the lower orders of production (those closer to consumption), to those at the higher orders. Note that this shift may occur with no change in the overall level of economic activity or aggregate spending. Countries that lack the necessary input factors to fuel this new production in the higher orders will see their trade account worsen as imports are necessary to make up the difference.
Consumers, for their part, are incentivized to save less and consume more as interest rates decline lower than would otherwise be the case. In this way, consumption increases relative to what it was before the boom and also relative to what is sustainable given the production plans of producers. If the productive shift moves to sufficiently high orders there will be a relative dearth of consumers’ goods available to meet consumers’ needs. In the most recent boom in the United States from 2002–2007 we could see this was apparent as producers moved to the higher order production good of housing, along with research and development (in lieu of the “middle” order production of basic capital goods, such as infrastructure). As a consequence American consumers imported the goods that were necessary to meet their over-consumptive patterns. A sharp trade deficit developed.
Perhaps the most important conclusion is that the necessary bust following the credit-induced boom will move the balance of trade to a more sustainable position. As the production and consumption patterns during the boom are unsustainable, they will eventually be reversed. This reversal will be accompanied by either: (1) increasing interest rates in a scramble for funding now realized to be scarce, or (2) an increase in factor prices, particularly commodity or basic input prices. Either of these events will have the effect of reducing the trade deficit sustained by the expansionary monetary policy.
As interest rates increase, longer-dated investment projects are divested from in favor of shorter-term projects. This shift favors expenditure on domestically produced goods—infrastructure projects, for example—at the expense of imports. As factor prices increase, projects dependent on imported goods will also increase, disincentivizing consumption of them. As consumption of imported goods decreases the trade deficit will gradually improve.
The effects of an expansionary monetary policy on the trade balance of a country are not only counter to what the advocates state, they are also detrimental in the sense that they will set in motion a credit-induced boom. This boom has the unfortunate side effect that it is unsustainable, and also that it actually worsens the balance of trade by the production and consumption patterns it incentivizes. A cleansing recession will not only undo the malinvestments of the previous boom and return consumption patterns to sustainability, but will also rectify an unsustainable trade deficit.
References
Bagus, Philipp, and David Howden. 2010. “The Term Structure of Savings, the Yield Curve and Maturity Mismatching.” Quarterly Journal of Austrian Economics 13, no. 3: 64–85.
——. 2011a. Deep Freeze: Iceland’s Economic Collapse. Auburn, Ala.: Ludwig von Mises Institute.
——. 2011b. “Monetary equilibrium and price stickiness: Causes, consequences and remedies.” Review of Austrian Economics 24, no. 4: 383–402.
Blanchard, Olivier. 1990. “Why Does Money Affect Output? A Survey.” NBER Working Paper No. 2285.
Cwik, Paul F. 2005. “The Inverted Yield Curve and the Economic Downturn.” New Perspectives on Political Economy 1(1): 1–37.
——. 2008. “Austrian Business Cycle Theory: A Corporate Finance Point of View.” Quarterly Journal of Austrian Economics 11, no. 1: 60–68.
Davidson, Paul. 2002. Financial Markets, Money and the Real World. Cheltenham, U.K.: Edward Elgar.
Fisher, Irving. 1907. The Rate of Interest. New York: MacMillan.
Garrison, Roger W. 2001. Time and Money: The Macroeconomics of Capital Structure. London: Routledge.
Hayek, Friedrich A. [1937] 1971. Monetary Nationalism and International Stability. New York: Augustus M. Kelley.
——. [1976] 1990. Denationalisation of Money—The Argument Refined: An Analysis of the Theory and Practice of Concurrent Currencies. 3rd ed. London: The Institute of Economic Affairs.
Howden, David. 2010. “Knowledge Shifts and the Business Cycle: When Boom Turns to Bust.” Review of Austrian Economics 23, no. 2: 165–82.
Howden, David, and Brenna Kajikawa. 2012. “Japan’s Blessing of a Strong Currency.” Ludwig von Mises Institute Daily Article, March 2nd. [Available] http://mises.org/daily/5928/The-Blessing-of-a-Strong-Currency
Lucas, Robert E. 1976. Econometric Policy Evaluation: A Critique. Carnegie-Rochester Conference Series on Public Policy 1, no. 1: 19–46.
Machlup, Fritz. 1932. “The Liquidity of Short-Term Capital.” Economica 12, no. 37: 271–84.
Mises, Ludwig von. [1912] 1971. The Theory of Money and Credit. H.E. Batson, trans. Irvington-on-Hudson, N.Y.: The Foundation for Economic Education.
——. [1928] 2002. “Monetary Stabilization and Cyclical Policy.” In On the Manipulation of Money And Credit. Bettina Bien Greaves, Jr., and Percey L. Greaves, Jr., ed. and trans. Auburn, Ala.: Ludwig von Mises Institute. Pp 63–179.
——. [1938] 1990. “The Non-Neutrality of Money.” In Money, Method and the Market Process. Richard M. Ebeling, ed. Norwell, Mass.: Kluwer Academic Publishers.
——. [1949] 1998. Human Action: A Treatise on Economics. Auburn, Ala.: Ludwig von Mises Institute.
Rothbard, Murray N. [1962] 2004. Man, Economy and State. Auburn, Ala.: Ludwig von Mises Institute.
——. [1995] 2006. Economic Thought Before Adam Smith: An Austrian Perspective on the History of Economic Thought, Volume I. Auburn, Ala.: Ludwig von Mises Institute.
Salerno, Joseph T. [1982] 2010. “Ludwig von Mises’s Monetary Theory in Light of Modern Monetary Thoughts.” Reprinted in Money, Sound and Unsound. Auburn, Ala.: Ludwig von Mises Institute. Pp. 63–118.
——. [1994] 2010. “International Monetary Theory. Reprinted in Money, Sound and Unsound. Auburn, Ala.: Ludwig von Mises Institute. Pp. 63–118.
David Howden is chair of the department of business and social sciences, and associate professor of economics at St. Louis University, at its Madrid Campus.
- 1The other three treatises are Socialism (Indianapolis: Liberty Fund, 1981), Human Action (Auburn, Ala.: Mises Institute, 1998), and Theory and History (Auburn, Ala.: Mises Institute, 1985). See the complete Mises bibliography at http://mises.org/misesbib.asp. For general biographical information on Mises see Murray Rothbard, Ludwig von Mises: Scholar, Creator, Hero (Auburn, Ala.: Mises Institute, 1988), Israel Kirzner, Ludwig von Mises: The Man and His Economics (Wilmington, Del.: ISI Books, 2001), and J.G. Hülsmann, Mises: The Last Knight of Liberalism (Auburn, Ala.: Mises Institute, 2007).
- 2Keynes had written a book review of Mises’s treatise, stating it “is the work of an acute and cultivated mind. But it is critical rather than constructive, dialectical and not original. The author avoids all the usual pitfalls, but he avoids them by pointing them out and turning back rather than by surmounting them.” (Economic Journal, September 1914, p. 417). Sixteen years later he stated that “in German, I can only clearly understand what I know already!—so that new ideas are apt to be veiled from me by the difficulties of language.” Keynes, A Treatise on Money (London: Macmillan, 1930), vol. I, p. 199, note 2.
- 3The 1953 edition (New Haven, Conn.: Yale University Press) included an additional fourth part on “monetary reconstruction” that Mises had written for this new edition. In that form the book was published again three more times: 1971 (Irvington-on-Hudson, N.Y.: Foundation for Economic Education; second print in 1978), 1981 (Indianapolis: Liberty Fund), and 2009 (Auburn, Ala.: Mises Institute).
- 4Several Spanish translations (La Teoría del Dinero y Del Crédito) have been made: one by Antonio Riaño, published in 1936 (Madrid: M. Aguilar), one by José Ma. Claramunda Bes (Barcelona: Ediciones Zeus, 1961), and one by Juan Marcos (Madrid: Union Editorial, 1997).
- 5The Japanese translation was made from the second German edition by Yoneo Azuma: Kahei oyobi Ryütüjshudan no Riron (Tokyo: Jitsugyo no Nipponsha, 1949) and re-published in 1980 (Tokyo: Nihon Hyöron-Sha).
- 6Translated by H.P. Yang (Taiwan: Taiwan Bank, Economic Research Department, 1969).
- 7The Russian translation, along with annotations, was made by G. Sapov who used both the American edition and the second German edition: Теория денег и кредита (Chelyabinsk: Sotsium, 2012).
- 8The French edition (La Théorie de la monnaie et du crédit) is incomplete and only available on the Internet (http://herve.dequengo.free.fr/Mises/Tmc/TMC_1_1.htm). A print edition is forthcoming along with a preface from Antoine Gentier (Paris: Editions de l’Institut Charles Coquelin).
- 9Brad Delong, “Paul Krugman Asks a Question: On the ‘Austrian’ Hatred of Fractional Reserve Banking, Paper Money, etc. Weblogging” (http://delong.typepad.com/sdj/2012/09/paul-krugman-asks-a-question-on-the-austrian-hatred-of-fractional-reserve-banking-paper-money-etc-weblogging.html#more; accessed on 3 October 2012, at 9h32 CET)
- 10On the shortcomings of the Batson translation, see chap. 1, below.
- 11He calls money also “money in the narrow sense.” Most economists today call it “base money.” Notice that Mises argued that the essential function of money is to serve as a generally accepted medium of exchange. All other functions are consecutive functions. They are derived from this primary one (A10–12). Mises endorsed Knies classification of money as a good sui generis, that is, as distinct from consumers’ goods and from capital goods. The reason is, again, that these three types of goods are subject to different laws of valuation and pricing (A79).
- 12Mises argued most notably that the fatal error of the Currency School, which otherwise had sound conceptions that he endorsed in his book, was to regard banknotes as some form of money, whereas it considered demand deposits as pure credit instruments and not as a form of money. This was in Mises’s eyes a distinction without a difference and it led to the practical failure of Peel’s Act. We will deal with this issue in more detail below.
- 13During WWI, Mises refuted the assignment theory in a 1916 journal article “on the classification of monetary theories.” This paper would then be incorporated into the 1924 edition of his Theorie des Geldes und der Umlaufsmittel (chapter 9 of the second part; see B242–63) and remained as an appendix in the 1953 edition (see C503–24).
- 14See North (1993, p. 159).
- 15They are not different in all respects. For example, increasing the supply of fiduciary tends to entail an increase of the price level, just as it would be in the case of an increased supply of money proper or of money certificates.
- 16Unfortunately, the English rendering as Theory of Money and Credit obscured this central theme. We will address the problems of this translation below.
- 17See Menger (1968 [1909], pp. 73–75, 80–91. In the English edition the distinction between inner and outer exchange value was completely dropped. In a footnote (on p. C146) Batson explains: “Since this distinction has not been usual in English terminology, it has been omitted from the present version; and, in what follows, wherever ‘the objective exchange value of money’ is referred to, it is the innere exchange value that is meant unless the contrary is explicitly stated.”
- 18He repeatedly referred to Mathus’s Principles of Political Economy. See especially Menger (1968 [1909], p. 82).
- 19See Menger (1968 [1909], p. 75.
- 20In a passage where he explained that distinction (not translated into English), he stated (A132f., B104): “Both expressions are somewhat odd. But they have become accepted in science ever since Menger used them. Therefore they shall be used where appropriate in the following investigations.” (Beide Ausdrücke sind nicht gerade glücklich gewählt. Aber sie haben einmal in der Wissenschaft das Bürgerrecht erlangt, seit Menger sie verwendet hat; darum sollen sie auch in den folgenden Untersuchungen dort gebraucht werden, wo dies mit Nutzen geschehen kann.)
- 21B200, my emphasis JGH. The word “inner” lacks in the English edition, see C272. Similarly, see the definition of the term “inflationism” on A265 (deleted from the second edition). Mises was reluctant to use the term inflation at all, referring to the reservations expressed by Pigou. He thought scientific analysis could do without them. For a penetrating history of the common definitions of the terms inflation and deflation see Bryan (1997).
- 22A246, B200. Again, the English edition lacks the words “inner” (see C248). The translator, Batson, also tried to make a distinction between Geldwertpolitik, Geldpolitik, and Währungspolitik (see C247, footnote), whereas Mises used all three terms synonymously, as is common in the German-language literature. Similarly, Mises stated that monetary policy in that sense is the “complement” or “corollary” (Gegenstück) of policies designed to influence the prices of single commodities or groups of commodities. Batson translates Gegenstück out of context as “antithesis.”
- 23Amadeus Gabriel highlights the interesting fact that the core idea of the regression theorem can be traced back to the contemporary German literature. See Gabriel (2012) in the present volume, chapter 2.
- 24See A154f., B122f., C164.

