
Men of Wealth
Interlogue Three: I. Hugo Stinnes
HUGO STINNES
ONE CANNOT speak of Krupp before the Great War without thinking of Hugo Stinnes after the war. For one brief, dizzy moment Stinnes was, perhaps, and in a sense, the richest man in the world. In the hot cauldron of inflation the modern ideal of liquidity reached its craziest perfection—liquidity of ownership, the ownership of everything in Germany reduced to complete fluidity, running like a turbulent wild river through the markets. The ownership of office buildings, hotels, apartments changed hands half a dozen times a day like wildcat shares on an exchange. In that amazing epilogue of war, Stinnes, in a delirium of acquisitiveness, poured into his holding companies banks and factories, railroads and power plants, mines and oil companies, steamships, hotels, building blocks, estates by the hundreds. Germans, taught by their war-makers to adore the colossal, opened their eyes and looked with awe at this supercolossal industrial miracle. German business seemed to be divided into two parts—one part belonging to Stinnes, the other distributed among the other millions of Germans.
The vast extent of his possessions in Germany may be imagined from a simple list of some of the odds and ends that dropped into his bag outside Germany as a sort of by-product of his internal acquisitions. He found himself in 1923 controlling 20 coal companies, 11 iron mines, four oil fields and refineries, 16 earthen, stone, and ceramic works, 29 smelting works, 20 metal, machine, wagon, and locomotive works, three telegraph companies, four shipyards, 80 electric plants, eight paper, chemical, and sugar plants, four shoe factories, 47 electric and gas plants, nine shipping companies, 14 newspapers and print works, three cotton and coconut plantations, ten banks and holding companies, 204 selling agencies.
For all this, his fortune, vast for an instant and sensational, possessed no lasting importance. What it was worth is difficult to say. Had the whole tangle of steel and copper mines and mills, factories, banks, hotels, stores, buildings been reduced to marks—billions of billions of marks—and converted into the currency of America or England, they would have fetched just about enough pennies to buy an evening’s bus ride. The whole thing represented a tumescent boiling up of the blood of German industry in a fever of inflation, in the course of which this monstrous growth broke out. It was part of the nightmare of buying when everybody in Germany was running around frantically trying to get rid of their money as if it were a plague. Stinnes understood the crazy game better than others, but not well enough to see it through to the end. He was like a gambler sitting at a table piling up before him mountains of chips which were good for cash in a casino which was bankrupt and on fire in the midst of an earthquake. He began his mad game toward the end of the war. In five years he was dead, and his weird empire was scattered.
Hugo Stinnes, however, must not be dismissed as a mere gambler. He was a leading businessman of prewar Germany. His grandfather, Matthis Stinnes, made a fortune in shipping and coal. Hugo Stinnes was born in 1870, as Bismarck prepared to incite the Franco-Prussian War. At twenty-two he formed his own firm but also took a part in managing the family mining interests. His own business grew enormously, until by 1914 it comprised coal and iron mines, steel mills, railroads, ships, shipbuilding, banking, trading companies. He loomed large in the Ruhr.
He was the leading exponent of vertical combination in Germany. The German pattern of combination was horizontal, beginning with cartels as early as the days of Jacob Fugger. Stinnes was fascinated by the vertical type in which all the stages of production and even distribution, from the raw materials to the finished product, are brought under a central control. In America this had gone far—Carnegie and later Gary and Gates and still later Morgan brought it to full flower in the United States Steel Corporation. The war suddenly gave a swift boost to this type of combination, and Stinnes began to avail himself of the permissions and opportunities of the war. Owning steel and coal industries, he needed lumber for the mine pits. Hence he acquired forests. Having forests for lumber he could use it to make paper. Having paper he could use it in printing plants. Having printing plants he could publish newspapers. And so the endless chain of acquisition went in every conceivable direction. He helped plan the war management of Belgian industry. He spread his control into Belgium and Luxembourg. He took a leading part in the direction of Ruhr industries and used that position to his advantage. He was expanding all through the war.
His method was to acquire mere minority rights in companies. He banked on his personal force to make that dominant. Not tall, but thick-set, erect, heavy-featured, with close-cropped hair, well-trimmed beard, yellow complexion, eyes oblique but shifting and yet penetrating, cool, a calculating machine, talking but little and then in a weary whisper, he nevertheless radiated that mysterious personal force which reduced other men to obedience.
When the war ended and his Belgian and many other semiwar possessions were confiscated, his companies were compensated by the German government, putting him into possession of large amounts of cash. Then, as the inflation got under way, he could, through his own banks and credit agencies, borrow marks to buy shares, which marks he could repay in a few weeks with greatly depreciated currency. And as this process went on Stinnes, coolly calculating the chances, the velocity of inflation, the human elements at work, borrowed and bought and paid his credits until he seemed to be swallowing all Germany, and the whole world looked daily at the mounting expansion of his interests. He seemed to be getting everything—chemical plants, lighting plants, explosives, cellulose, newspapers, publishing houses, brass and copper mills, automobile factories, film companies, shipping lines, big banks, banks with branches all over Germany, mortgage companies, insurance companies, companies of all sorts in Russia, Austria, Czechoslovakia, Poland, Rumania, Switzerland, South America. A cyclone seemed to be sweeping everything in Germany into his hands. Then came the stabilization of the mark. All the tremendous forces that had been driving everything his way suddenly ceased. And Stinnes, too. Only fifty-five, he seemed to cease with the storm. He died on April 10, 1924. His two sons quarreled over the unmanageable loot. They were utterly unequal to the task, and so, in all likelihood, was Stinnes himself. In 1925 the whole thing broke down. When the brothers and other parties interested finished there was left a few coal mines, two iron- and steelworks, four metal-trading firms, four shipping companies, and a few miscellaneous items.

LAND FORTUNES
Those fabulous fortunes of the great feudal princes of the East naturally invite the imagination of those who are interested in the subject of wealth accumulations. And the same observation goes for the great land fortunes of England, many of which still exist.
It cannot be said that they are without economic significance, since they perhaps control the economic life of the regions where they exist. But they are certainly without significance for us here. They are no part of the pattern of the modern world. They hang on as a remnant of a world that is dead in most places and dying everywhere. Not only do they belong to the type of fortune of the Middle Ages but a few of them are actually those very fortunes. They are either feudal or semifeudal, and there is no essential difference between them whether they be found on the banks of the Ganges or Sweet Avon. Essentially they involve the ownership of the land as the indispensable condition of controlling the product of the dweller upon it. In earlier times or in more backward countries their ownership of the land was accompanied by political rights of the most despotic character over the lives and bodies of the tenants. In more modern and civilized areas these political rights have been either greatly reduced or wholly extinguished.
One hears of those storybook or cinemalike Indian maharajas who are invariably represented as possessing fabulous stores of gold and precious stones and sources of income that are mysterious but abundant. First of all, there is a good deal of exaggeration about them all, a very considerable lack of precise information. But aside from that, they are anachronisms in the world’s economy.
Most often reported among these Oriental princes and unfailingly described as the richest man in the world is the Nizam of Hyderabad. Hyderabad is an Indian state about the size of Idaho, with a population of about 12,500,000, and lying on the boundaries of Madras and Bombay. The Nizam is the principal Mohammedan ruler of India, and the state itself has a lot of good agricultural land, and some coal, copper, iron, diamonds, and gold. But none of these resources has been very vigorously worked. Doubtless the Nizam enjoys an immense income. But we are asked to believe that he has $500,000,000 of gold stored away in a strong room, part of his personal fortune, and another $2,000,000,000 in jewels.
This is a huge amount of gold in a country that operates on the silver standard, and, of course, it is gross exaggeration. But exaggerations pursue one remorselessly through the mazes of Indian fortunes. One hears about Akbar, first of the Great Moguls in the sixteenth century, who had an income of $200,000,000 a year and who on festival days weighed himself against gold coins and gave his weight in gold to the poor. Then there was Shah Jahan who built the Taj Mahal, whose peacock throne cost $32,000,000, and who enjoyed an income from his land alone of $22,000,000. But neither raked in so rich an income as the later Mogul Aurangzeb who collected $385,000,000 a year. These utterly fictitious statistics, so general when dealing with Indian fortunes, leave one quite lost as to the facts, which, of course, do not remotely approximate these figures.
The English land fortunes, of course, are for the most part almost wholly hereditary fortunes running back over periods of varying length. Few if any of them extend back to the Middle Ages. In 1911 when a new Domesday Book was compiled, but one landed estate turned up which had been included in the original Domesday Book compiled in 1086. It was a small estate of 2000 acres in Somerset that had cost eleven pounds in the eleventh century and was valued at 27,000 pounds in 1911, with an income of 1400 pounds. It remained in 1911 in the name of the same family that had owned it in the year 1086.
As a matter of interest I need but mention a few of the larger estates that remained intact in 1883. I give below thirteen of the largest:
NAME |
RENT-ROLL |
| Norfolk, Duke of | £269,698 |
| Bute, Marquis | 186,155 |
| Northumberland, Duke of | 182,557 |
| Ramsden, Sir J. W. | 166,681 |
| Derby, Earl of | 163,326 |
| Devonshire, Duke of | 145,860 |
| Bedford, Duke of | 141,549 |
| Tredegar, Lord | 124,598 |
| Calthorpe, Lord | 122,628 |
| Dudley, Earl of | 120,442 |
| Haldon, Lord | 109,275 |
| Anglesey, Marquis of | 107,361 |
| Cleveland, Duke of | 100,485 |
The largest in area was that of the Duke of Northumberland, which embraced 191,480 acres. The largest rent-roll, however, was that of the Duke of Norfolk who then collected 269,698 pounds a year from his tenants, though he had far fewer acres. But some of them were located in the choice districts of London.
Some of these estates embrace a good deal of worthless lands; others include whole towns and valuable timber and mineral rights. But they are not characteristic of the existing economic system and under the impact of income and inheritance taxes are being very seriously reduced and in some cases broken up.

DYNASTIC FORTUNES
The dream of the rich man, particularly the parvenu of other days, as soon as he looks about him and surveys his glory, is to perpetuate it in a dynasty. This was not so difficult in the feudal era when wealth rested upon the indestructible land and men could entail their fortunes through the practice of primogeniture. But when the laws against entails were passed, the days of the dynast became somewhat more difficult. Nevertheless, aristocratic families in England and Germany and Spain and other Continental countries have found ways of transmitting their wealth from one generation to another with a good deal of success.
But in America, where the land has got pretty generally distributed, where fortunes are invested rather in industrial and commercial enterprises, the fear of the dynast has been much diluted. One of the oldest fortunes is that of John Jacob Astor. Its founder died in 1825, leaving $25,000,000. When his son died in 1890 there were a hundred millions to divide. This went to two sons—$50,000,000 to each. It grew in their hands. One left $150,000,000, the other $75,000,000. The owner of the $150,000,000 took himself off to England where whatever of dynastic energy is left is a rash upon England’s limbs, not ours. The brother with the $75,000,000 died in America leaving his fortune among numerous heirs. The bulk of the American Astor fortune is in the hands of William Vincent Astor—$87,000,000. There are a few stray millions scattered about, but it is far under the $250,000,000 it was twenty years ago. And it continues to wane under certain new pressures while its owners have ceased to be dominating factors in any important business.
These pressures are several. They are the logical development of the whole system. One of them is the inheritance tax. New social philosophies are now powerful. But state necessities are even more imperative. Governments need so much taxes that ways have to be found to get them. The inheritance tax is the one that generates the least effective resistance. During life, income taxes now weaken the power of the fortune to accumulate, and, at death, the government steps in to take the lion’s share.
The Vanderbilt fortune is one in point. Until his death old Commodore Vanderbilt strode the country like a colossus with his hundred million. His son William H. made it two hundred millions. He owned the New York Central Railroad as a man owns his corner store. But he found it wasn’t healthy for one man to control a great railroad. He found it to his advantage to sell a lot of his control. When he died he left eight children. Eight children subject a fortune to a very enfeebling division. But his sons, Cornelius and William K. got $50,000,000 each. Cornelius’ fortune at his death went to several children, but Alfred got the bulk, $80,000,000. When he died it had shrunk to $35,000,000. It was split $5,000,000 to his son William, $8,000,000 to the widow, and the balance to two sons of his second wife. William K. left $100,000,000. It went to two children, Consuelo and William Harold. The former withdrew her fortune to a ducal dynasty in England. Among the various heirs, a good slice drifted into the hands of Frederick W. Vanderbilt. He died in June, 1938. His estate, valued at $72,588,000, was liquidated in 1939, and the Federal government and state of New York took $41,272,000 of it in taxes.
Andrew Carnegie was worth at one time $300,000,000. He gave away most of it to the Carnegie Corporation for libraries and education. When he died his estate showed $23,000,000 left. His partner, Henry Clay Frick, left an estate valued at $150,000,000. $117,000,000 went to public benefactions. His children got $25, 000,000, and this was subject to heavy inheritance taxes that reduced it by forty per cent.
The Gould fortune was a great bolus of wealth. When Jay Gould died it had swollen to about a hundred million. He tried to entail his estate with a trust for his son, George J. When George died after many financial disasters he left $30,000,000 in another trust, but much split up: $10,000,000 in trust for seven children by his first wife, $4,000,000 for the three children of his second wife, and the balance in trust for both broods.
Even in England many noble gentlemen with immense estates have found them too costly to keep up after the income-tax gatherer had got through with them, and the inheritance-tax office has been doing its deadly work upon what is left.
The Mitsui fortune has endured because of the peculiar social system under which it exists. It has been possible to organize a family there with sanctions behind its decrees that would not be possible in America, France, or England, or, for that matter, in any large modern state. Then, by separating the family organization and the business organization and putting the business into the corporate form, the whole structure has been given a quality of permanence.
But the very corporate form that has served the Mitsuis so well is actually tending to break up family control of business in this country. The corporate form makes it possible for men to distribute their investments over a wide range of industries. Modern investment studies have convinced owners of immense fortunes that the greatest safety lies in diversification rather than control of an industry. Therefore the fortunes of very wealthy men will be found spread around in the stocks and bonds of scores, and in some cases of hundreds, of corporations. The result is that they hold a dominating interest in none and exercise over industrial policies, save in a few cases, but very little influence.
A third element now enters. The uncertainties of the world, the wars, depressions, and political irritations, have induced many men to take refuge in government bonds. They do this for another reason—to escape the income taxes. All these influences tend first to minimize the power of dynastic families over the industries founded by their ancestors and second to break up those fortunes, first through income and inheritance taxes, second through family distributions, and third through the erosion of the last dozen years.
If we will go back one hundred years we will find that the largest fortunes in America were the following:
| John Jacob Astor | $25,000,000 |
| Stephen Van Rensselaer | 10,000,000 |
| Stephen Girard | 7,500,000 |
| Peter C. Brooks | 6,500,000 |
| William B. Astor | 5,000,000 |
| Amos and Abbot Lawrence | 5,000,000 |
| Peter G. Stuyvesant | 4,000,000 |
| James Lennox | 3,000,000 |
| Peter Schermerhorn | 2,500,000 |
| John P. Cushing | 2,500,000 |
| William B. Crosby | 1,500,000 |
| Isaac Bronson | 1,500,000 |
| Thomas H. Perkins | 1,500,000 |
| John Bolen | 1,250,000 |
| Henry Brevoort | 1,000,000 |
| Gouverneur Morris | 1,000,000 |
| John Mason | 1,000,000 |
| Jonathan Hunt | 1,000,000 |
| Samuel Appleton | 1,000,000 |
| Robert G. Shaw | 1,000,000 |
Some of these, of course, are merely good guesses at the fortunes of these men, but they serve to show us how few are left today. There were a few others whose fortunes cannot be even guessed at—David Sears, millionaire stockholder; Jacob Little, security speculator; August Belmont, representative of the Rothschilds.
In the world of today the way of the dynast is a hard one.
Brown Brothers
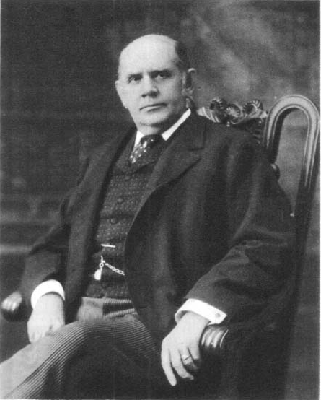
MARK HANNA

